 Is Donald Trump working on 'something much bigger' for Middle East after Iran war? Here's what report says
 Gold, silver prices today, September 6, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Who is Dinesh Sharma? New Lt Governor of Andaman and Nicobar Islands
 NEET-UG 2026 Paper Leak Case: 14th accused Sheshrav Suryawanshi sent to judicial custody till September 18
 Women’s Asia Cup 2026: India hammer Pakistan by 7 wickets, claim top spot in Group AWomen’s Asia Cup 2026: India hammer Pakistan by 7 wickets, claim top spot in Group A
 Harmanpreet Kaur makes history, becomes first cricketer ever to achieve remarkable feat
 'This is not politics': Brian Lara makes emotional appeal for Imran Khan’s proper medical treatment
 Suresh Raina reveals MS Dhoni’s first reaction after he announced retirement minutes later
 'We are always one step ahead': Deepti Sharma sends strong message to Pakistan ahead of Women’s Asia Cup clash
 Mohanlal's L367 titled Operation Ganga, Vishnu Mohan film has this connection with Dhurandhar, Pushpa, Kantara
 Mirzapur The Movie: Amol Parashar goes all out, calls Pankaj Tripathi, Divyenndu, Rasika Duggal, Harshita Gaur, Ali Fazal 'craftiest actors of our generation'
 Lust Stories 3 OTT release date: Ali Fazal, Aditi Rao Hydari, Siddharth, Vijay Varma-starrer to premiere on Netflix
 Mahakavya Shri Ramayan Katha: Amid massive backlash, Anjali Arora admits playing Mata Sita has been responsible journey: 'I knew from beginning that...'
 Hanuman Ansh declared tax-free in Uttarakhand, CM Dhami congratulates team for making 'inspirational film'
 West Bengal News: TMC office attack? Abhishek Banerjee questions action against BJP
 Nepal Floods: Water Levels In Three Major Rivers Of Nepal Cross Danger Mark Amid Heavy Rain
 Trump Warns Iran Of ‘Biggest Attack’ As Us Launches Fresh Strikes After Attacks On American Forces
 Nepal Flood: Drone Camera Captures Moment Glacier Collapsed On Lirung Peak Before Nepal Flood
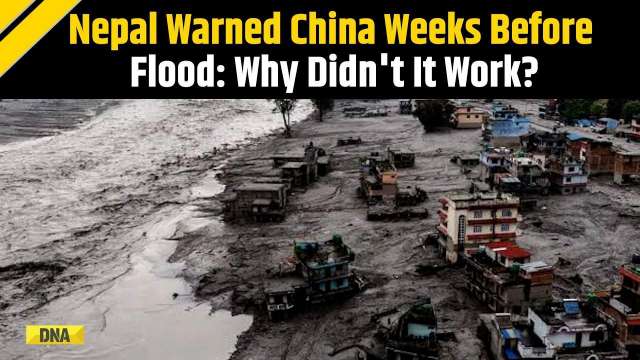 Nepal Warned China Weeks Before Flood Why Didn't It Work | Data Sharing & Warning GapsGold, silver prices today, September 6, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Tata Sons Chairman Race: T V Narendran, Saurabh Agrawal, Ashish Chauhan among top contenders
 Tata-owned JLR plans 4,000 UK job cuts amid profit slump and US tariffs
 Gold, silver prices today, September 5, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 NSE IPO Gets SEBI Nod: What we know about issue size, dates and selling shareholders
 From Suhana Khan to Rasha Thadani, Ananya Panday: Gen-Z actresses acing modern-day Radha look in Janmashtami
 Teacher's Day 2026: From Thalapathy Vijay to Jyothika, 5 popular on-screen gurus from South that became household names
 OTT Releases This Week: Dhamaal 4, Gandhari, DC, Bigg Boss 20; Indian movies, series to watch on Netflix, JioHotstar, ZEE5
 Shah Rukh Khan in Darr, Akshay Kumar in Haiwaan, Ajay Devgn in Kaal: When Bollywood superstars dared to play villains
 As Jassi Jaise Koi Nahin completes 23 years, 5 times when Mona Singh stole limelight, became scene-stealer in biggest Bollywood films and seriesWho is Dinesh Sharma? New Lt Governor of Andaman and Nicobar IslandsNEET-UG 2026 Paper Leak Case: 14th accused Sheshrav Suryawanshi sent to judicial custody till September 18
 Who is Ritesh Hange? Chetan’s friend and the third accused in Ketan Agarwal murder case
 PM Modi at SRCC: ‘Half-filled glass’, GDP growth, ‘fragile five’ to fastest-growing economy; key remarks
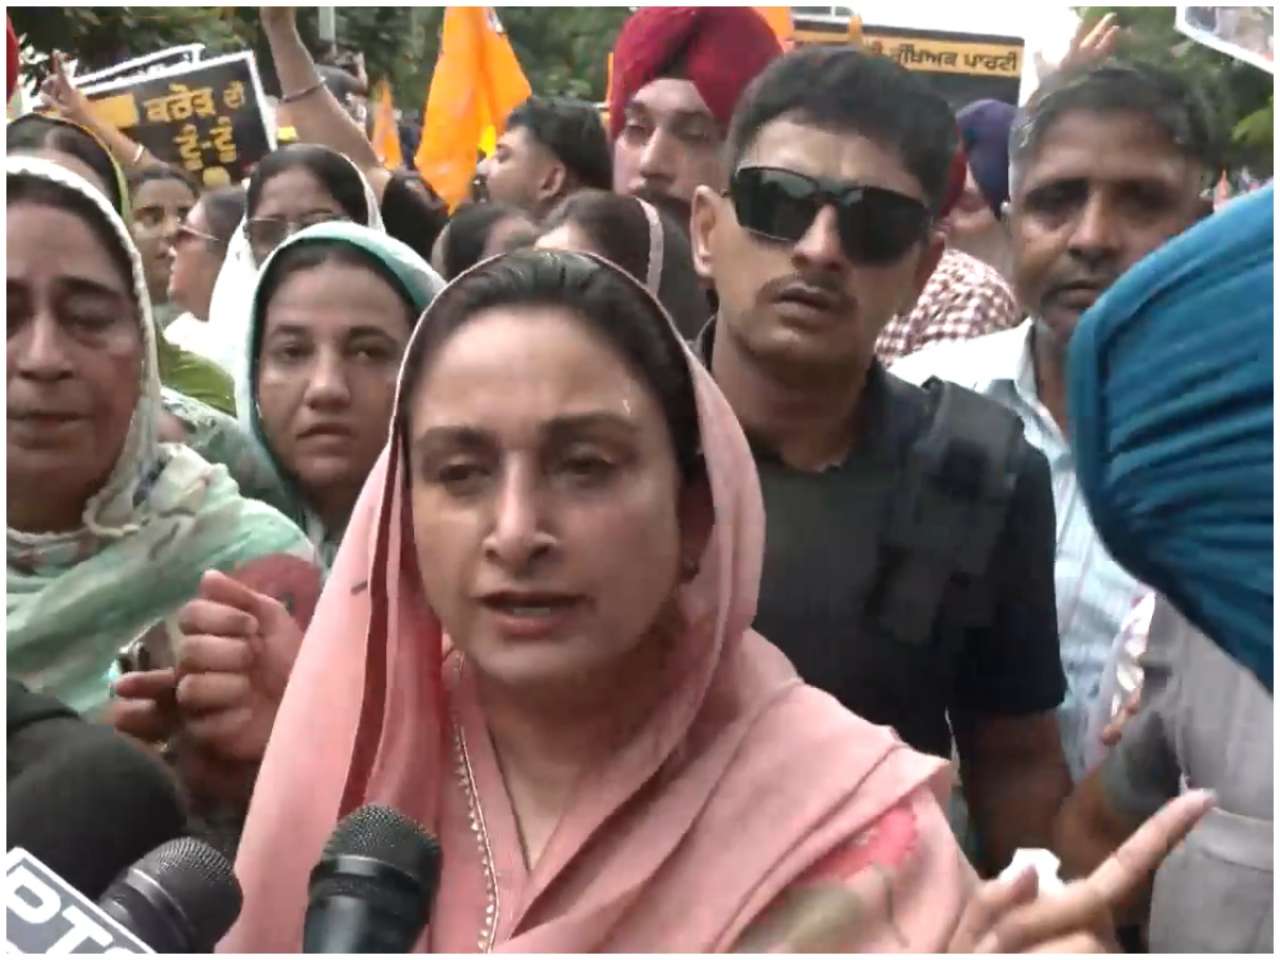 Harsimrat Kaur Badal detained: What happened during SAD’s Chandigarh protest?
 Teachers’ Day 2026: Heartfelt wishes, messages to make your favourite teacher feel special
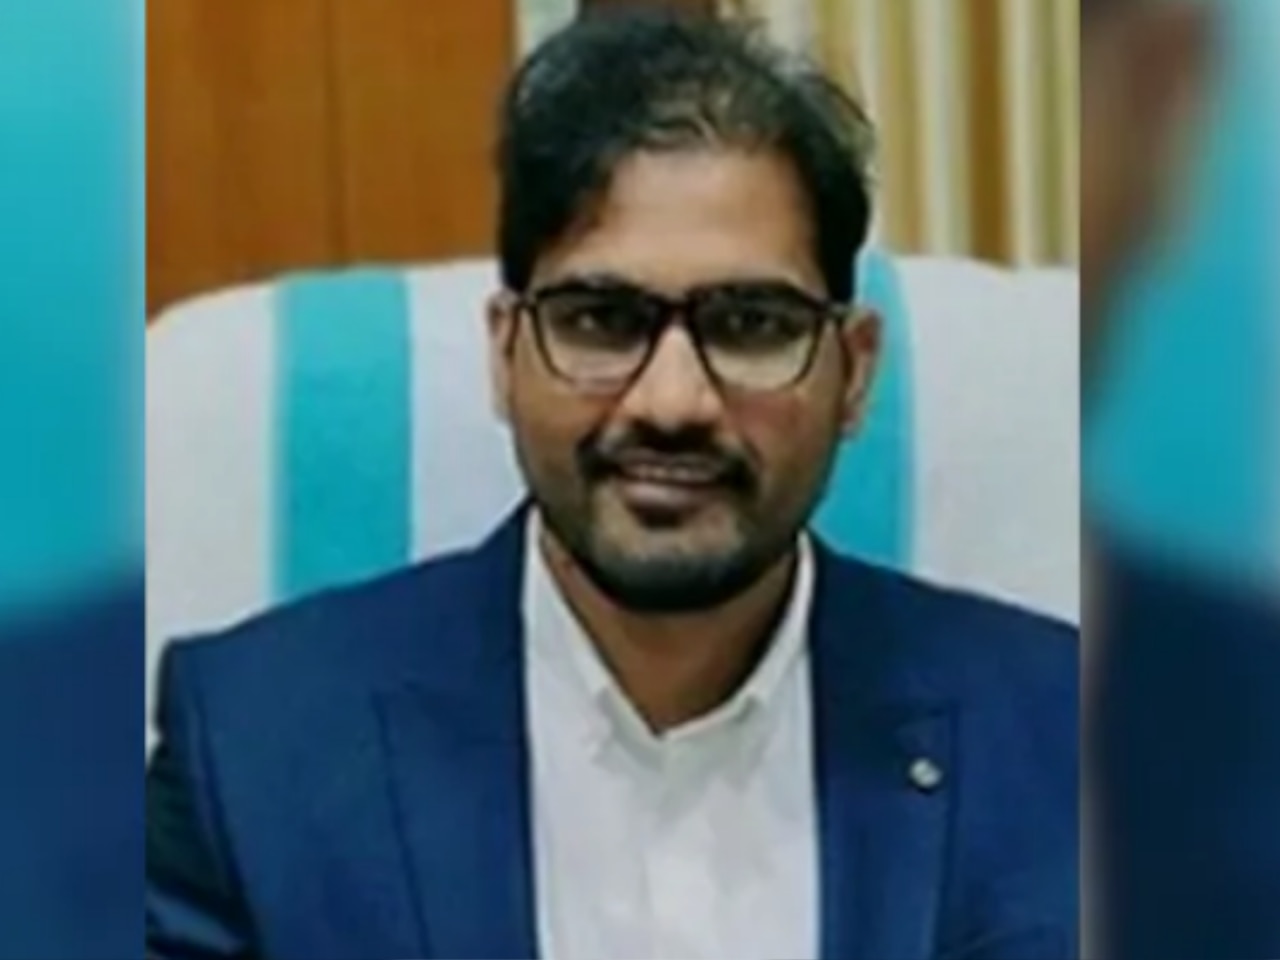 Who is Gyanendra Kumar Gangwar, IAS officer arrested in KPSC exam irregularities case?
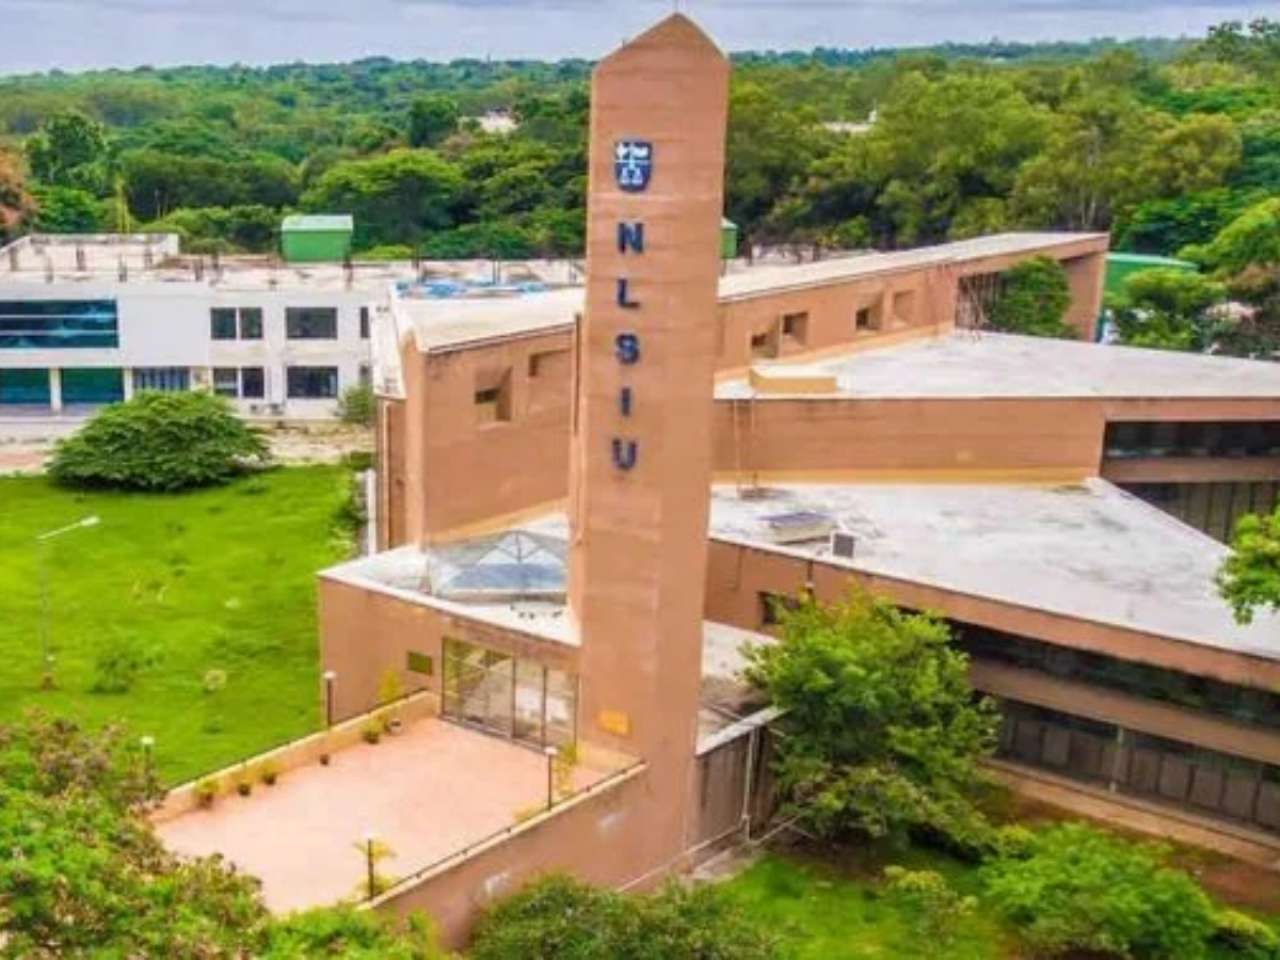 NLSIU cancels convocation amid row over CJI Surya Kant's proposed presence; CJP reacts
 GATE 2027 Registration: Application form to be available from August 27, check direct link, documents required and more
 UPSC Direct Recruitment 2026: Applications open for 80 Assistant Provident Fund Commissioner posts
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
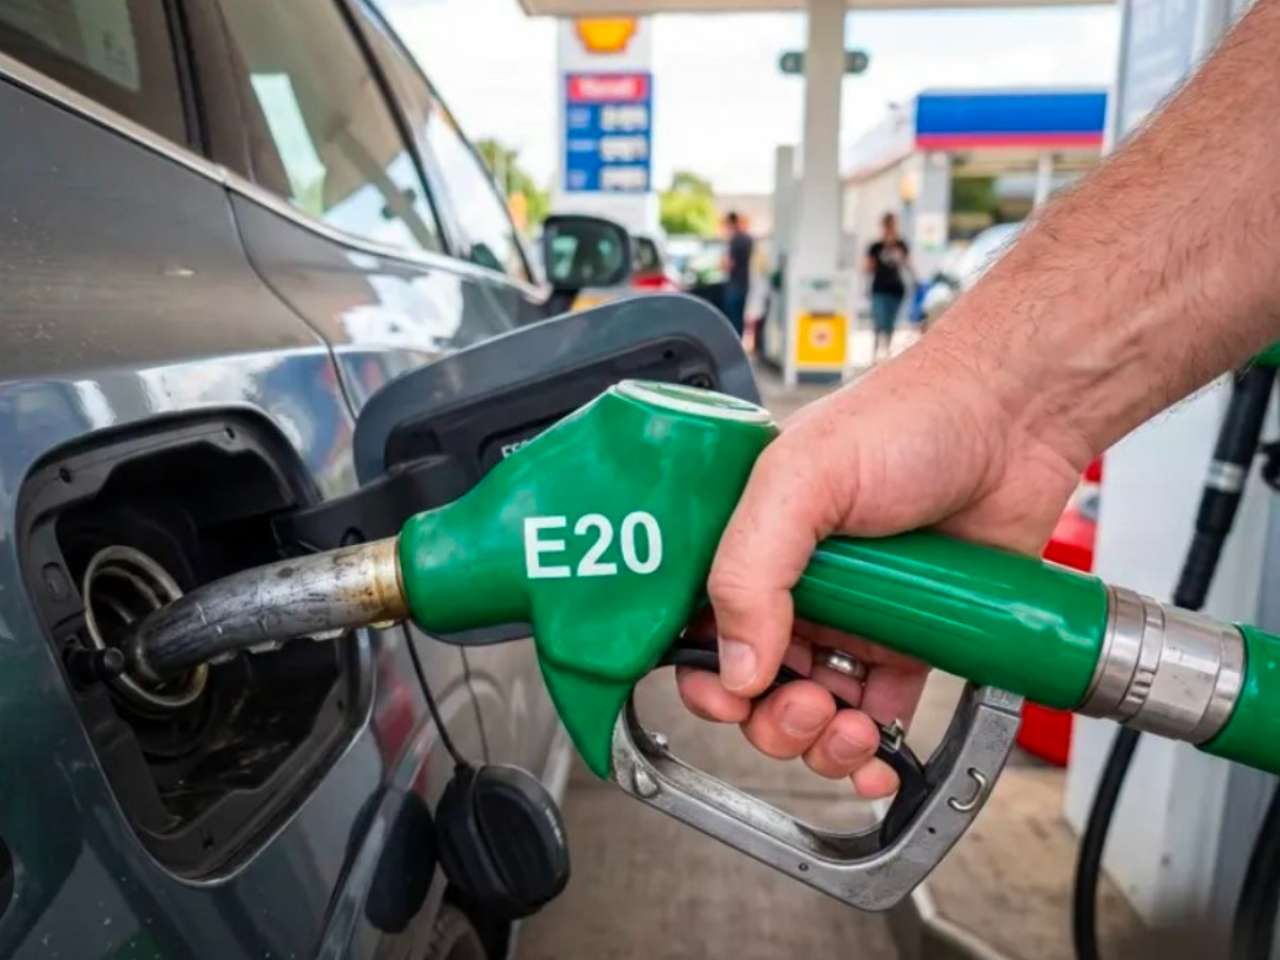 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
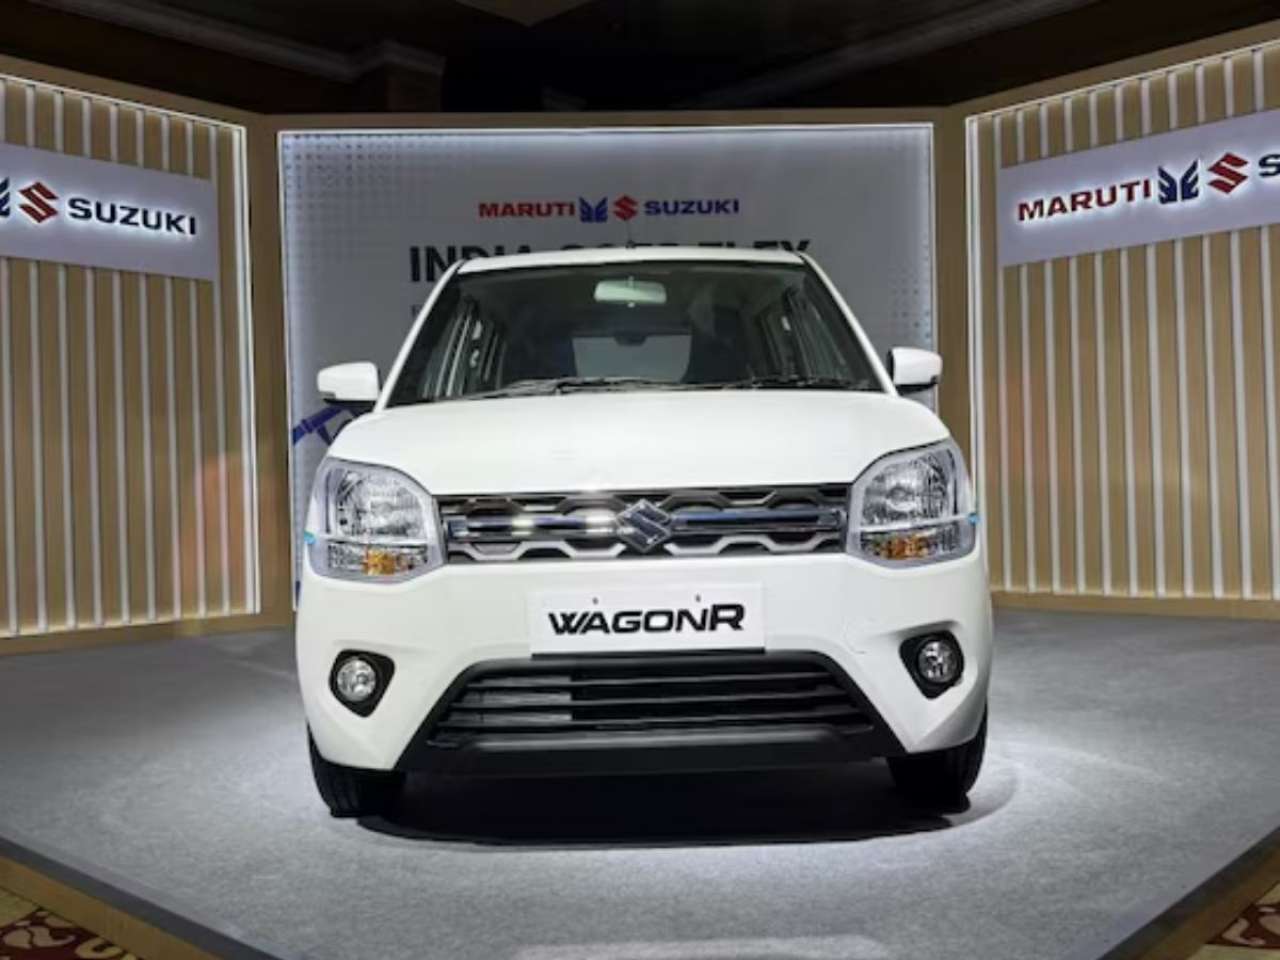 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
 Hyundai Creta 2026 Facelift Explained: What’s new, what’s gone, what it costs
PERSONAL FINANCE
A good borrower, with good repayment record can ask for higher limit to keep credit utilistation levels low

Updated : Dec 24, 2018, 06:55 AM IST


It is said that a bank is a place that offers you a loan when you don't need it. The same can be said about a credit card limit. When you least expect or want to increase the credit limit on your credit card, you will get a call from your bank saying you have a pre-approved credit limit upgrade. And all you need to do is say yes and the limit on your card will be increased. But is advisable to increase the credit limit on your card? Is there a good time to do so? Is there a bad time to do so? DNA Money spoke to experts to help understand the nuances of a higher credit card limit. Read more to find out.
Good borrower: When it comes to being a borrower, there is such a thing called being a good and a bad borrower. If you are a good borrower, it's okay to ask for a credit line increase in certain circumstances. Hrushikesh Mehta, Country Manager – India, Clearscore Technology Services says, "The best time to apply for an increase in a credit card limit is when you have a good payment track record (hence, a good credit score) and you have low debt levels. For example, if you have recently paid down a loan or are close paying one down you would have a better chance at a limit increase."
In short, if you've shown good payment behavior, you stand a better chance of getting a credit limit increase.
When your spending behavior changes: If you are a good credit card borrower, who pays the card bill on time and is using the card for convenience as not as a source of financing, you can go ahead and ask for an increase in credit limit in certain conditions. Samant Sikka, CEO and Founder at Sqrrl - a money investment app says, "If you are a good borrower and there is a change in your spending pattern then it's completely alright to ask for a credit hike. For instance, if you normally charge Rs 50,000 on the card monthly, but now decide that you will start adding your monthly utilities say for Rs 25,000 on the card as well. In such a case your spending pattern has changed. It's okay to ask for the credit limit increase, to keep a buffer. The intention should not be about rotating credit, rather to manage payments seamlessly."
To keep credit utilisation low: Another reason to ask for a hike in credit limit is to keep credit utilization low. Ranjit Punja, CEO and co-founder Creditmantri says, "The right time to seek the credit limit is when you are utilising a large percentage of your credit limit like 70-75% of your credit limit. Or maximising your credit limit. It's a good idea to seek an increase in the credit limit on your card then."
Remember if you are using around 70-80 % of your credit limit, it's not seen as a good thing by the credit bureaus. Punja says, "Credit utilisation of under 50% has a positive impact on your credit score. If your credit utilisation is too high, it's a good time to ask for increase credit limit, so the credit utilisation falls to under 50%."
Remember, any credit increase request must be made only if you are a good borrower, pay your credit card bill every month in full and don't roll over any credit. Punja says, "You have to be cautious when you ask for a credit limit increase. You may feel as if you have incremental cash and might go overboard and if you are unable to pay, you will end in a debt trap."

Recent loans: According to Mehta it is not wise to apply for a limit increase if you have recently (within two months) applied for any credit product. It will show the bureaus that you are desperately looking for credit or are credit hungry and will impact your credit limit negatively. The more credit or loan inquiries you make will bring your credit score down. Wait for a cooling off period of six to twelve months or so.
Too much-unsecured debt: Debt can be both secured like a home loan or an unsecured debit-like credit card or personal loan. Anubhav Jain, head of risk and co-founder Qbera.com says, "If you have too much of unsecured debt already, like a couple of credit cards, and a personal loan or so and if you go for an increase in credit limit on your card, the bureaus will see you as someone who is hungry for credit. Especially if you have a high unsecured debt as a percentage of your total debt." So in such a case, you should not ask for an increase in your credit limit.
Credit problem: If you are someone who is unable to handle credit well, you should stay away from asking for an increase credit limit. Ideally, if you are a credit junkie, there's a chance that the lender will deny you any credit as your credit score would be already poor. In such a case making a request for extra credit will simply work against you and decrease your score further.
Traveling aboard: Should you request an increase in credit limit while traveling abroad? The experts we spoke to were divided in their opinion. According to some, if you are someone who is asking for an increase in credit limit to get credit, then don't ask for it. If you are taking it because using the credit card for convenience as compared to carrying cash, then you could go for a higher limit.
Some said that its okay to ask for an increased line of credit while traveling abroad even if it is taken for credit purposes and not just convenience, provided, you are 100% certain that you will be able to pay off the total amount the next month and not roll over. Else you might just enter a debt trap.
In short, if you are a good borrower and wisely ask for an increase in credit limit, it will work for you and help you increase your credit score. But, if you are a poor borrower, asking for an increase is a bad idea.