 Trump dismisses calls to slow down AI development: 'Negative forces bringing it up'
 IND vs AFG 1st T20I: India hammer Afghanistan by 7 wickets; Abhishek Sharma’s 82, Arshdeep’s 3-fer seal win
 From Kerala to Tamil Nadu: Why four Opposition CMs skipped BRICS dinner despite invite
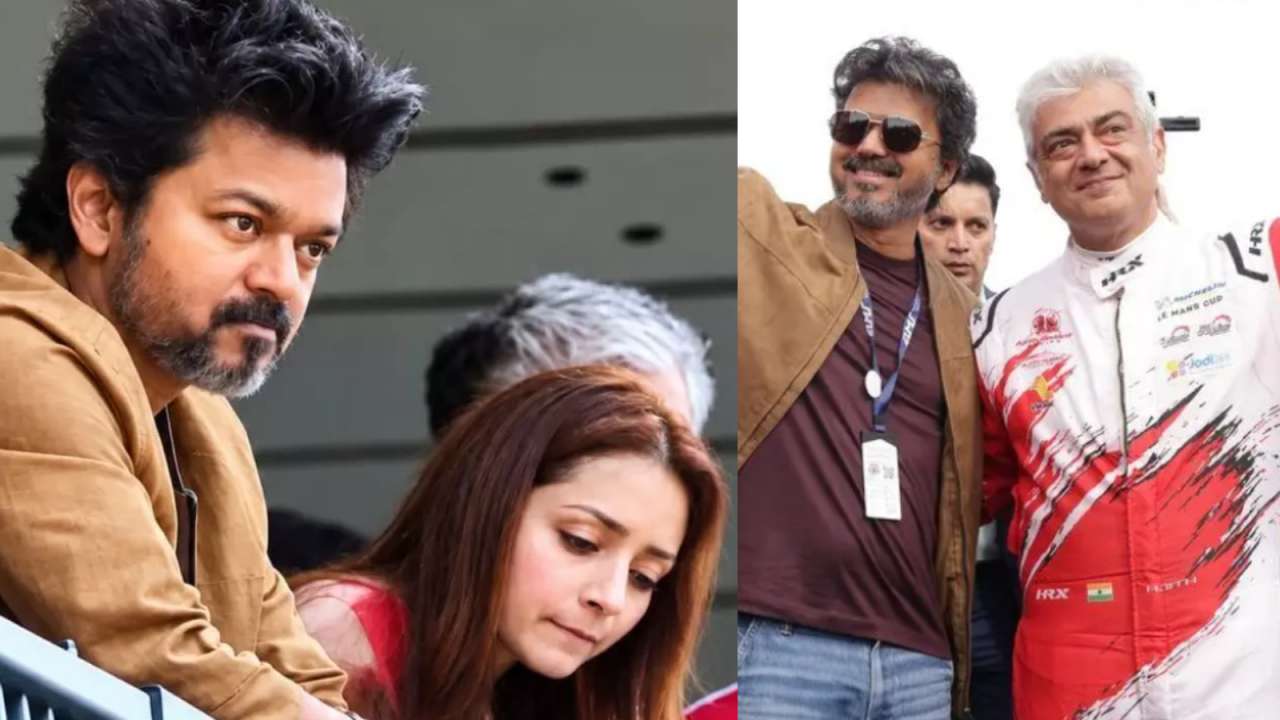 'Indian version of Coldplay kiss cam': Netizens react as Vijay, Trisha's awkward moment from Ajith Kumar's Silverstone race goes viral
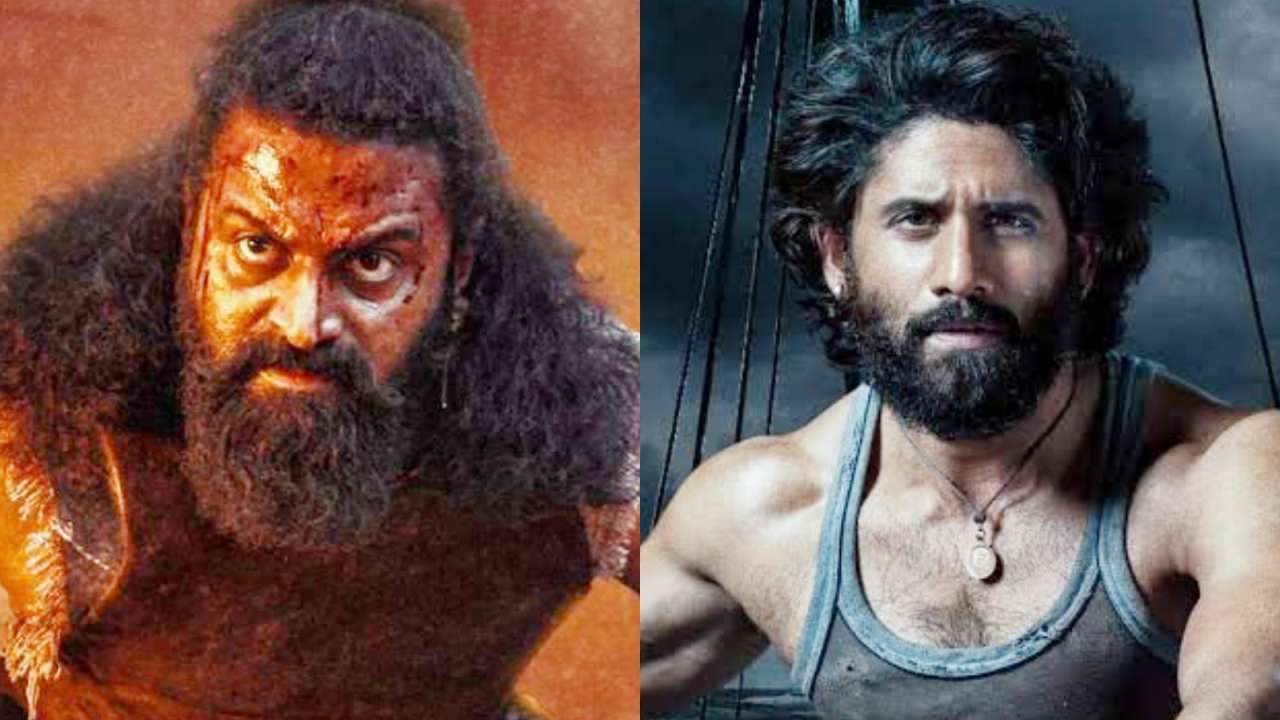 SIIMA 2026 winners list: Kantara Chapter 1 wins Best Film; Rishab Shetty, Naga Chaitanya bag top acting honoursIND vs AFG 1st T20I: India hammer Afghanistan by 7 wickets; Abhishek Sharma’s 82, Arshdeep’s 3-fer seal win
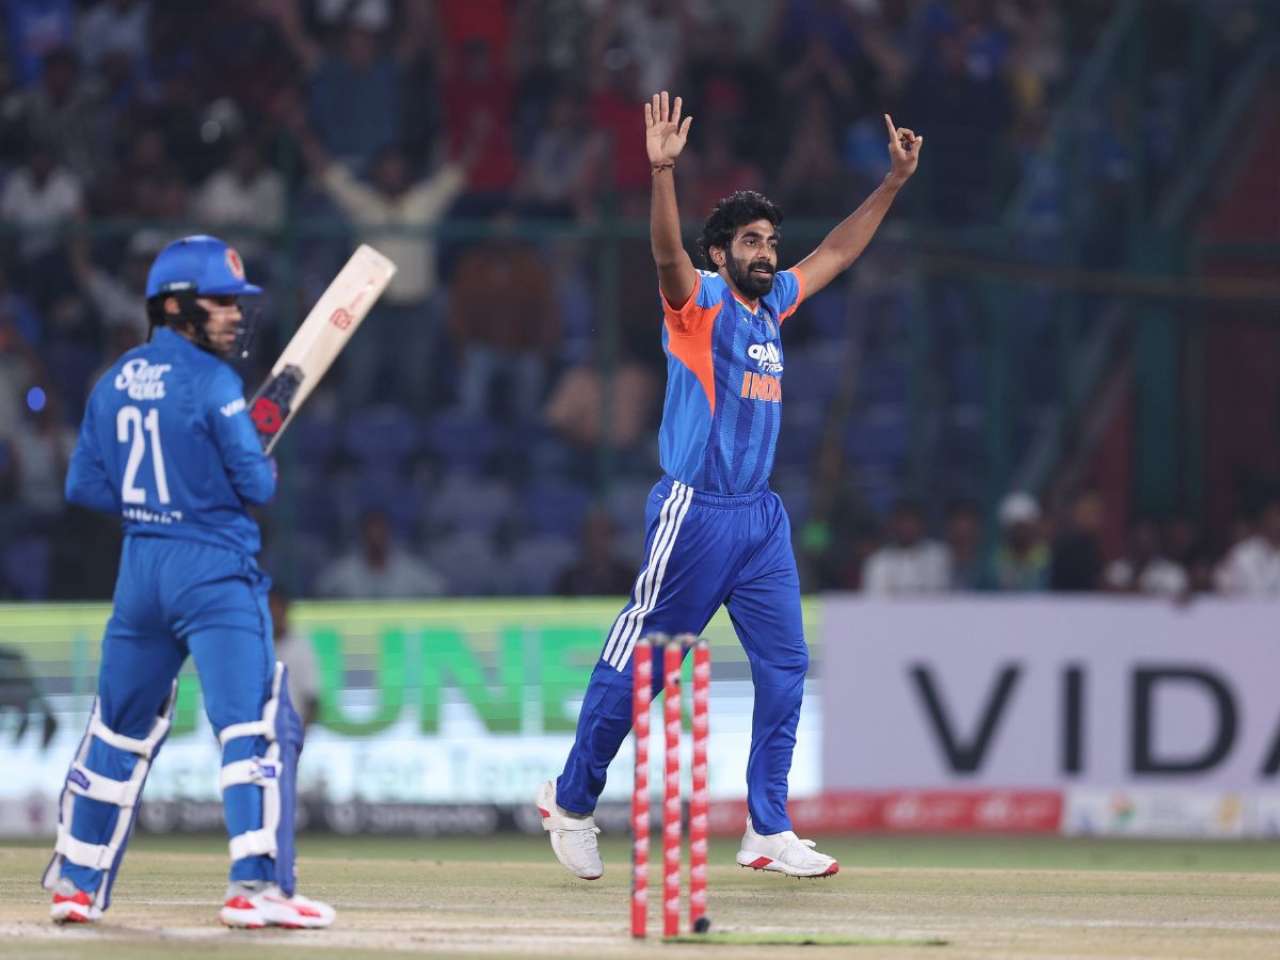 IND vs AFG 1st T20I: Jasprit Bumrah breaches 350-wicket barrier in T20s, joins elite club with Bhuvneshwar Kumar
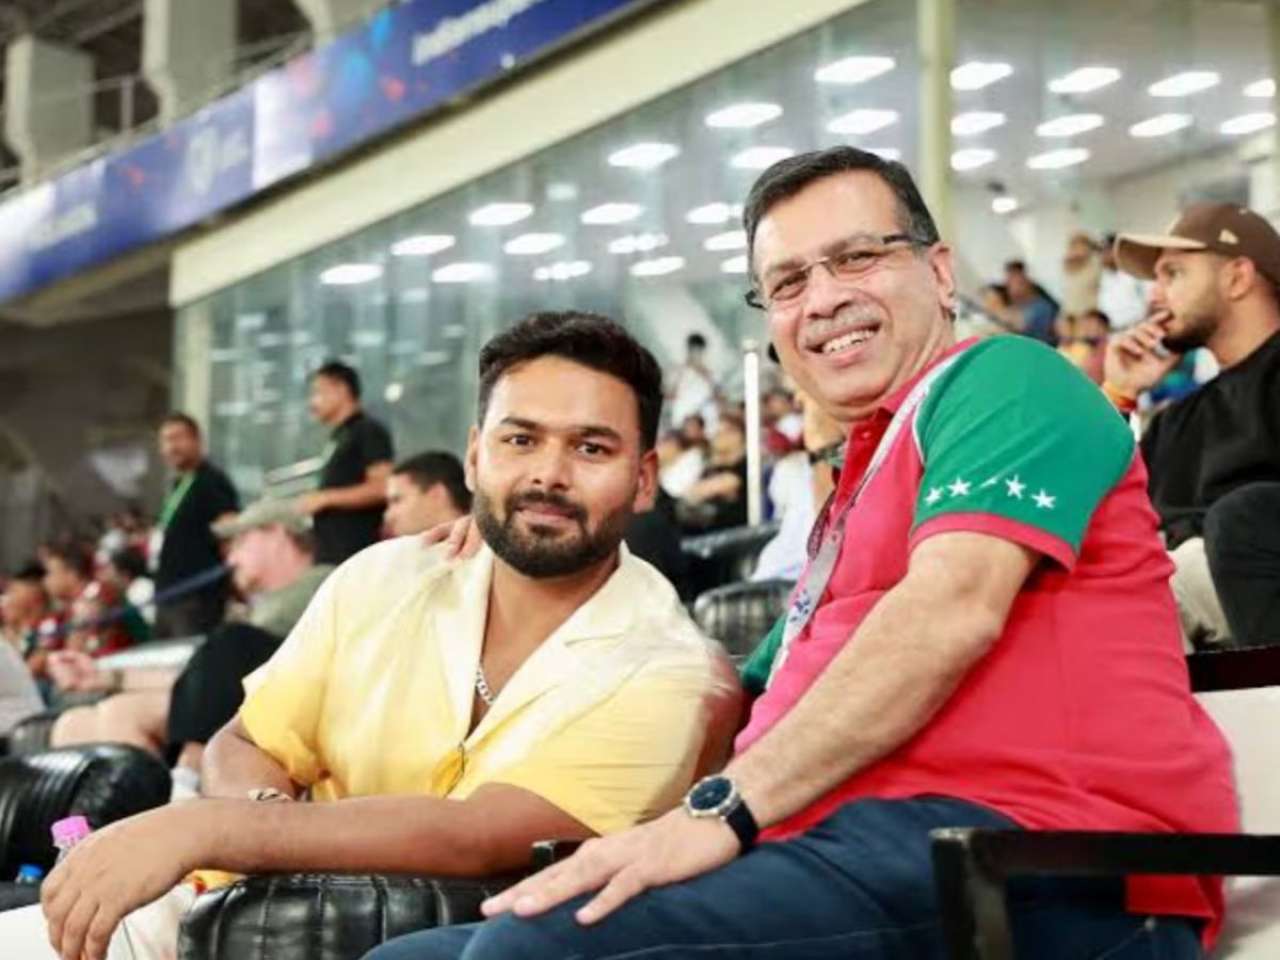 'Wasn't just about the trade': LSG owner Sanjiv Goenka breaks silence on last conversation with Rishabh Pant
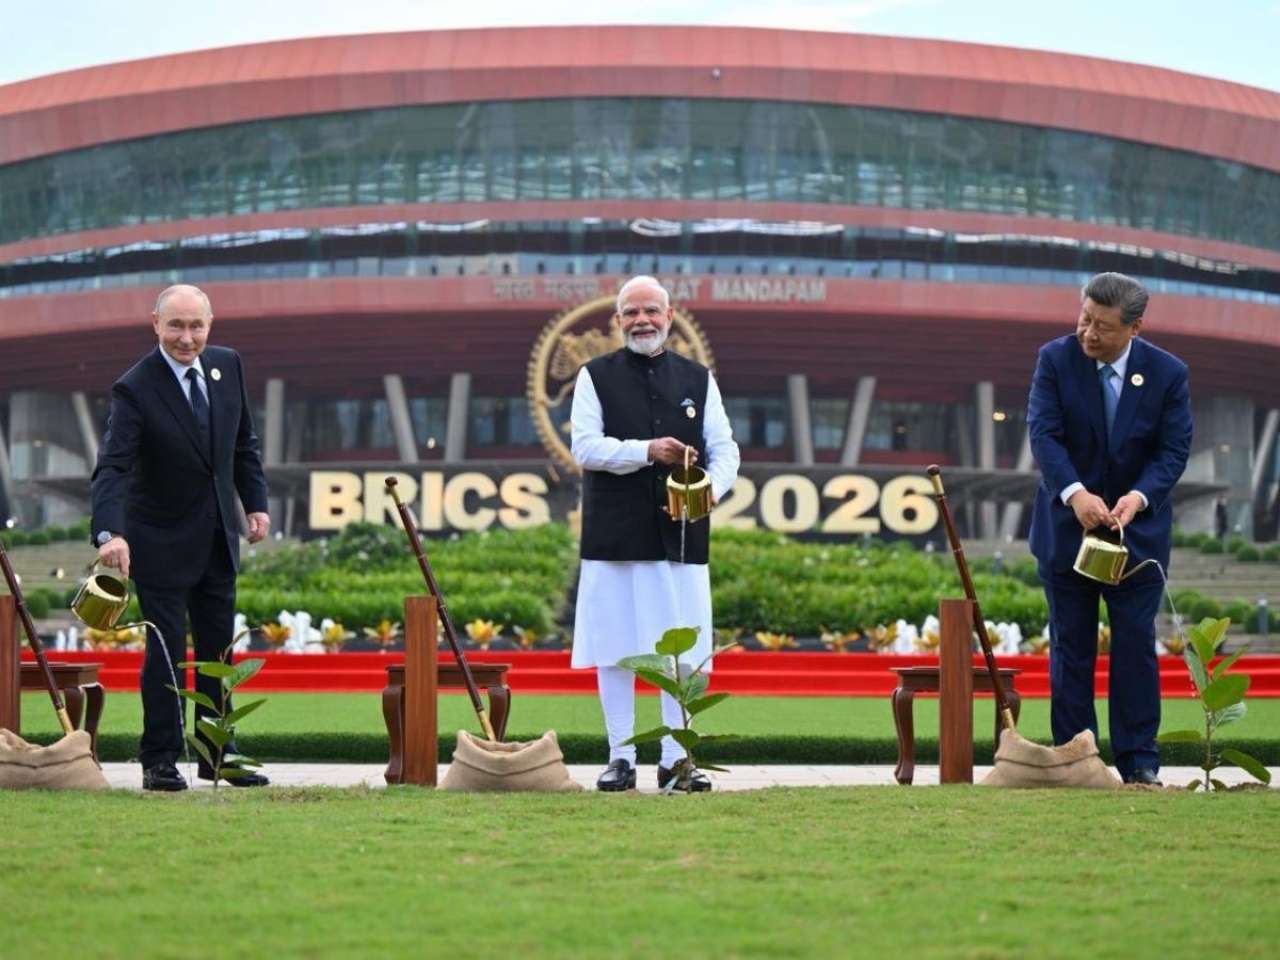 'Together in Mother India': How one powerful BRICS picture prompted Ravi Shastri’s proudest moment
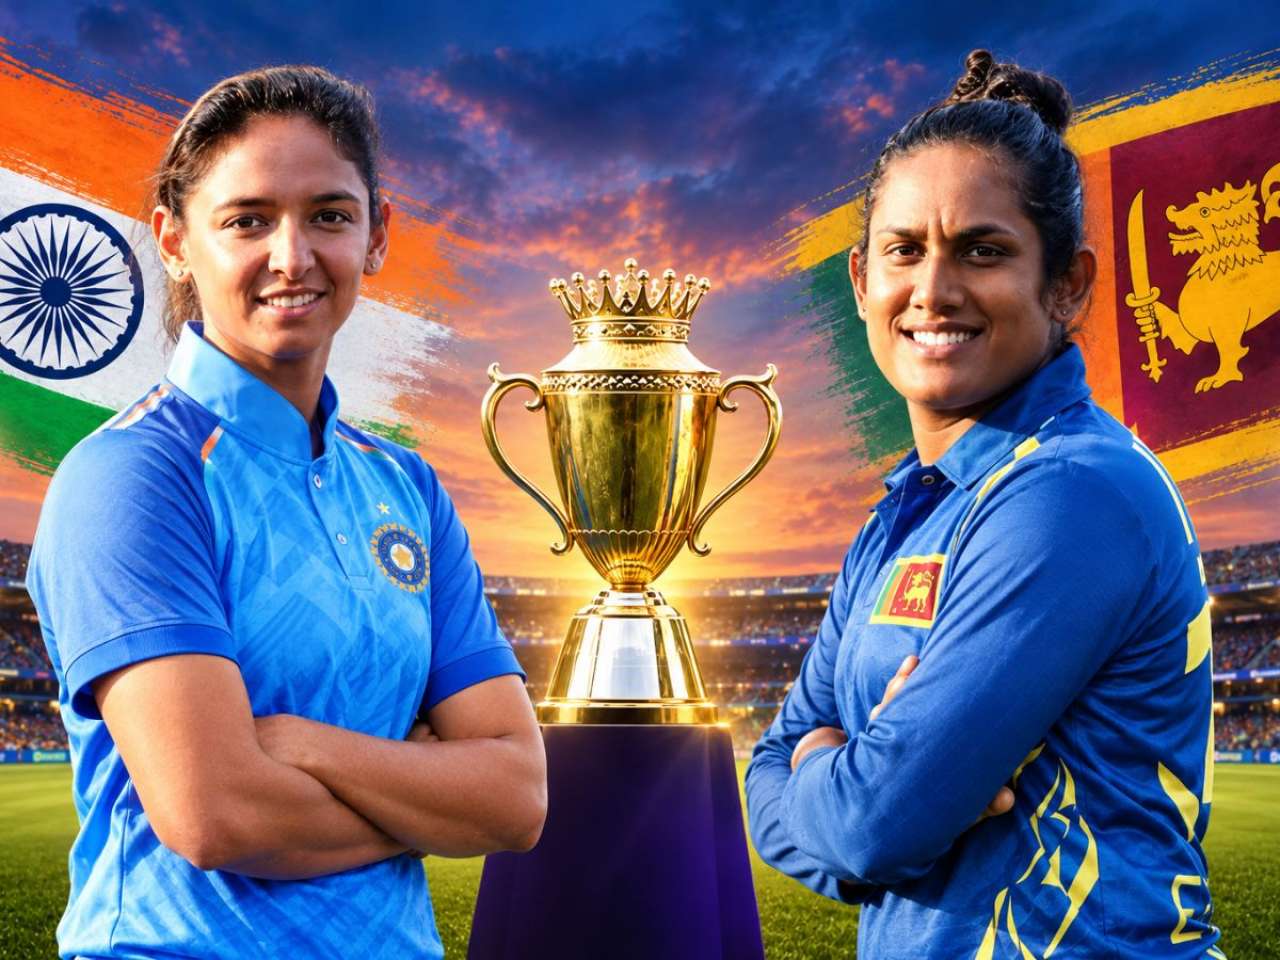 Revisiting Dambulla shock: What India must change in batting for Women's Asia Cup final vs Sri Lanka'Indian version of Coldplay kiss cam': Netizens react as Vijay, Trisha's awkward moment from Ajith Kumar's Silverstone race goes viralSIIMA 2026 winners list: Kantara Chapter 1 wins Best Film; Rishab Shetty, Naga Chaitanya bag top acting honours
 Aneet Padda reveals she auditioned for Hunkkaar at 17, shot OTT series when she was 20: 'Something terrible happened...'
 Hanuman Ansh box office collection day 38: Neem Karoli Baba film is unstoppable, crosses Rs 200 crore in India
 Exclusive: Shashwat Sachdev's debut live IP Future Machine sparks $50 million bidding war as London, Dubai venues vie for world premiere
 Houthi Attack Saudi Arabia: Houthis Snatch Key Red Sea Gateway Mocha; Big Shock For Saudi | US-Iran
 BRICS Summit 2026: India To Push BRICS Digital Currency Link Despite Political & Technical Hurdles
 BRICS 2026: Putin Lands In Delhi For BRICS Summit To Hold Bilateral With PM Modi Today
 iPhone 18 Price: Why Apple iPhone 18 Range Is So Much Costlier In India Than US?
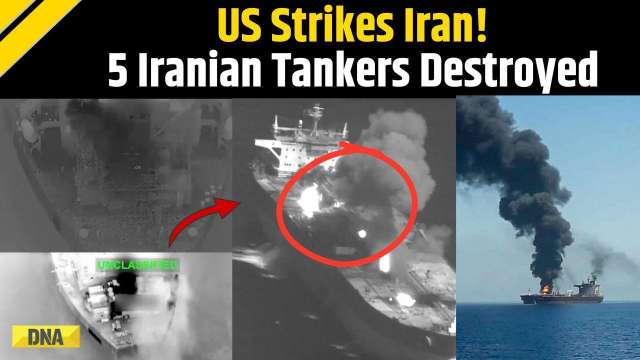 US Iran News: US Destroys 5 Iranian Oil Tankers, Iran Strikes US Base In Jordan
 Gold, silver prices today, September 13, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Bernard Arnault out of world's top 10 richest list for first time since 2017, net worth falls to USD 143 billion
 Gold, silver prices today, September 12, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 8th Pay Commission: Why do Chennai GPO pensioners demand restoration of Old Pension Scheme? Will government do it?
 Crude oil price jumps above USD 108, hits 4-month high amid West Asia crisis; Know how it will impact India
 MS Dhoni to Virat Kohli: Indian cricket stars turn back time in viral 80s AI photo trend
 Bigg Boss 20: From Mary Kom, Mahhi Vij to Isha Rekhi, Qazi Touqeer, Rhiti Tiwari, Gullu; final confirmed list of contestants
 From Suhana Khan to Rasha Thadani, Ananya Panday: Gen-Z actresses acing modern-day Radha look in Janmashtami
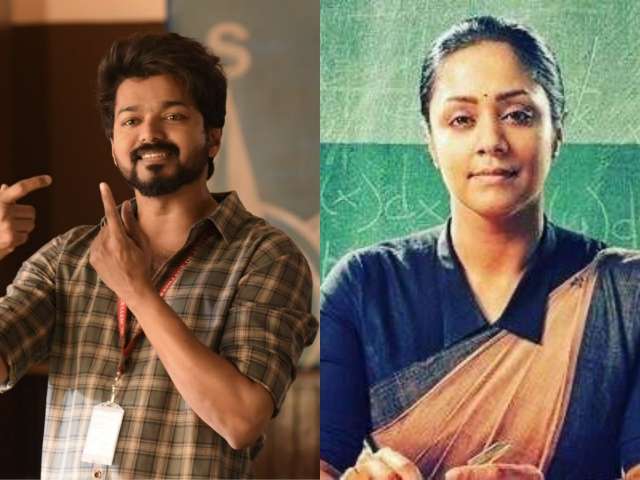 Teacher's Day 2026: From Thalapathy Vijay to Jyothika, 5 popular on-screen gurus from South that became household names
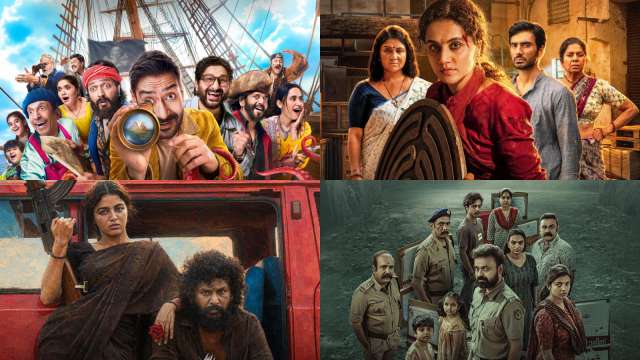 OTT Releases This Week: Dhamaal 4, Gandhari, DC, Bigg Boss 20; Indian movies, series to watch on Netflix, JioHotstar, ZEE5From Kerala to Tamil Nadu: Why four Opposition CMs skipped BRICS dinner despite invite
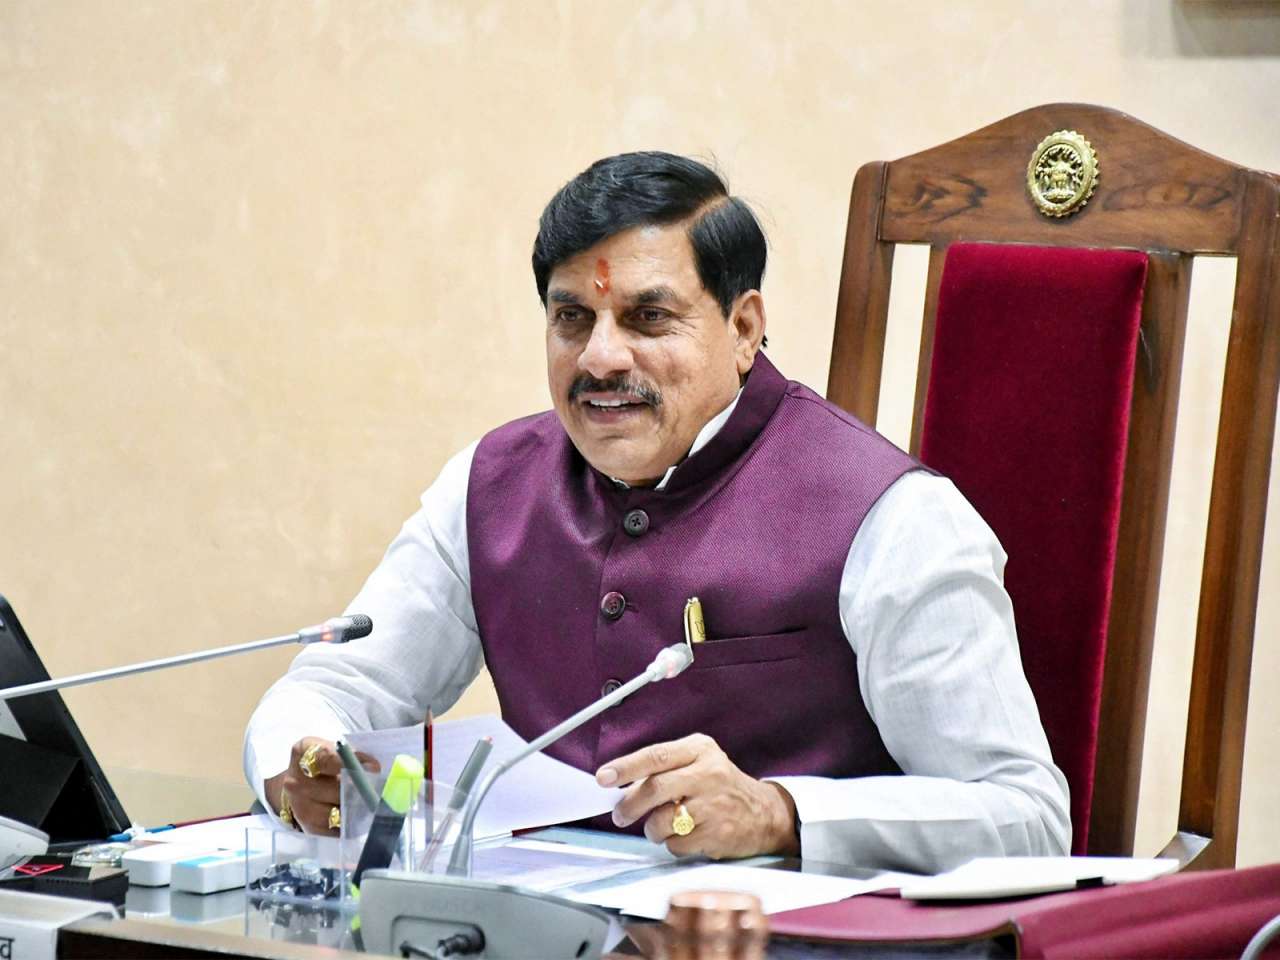 MP CM Mohan Yadav slams Rahul Gandhi over his 'Chhatron Ki Goonj' event in Indore
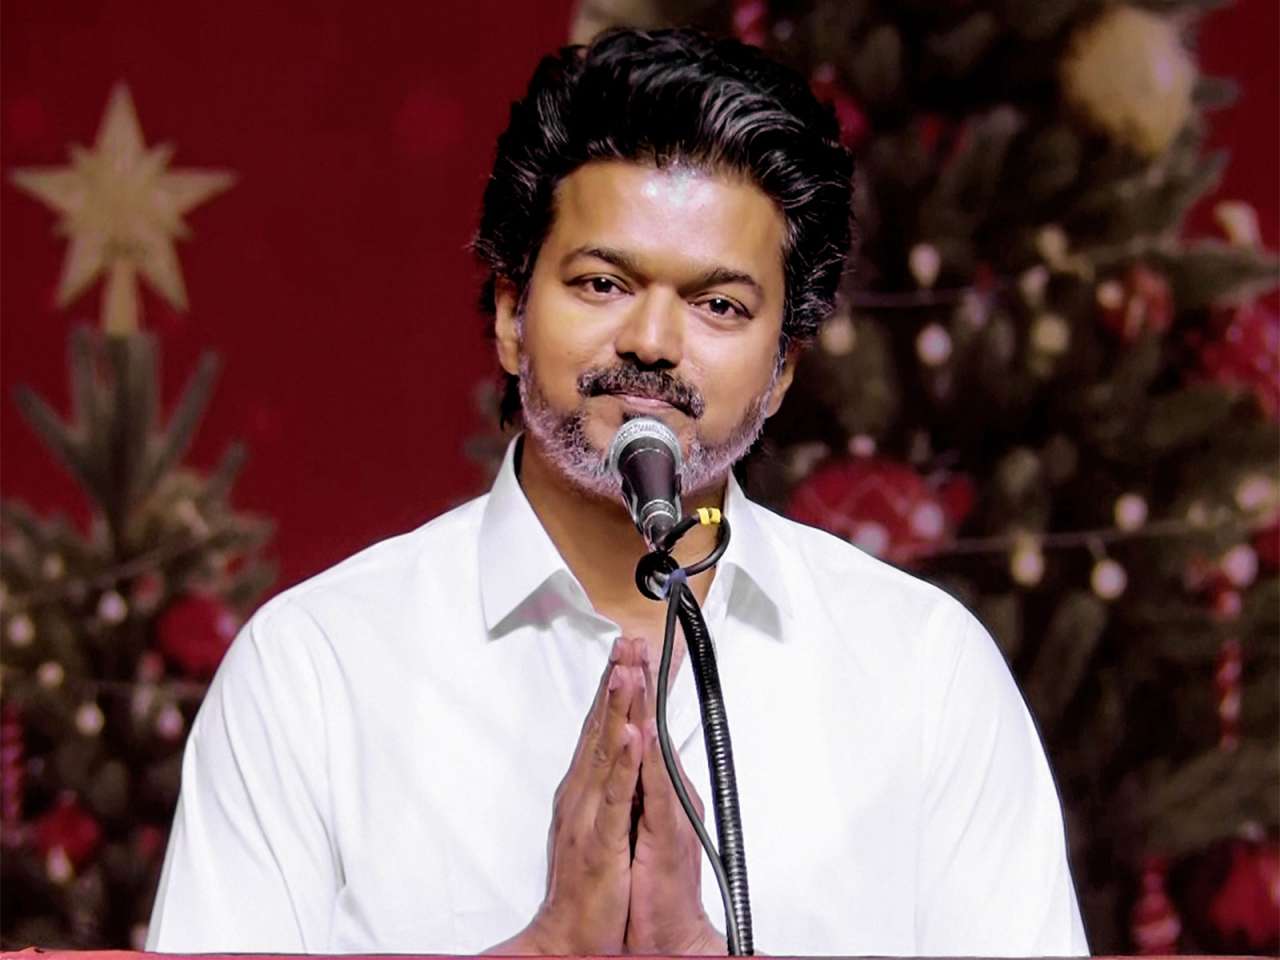 TVK files police complaint against DMK leaders over controversial remarks targeting CM Vijay
 MCD cracks down on illegal construction in Delhi, demolishes 11 properties
 Rahul Gandhi vs Kiren Rijiju: BRICS dinner menu sparks BJP-Congress clash
 UGC NET: NOIDA protest accused cracks exam, scores 99.3 percentile, says how made preparations in jail
 NEET PG Exam 2026: When will answer keys be released, how to access? Know here
 Teachers’ Day 2026: Heartfelt wishes, messages to make your favourite teacher feel special
 Who is Gyanendra Kumar Gangwar, IAS officer arrested in KPSC exam irregularities case?
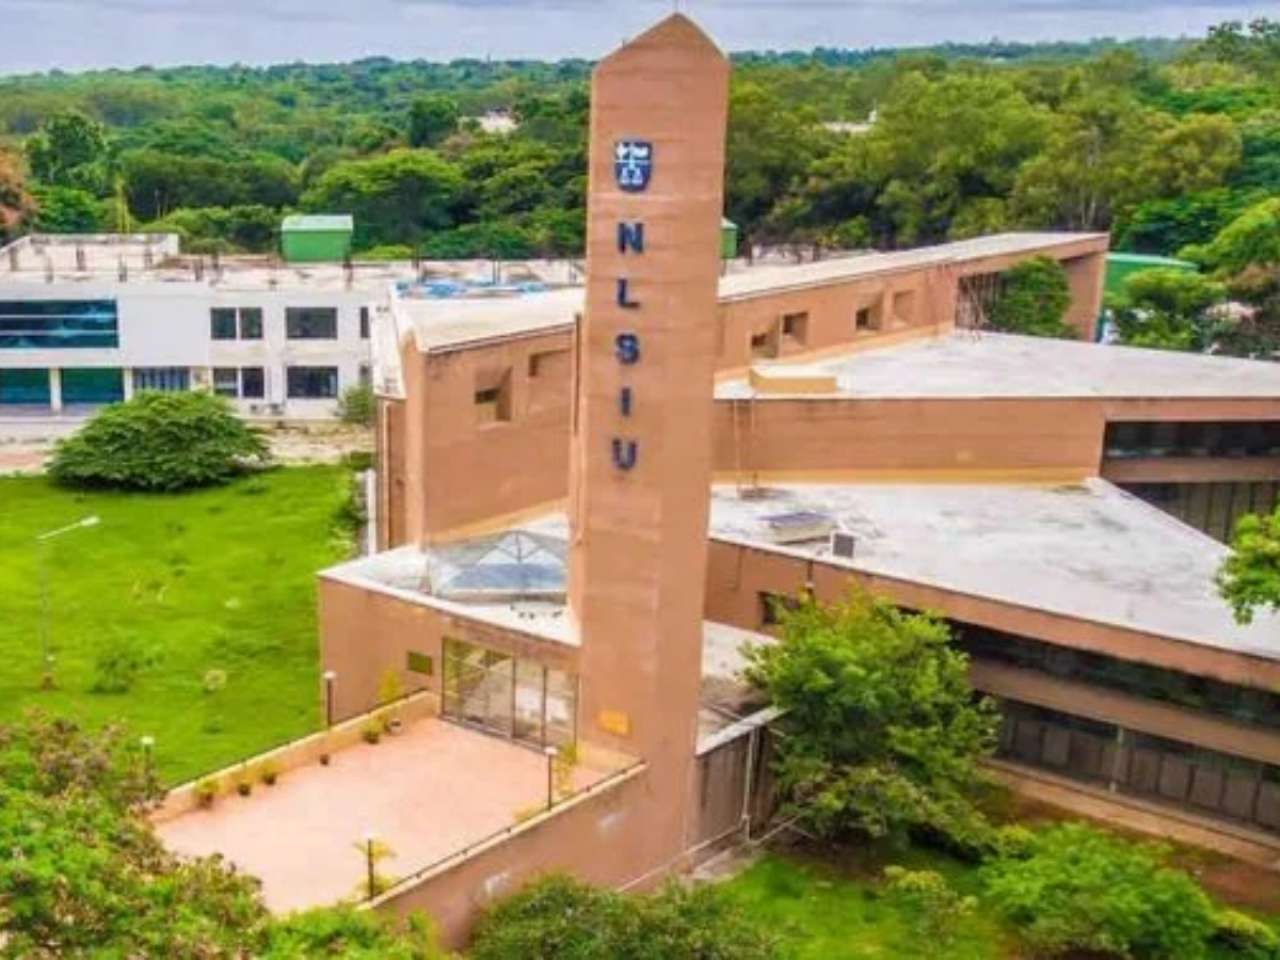 NLSIU cancels convocation amid row over CJI Surya Kant's proposed presence; CJP reacts
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
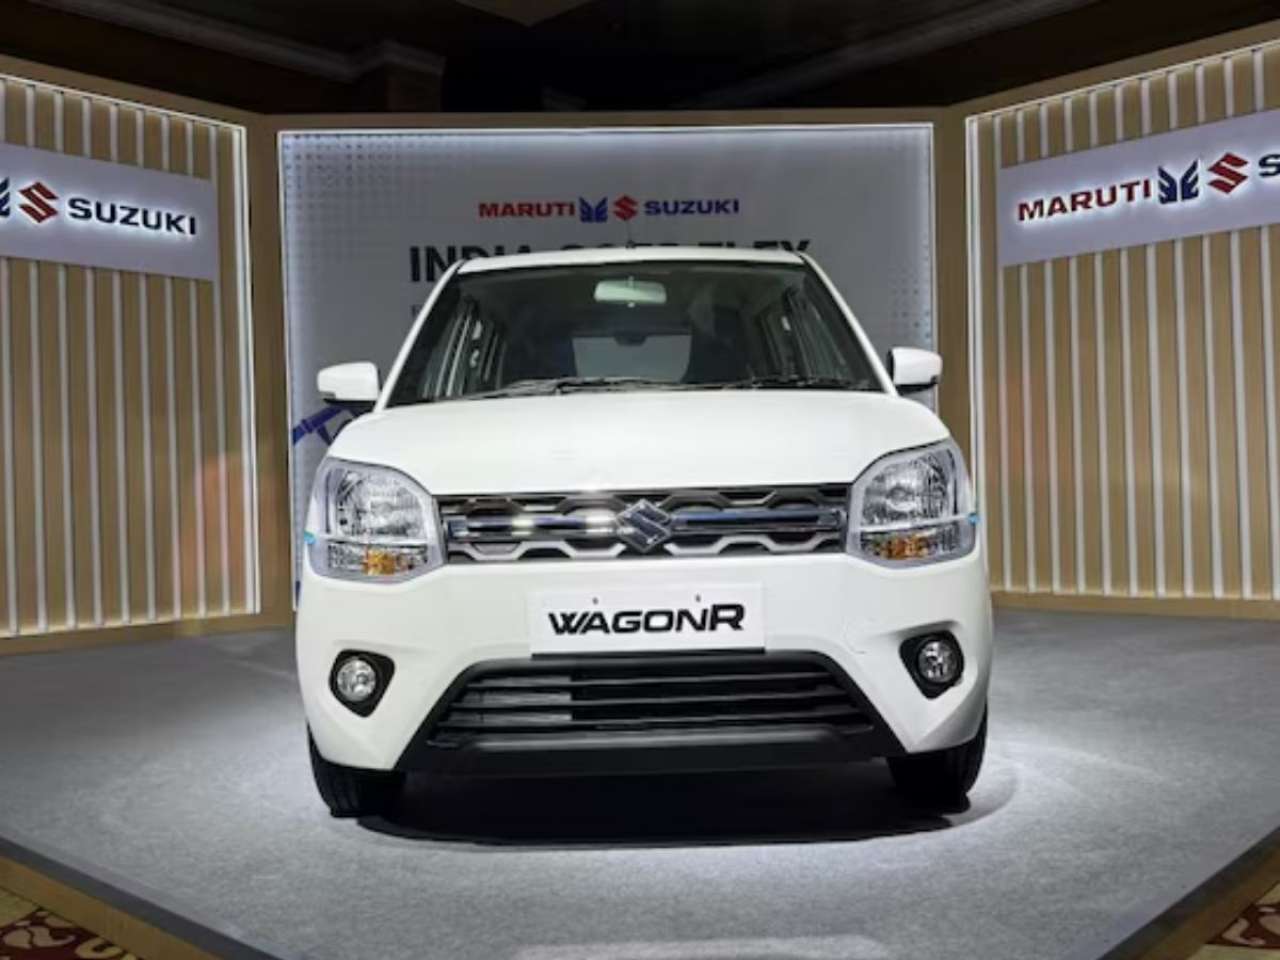 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
PERSONAL FINANCE
Both PPF and NPS are preferred by long term investors who are looking for a solid way to increase their wealth.

Updated : Aug 16, 2021, 05:23 PM IST | Edited by : Abhishek Sharma


When choosing a long-term investment, most people prefer Public Provident Fund (PPF) and National Pension System (NPS) over others. However, the objectives of both these investment options may be different. While NPS is purely a retirement scheme, PPF needs to be kept active even after maturity. Let us know about these two in detail so that you can make an informed choice.
Since NPS a retirement scheme, investment is made in this so that the pension continues after the age of 60 years. On the other hand, to get a pension through PPF, you have to keep it active even after maturity.
PPF is a 100% debt instrument, i.e. its entire money is invested in bonds etc., whereas NPS has a share of both debt and equity. In NPS, the investor has the option that to keep the equity share up to 75% in it. Experts say that if the investor has a high-risk appetite, then he/she can keep the debt-equity ratio 50:50, to get a return of up to 10 percent in the long term, which is about 3 percent from the 7.1% of PPF.
In NPS, after maturity, a minimum of 40 percent is mandatorily put in the annuity, which means pension. This money will be used to get a monthly pension after retirement.
By investing in both these schemes, you also get the benefit of tax exemption. Income tax exemption is available on investment of Rs 1.5 lakh annually. There is no fixed maturity limit in NPS, whereas PPF matures in 15 years, so those who want to continue investing in PPF for a long period have to carry forward the investment for a period of five years every time. That is, if someone wants to continue PPF for 30 or 35 years, then he can continue it in blocks of 5 years. Experts advise that investors should opt for PPF extension as they get the benefit of compounding interest.
Let us now see which option between PPF and NPS gives you more benefit or amount on retirement. Suppose you are 30 years old, you want to invest for the next 30 years so that when you are 60 years old, you have a huge amount in your hand.
Rs 3,000 per month investment in PPF
So, if you put Rs 3,000 monthly in PPF, that is, Rs 36,000 for one year and if you continue this investment for 30 years, then at the current 7.1% interest rate, you will get Rs 37,08,219 after 30 years.
Rs 3,000 per month investment in NPS
If you put 40 percent of this maturity value in the annuity, that is, Rs 17.81 lakhs, your lump sum amount will be Rs 26.71 lakh and your monthly pension will be Rs 11,874. Here, we have taken an 8% expected return on the annuity.