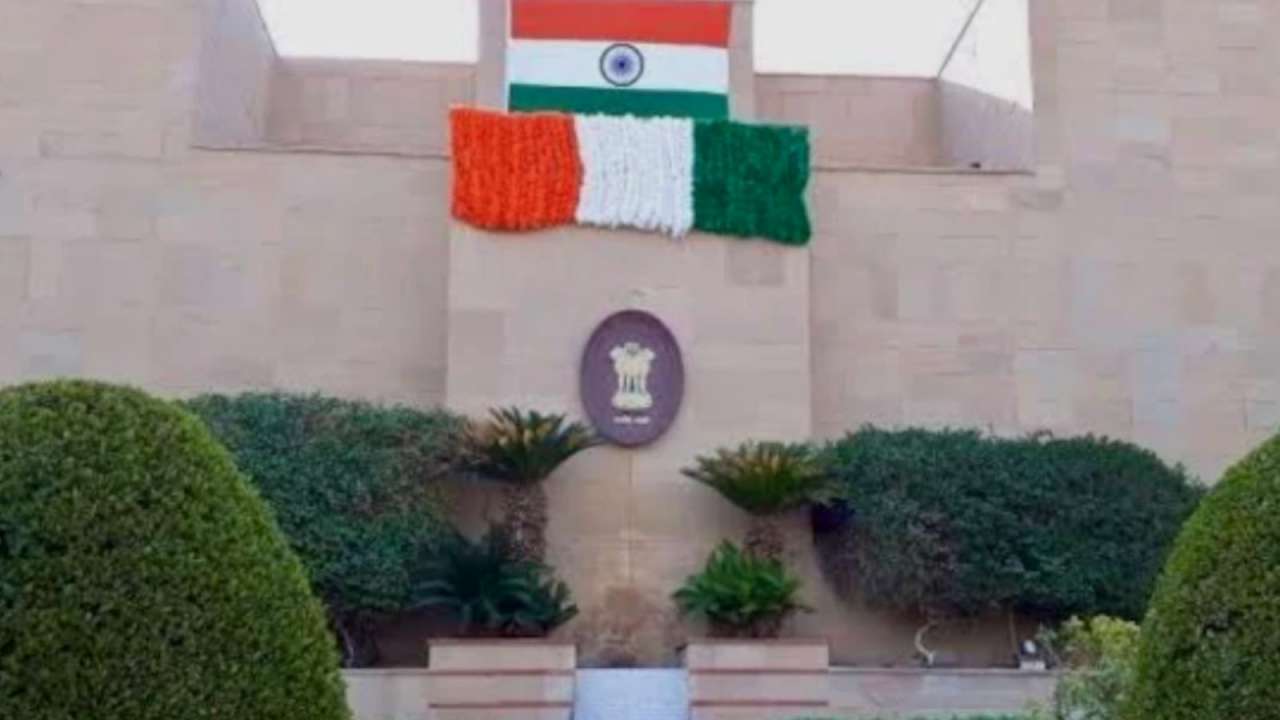
 Saudi Arabia Attacks: Indian Embassy issues advisory, urges citizens to stay alert
 Viral video: Yash defends Ranbir Kapoor against trolls for playing Lord Rama in Ramayana, calls him 'most honest' actor: 'God has given us the opportunity'
 SEBI Revises Closing Auction Session Rules: What changes from December 7?
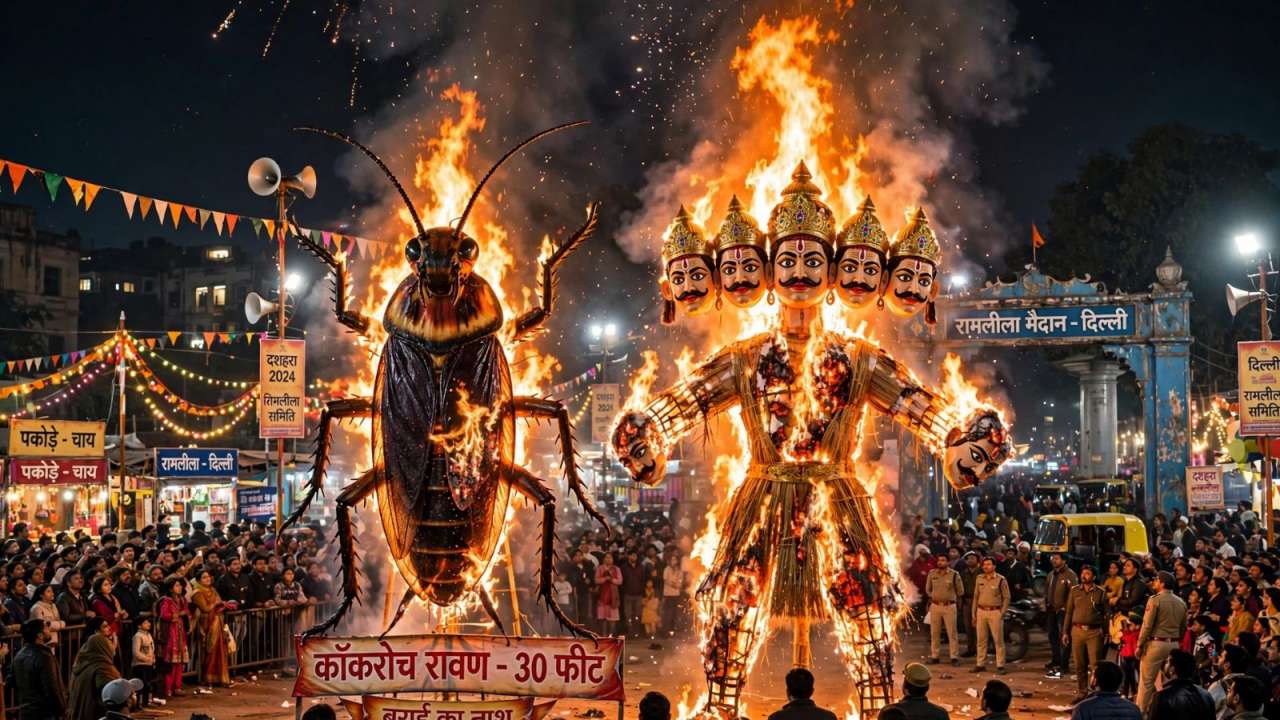 Delhi Ramleela to burn 30-foot Cockroach effigy alongside Ravan
 Ramayana: Ranbir Kapoor makes big statement, admits 'I don't deserve' to play Lord Rama, confesses what convinced him for film
 WATCH: PM Narendra Modi’s '15-year-olds' remark prompts priceless reaction from Vaibhav Sooryavanshi
 Sanju Samson sounds alarm on India's bowling crisis, makes huge admission on Jasprit Bumrah
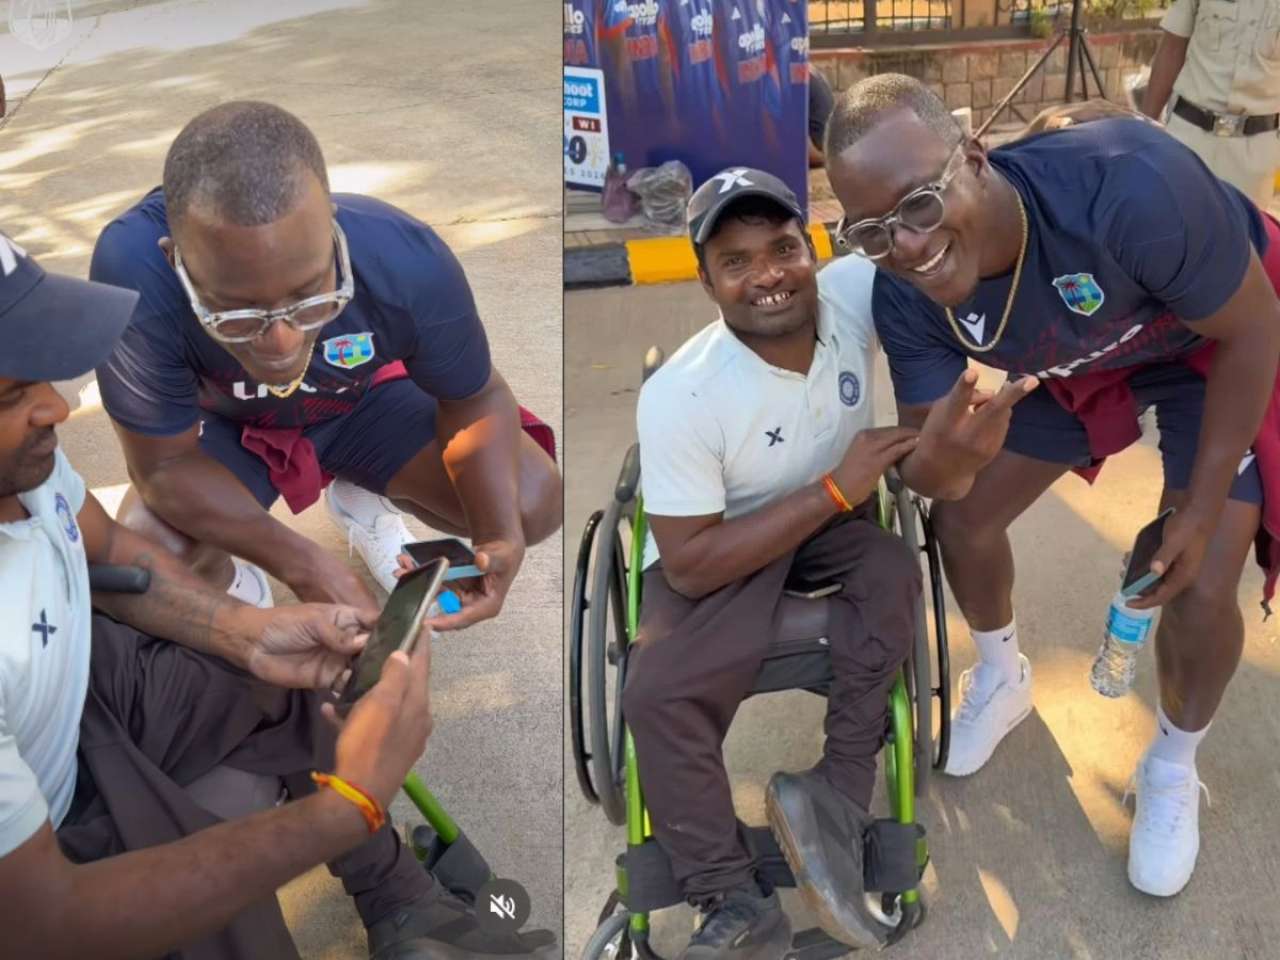 Watch: West Indies coach Darren Sammy wins hearts with gesture towards differently-abled fan
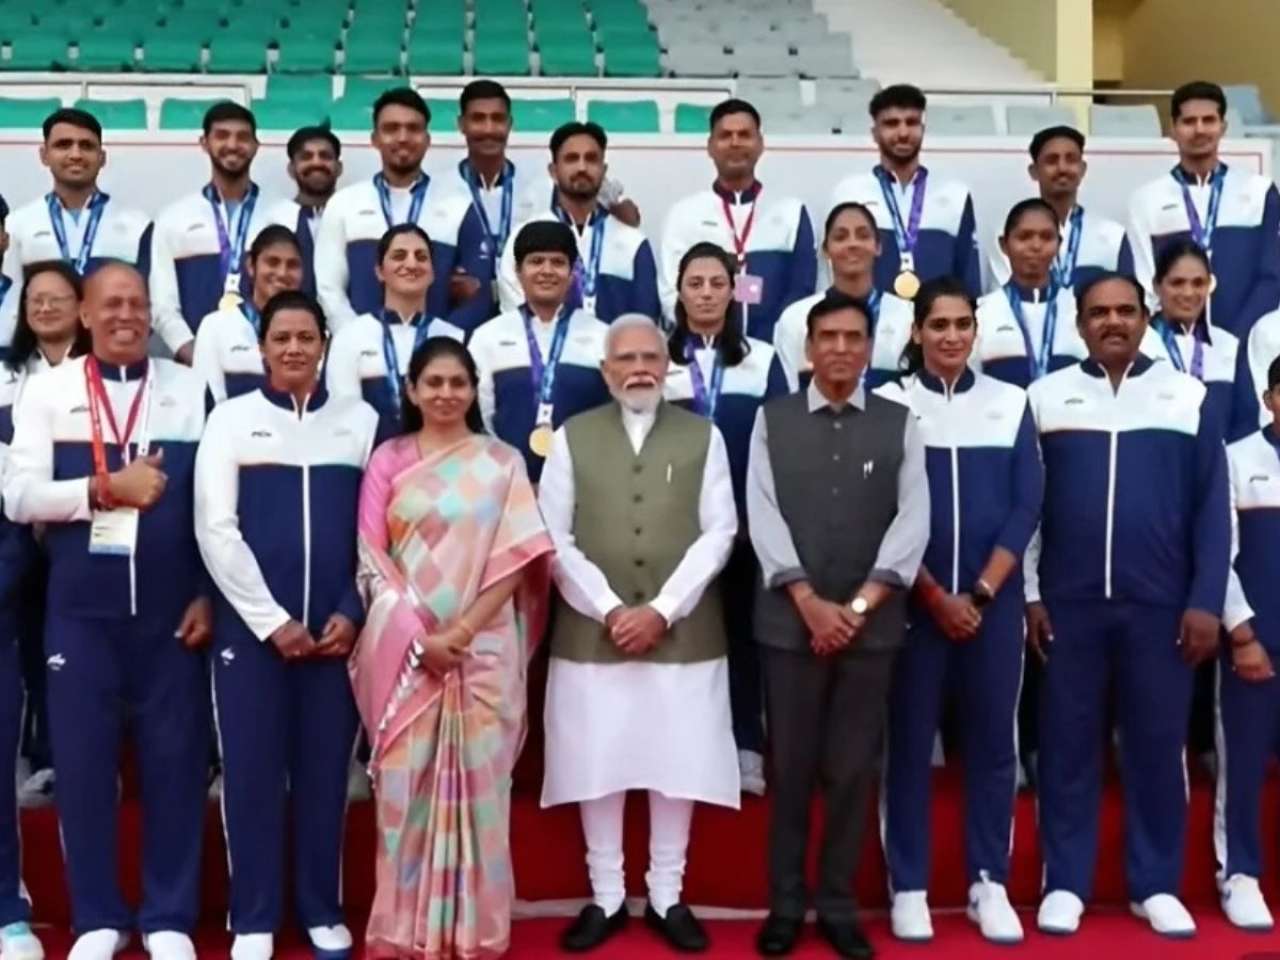 PM Narendra Modi meets India’s Asian Games 2026 stars after 85-medal haul, congratulates champions
 Were Sachin Tendulkar, Gautam Gambhir, Yuvraj Singh pushed out of Team India? Former selector drops massive bombshellViral video: Yash defends Ranbir Kapoor against trolls for playing Lord Rama in Ramayana, calls him 'most honest' actor: 'God has given us the opportunity'Ramayana: Ranbir Kapoor makes big statement, admits 'I don't deserve' to play Lord Rama, confesses what convinced him for film
 Ramayana: New trailer gives extended glimpses of Jatadhari Yash becoming ruthless Raavana, Ranbir's Ram battling mega monsters on rannbhoomi, fans react
 Prahaar Movie Review: Rajkummar Rao Streaks Into A Gripping Story Of Justice Beyond 26/11
 Imran Khan offered Rs 15 lakh to post against Modi govt? Know truth behind claim
 CJP Protest: Mumbai Police Issues Notice To Actor Imran Khan To Leave India By October 28
 CJP Protest: Rahul Gandhi Accuses Delhi Police Of Beating Youngsters At Protest | Jantar Mantar
 CJP Protest: Congress Rahul Gandhi Backs CJP Leaders Jailed For Tresspassing At Jantar Mantar
 Delhi Protest: Delhi High Court Bench To Hear Pleas On Protest Regulation & Jantar Mantar Ban
 Pakistan News: 5 Killed, 30 Injured As Rehman Baba Express Derails Near Multan In PakistanSEBI Revises Closing Auction Session Rules: What changes from December 7?
 Jio IPO: How Rs 30,213-crore issue could impact Mukesh Ambani's Reliance Jio, India’s digital ecosystem
 India-New Zealand FTA from Oct 20, Canada trade deal by year-end; What it means for exporters
 Gold, Silver prices today, October 15, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 IDBI Bank Sold For Rs 52,878 Crore: From Air India to IDBI Bank- Modi govt's big disinvestment moves explained
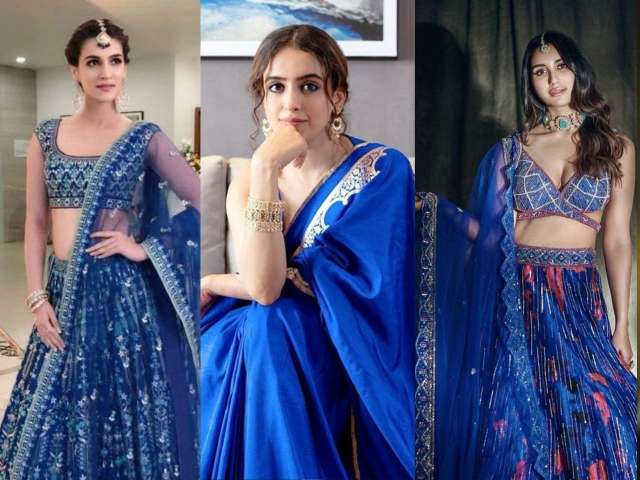 Navratri Day 4: From Shraddha Kapoor, Kriti Sanon, Sanya Malhotra, actresses who embody goddess in blue outfits
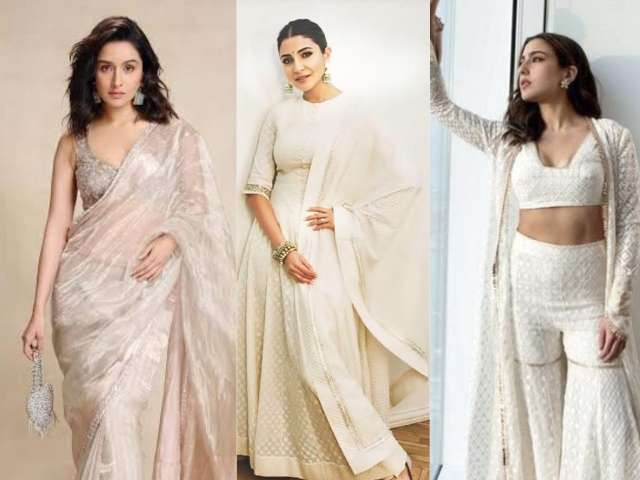 Navratri 2026: From Alia Bhatt to Sara Ali Khan, Shraddha Kapoor, take inspiration from Bollywood actresses to stun everyone in white
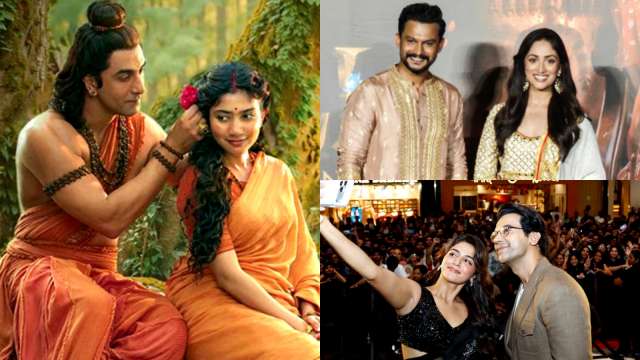 Ranbir Kapoor-Sai Pallavi, Yami Gautam-Addinath Kothare, Rajkummar Rao-Wamiqa Gabbi: 5 fresh on-screen jodis to watch out for in 2026
 OTT Releases This Week (October 5-11): Awarapan 2, Khalifa, Mandaadi; new India movies, shows to watch on Netflix, Prime Video
 OTT Releases This Week (Sept 28 - Oct 4): Dupahiya 2, Pooja Meri Jaan; new movies and shows to watch this Gandhi Jayanti weekendDelhi Ramleela to burn 30-foot Cockroach effigy alongside Ravan
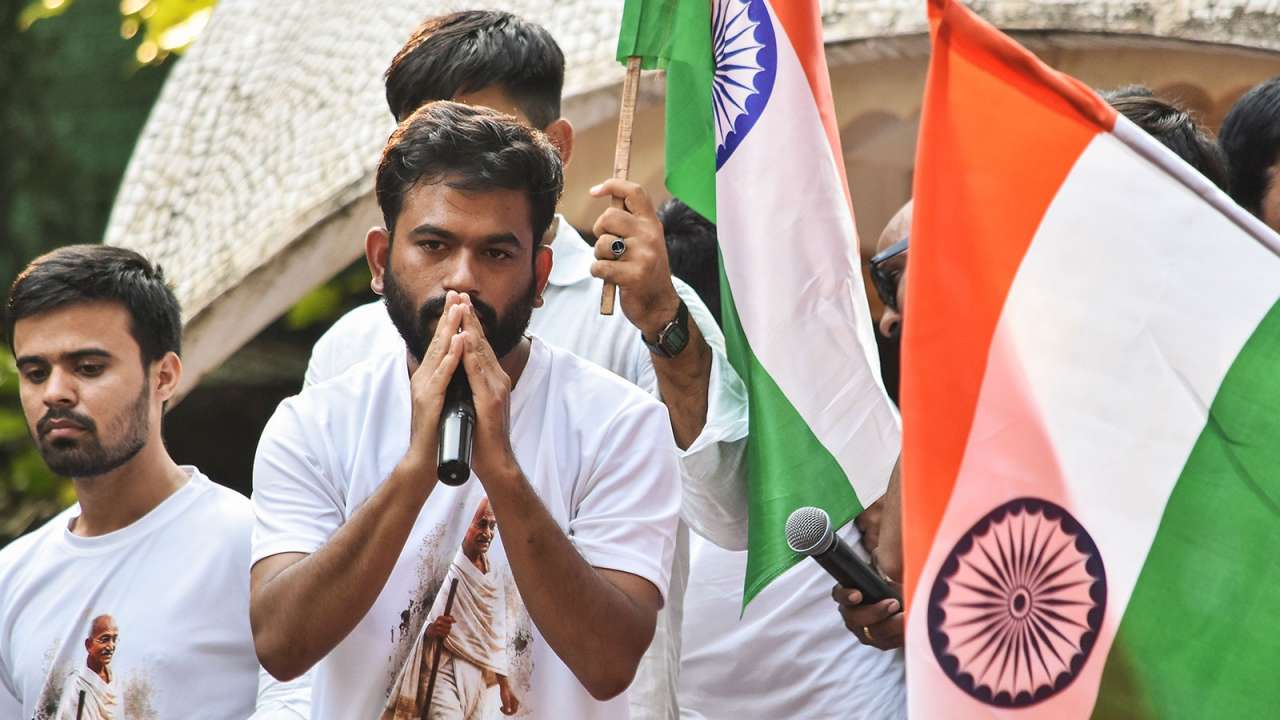 Connaught Place central park closed Oct 16-17 ahead of CJP's Tiranga rally, Delhi Police urges citizens to stay away
 Special Summary Revision of electoral rolls in 17 states, ECI takes big step after SIR
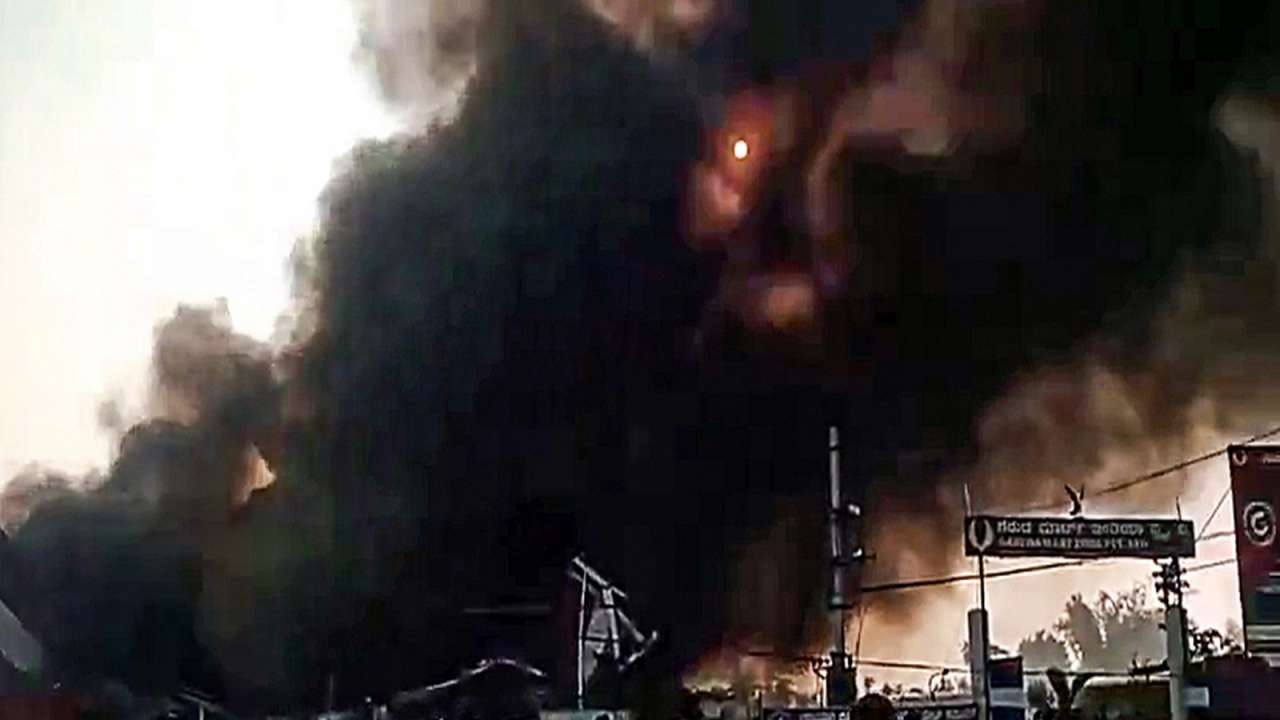 Fire breaks out after boiler blast at Chhatral GIDC, four dead in Gujarat factory
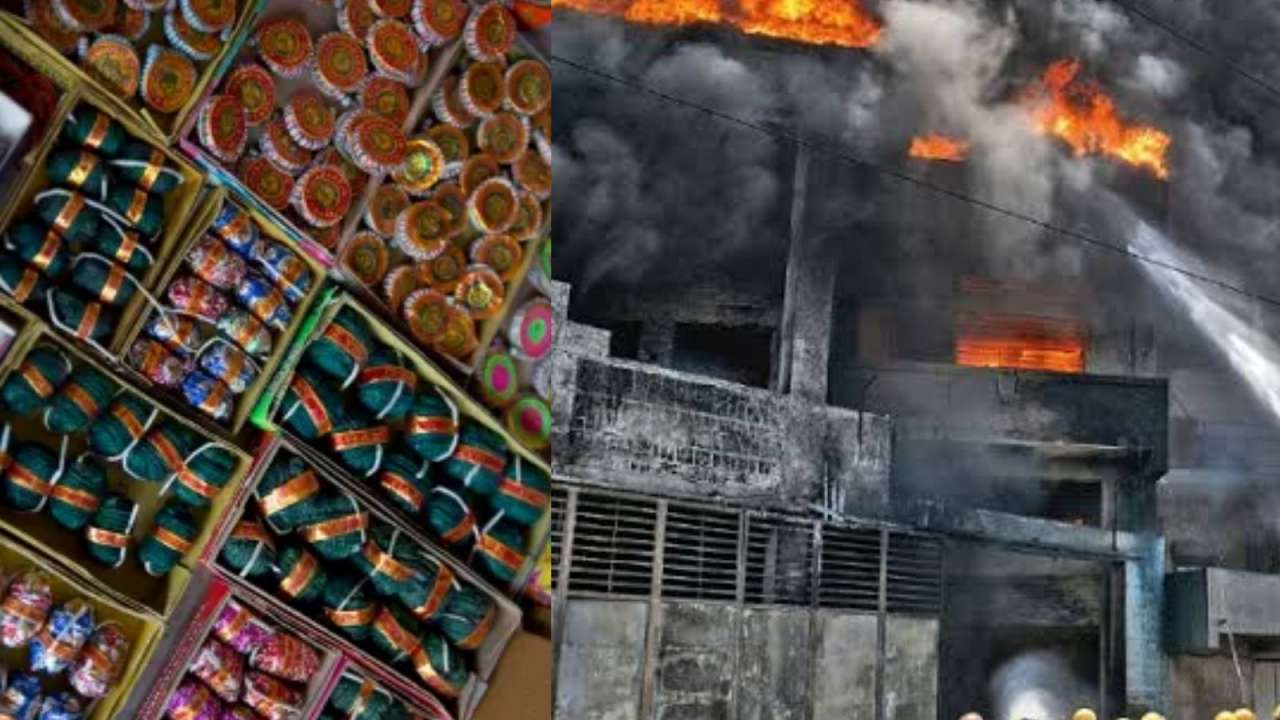 Explosion at fire cracker factory in Varanasi, many feared trapped under debris
 AI-generated question papers for NEET? Nandan Nilekani proposes novel idea for stopping paper leak
 Third Language Row: SC extends relaxation to Class 6 students, asks CBSE to grant exemption, here's what it means
 NEET PG 2026 Result Out: Check how to download scorecard from natboard.edu.in; Know category-wise cut-off and more
 Five-year BTech programmes? Ex-IIT director makes proposals amid IIT suicide controversy
 CBSE Date Sheet 2027: When will Class 10, 12 timetable be released? Check details here
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
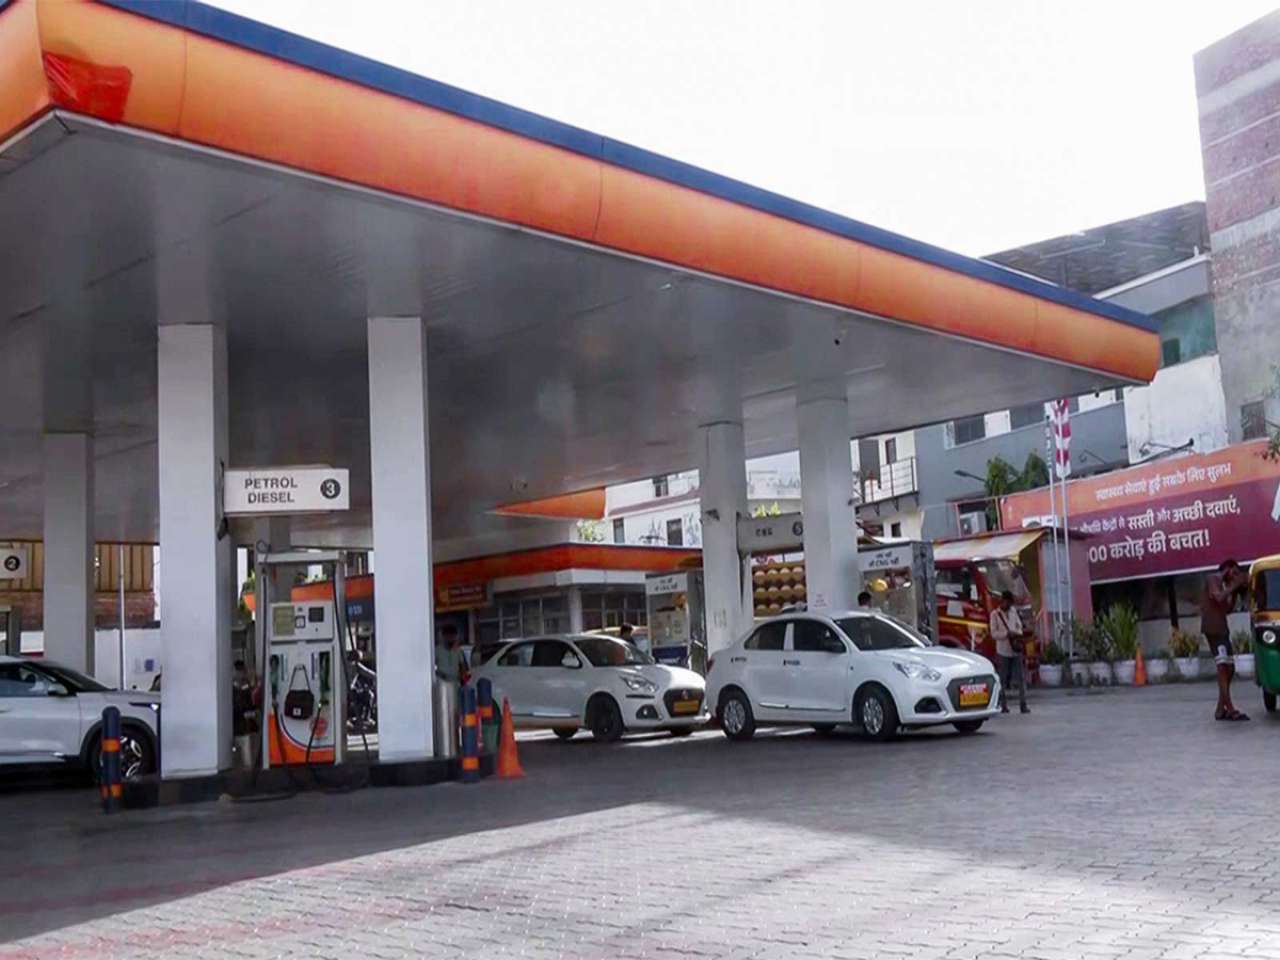 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
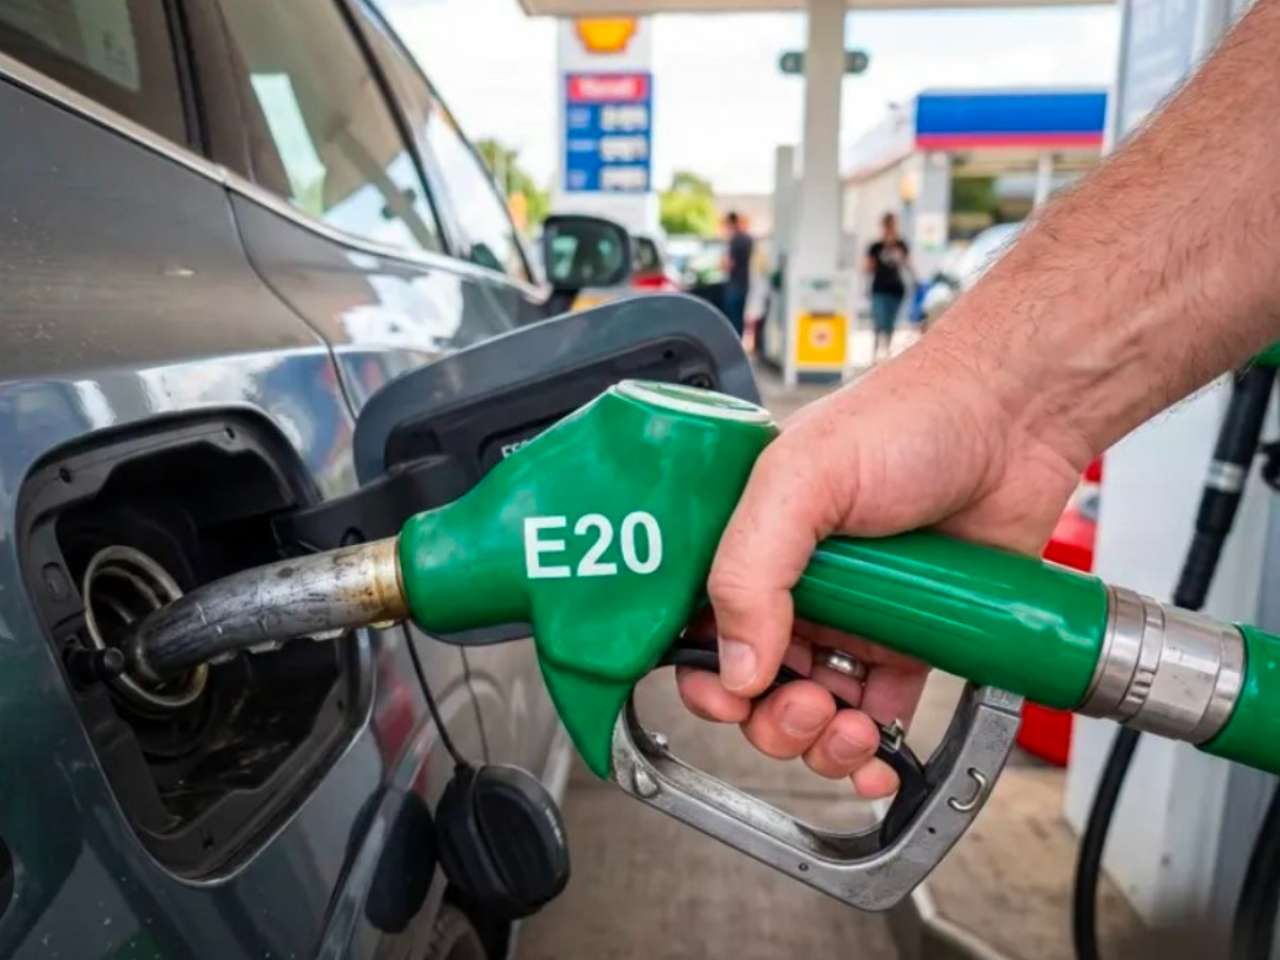 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
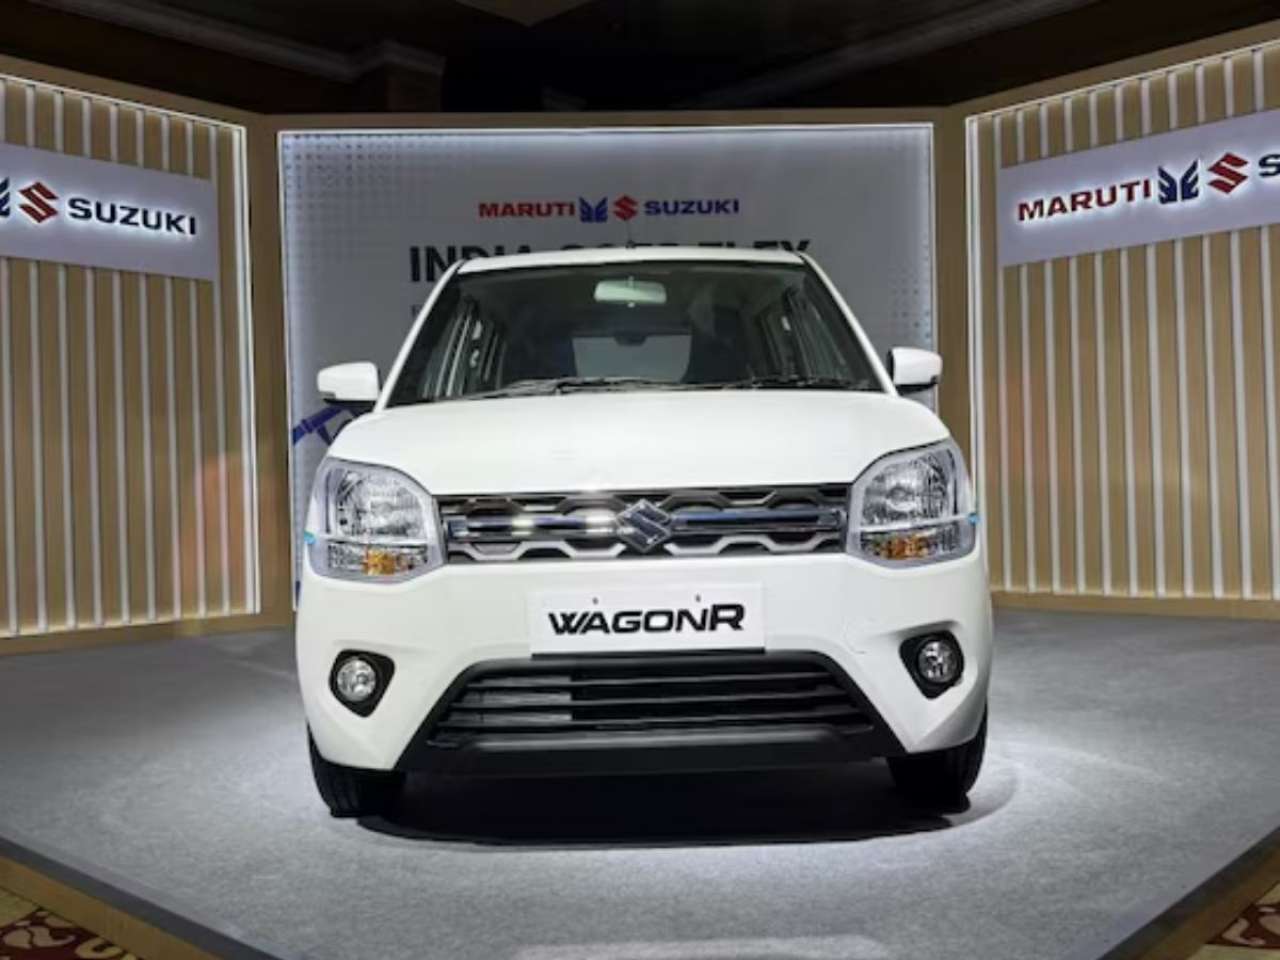 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
PERSONAL FINANCE
Tax savings would make the loan much cheaper than the return his daughter would get on the debt MF units

Updated : May 19, 2017, 07:25 AM IST

You may remember Hemant who I had written about in my article of May 04,2017 published in DNA Money. Hemant had about Rs 50 lakh (cost Rs 35 lakh) in a debt mutual fund (MF) which was earmarked to pay for his daughter’s education in USA. The investment was made four years ago, therefore would be eligible for concessional rate of long-term capital gains tax, and after indexation benefit, the tax payable was coming to only Rs 50,000. I had advised him not to redeem the units himself but to gift the mutual fund units to his daughter, so that she could redeem the mutual fund units without having to pay any long-term capital gains (LTCG) tax, since she had no other taxable income. Hemant had agreed to implement it.
However, he called me back to check on two things. Firstly, the mutual fund house said transferring MF units to another person (except on death) won’t be possible, and his only option was to redeem the units. I asked him to first dematerialise the units into his demat account after which, he could use the normal Transfer Instruction for Delivery slip to transfer the units to his daughter’s demat account accompanied by a letter announcing the gift which his daughter should accept. That would transfer the units into his daughter’s name. She could then proceed to redeem in the normal course. This way all the tax advantages would be retained in a perfectly legitimate way.
His second clarification was even more interesting. He mentioned that his tax advisor had asked him to take an education loan instead of using the invested money. The argument was that because of the deduction available on the interest paid on the education loan, the tax savings would make the loan much cheaper than the return his daughter would get on the debt MF units. This was the calculation he shared with me. His taxable income this year was likely to be around Rs 54 lakh, which means he would be paying income tax of around Rs 16,23,000. If he took an education loan of Rs 50 lakh from a PSU bank (by giving the security of his house), it was available to him at around 10.50% p.a. which means the interest for the first year would be Rs 5,25,000. The interest was fully deductible and his taxable income would drop to Rs 48.75 lakh (from Rs 54 lakh), on which the tax payable was approx. Rs 13,13,000 leading to a tax saving of Rs 3,10,000 approx. (Rs 16,23,000 less Rs 13,13,000). The actual interest paid on the loan thus came down from Rs 5,25,000 to Rs 2,15,000 because of the tax saving of Rs 3,10,000. Interest of Rs 2,15,000 on a loan of Rs 50,00,000 was an effective cost of only 4.30% p.a. The tax saving impact was so high simply because the tax deduction bought his income below the threshold of Rs 50 lakh after which he had to pay an income tax surcharge. His daughter could easily pay him back this amount by redeeming the mutual fund units which would be earning her around 7% p.a.
I checked out the figures and agreed that it made a lot of sense. I could not resist giving him another piece of advice though. Instead of taking an ‘education loan” from a PSU bank at 10.50% as proposed by him, I told him to take a loan against the security of the same property from a private bank which would be available much cheaper at around 9% only (around 1.50% cheaper). Hemant loved the idea but had a doubt. Would he still be eligible for the deduction of the interest paid on this “loan against property” despite it not being styled as an “education loan”?
I assured him that if he could prove that the money from the “loan against property” was used for the purpose of the higher education expenses of his daughter, he would definitely be eligible for the deduction of interest paid on the loan. Hemant was reassured and agreed to take a loan instead of just redeeming the mutual fund units and also to take the cheaper “loan against property” rather than the more expensive “education loan”.