BRICS Summit 2026: Delhi gears up for world leaders as Russia’s Sergey Lavrov arrives, Putin set to land soon
 US H-1B Visa: What ending 60-day grace period could mean for Indian workers
 Hitman begins preparations for West Indies ODIs: Is Rohit Sharma sending 2027 World Cup message?
 BRICS Summit 2026: Delhi airspace restrictions, train diversions from Sept 11-13; all you need to know
 ‘Disrespected’ Australian legend reveals what PCB still owes him after Pakistan coaching stintHitman begins preparations for West Indies ODIs: Is Rohit Sharma sending 2027 World Cup message?‘Disrespected’ Australian legend reveals what PCB still owes him after Pakistan coaching stint
 Will India-Afghanistan 1st T20I move from September 13? Here’s the latest update
 Pakistan U-19 team mistaken for asylum seekers: What actually happened outside their hotel?
 IND vs BAN Women’s Asia Cup Semi-Final: Can Bangladesh finally break India’s 8-game streak?
 Akanksha Chamola to seek alimony from Gaurav Khanna amid divorce? Orry drops major hint
 Double win for Shweta Tripathi: Amid Mirzapur The Movie's success, actress will screen her queer love story, Mujhe Jaan Na Kaho Meri Jaan at...
 Bigg Boss 20: Kushal Tanwar called out by ScoutOp's team over 'betrayed by a friend' narrative after captaincy task
 Shrimad Bhagavatam Part I Vishnurata: Amid Hanuman Ansh's blockbuster run, Ramanand Sagar's grandsons announce 7-part film universe, will release from...
 Bipasha Basu seeks Tukaram Mundhe's help, tags FDA's chief after claiming she found worms in THIS product: 'You're our only hope'
 iPhone 18 Price: Why Apple iPhone 18 Range Is So Much Costlier In India Than US?
 US Iran News: US Destroys 5 Iranian Oil Tankers, Iran Strikes US Base In Jordan
 Karnataka News: Amazon, Swiggy, Instamart Stores Raided In B'luru; Expired, Mislabelled Items Seized
 Israel News: Netanyahu Was Warned About Hamas Attack Before October 7, Didn't Act Because Of...
 Delhi PG Collapse: Supreme Court Steps In After Satya Niketan PG Tragedy Kills 7, Announces Big Move
 Zee Business Bond Tokenization Summit 2026 Mumbai: Finance leaders discuss RWA tokenization future of digital bonds
 Gold, silver prices today, September 10, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 8th Pay Commission: How much pension can central govt employees get under proposed pension structure?
 Gold, silver prices today, September 9, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 NSE IPO to open on September 18, list on September 25? Key details you need to know
 MS Dhoni to Virat Kohli: Indian cricket stars turn back time in viral 80s AI photo trend
 Bigg Boss 20: From Mary Kom, Mahhi Vij to Isha Rekhi, Qazi Touqeer, Rhiti Tiwari, Gullu; final confirmed list of contestants
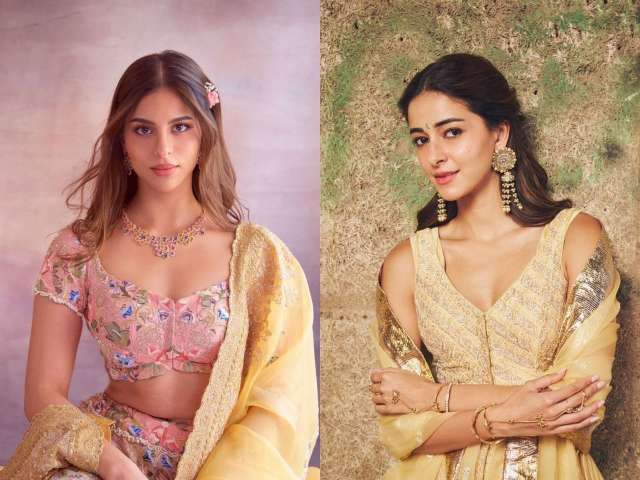 From Suhana Khan to Rasha Thadani, Ananya Panday: Gen-Z actresses acing modern-day Radha look in Janmashtami
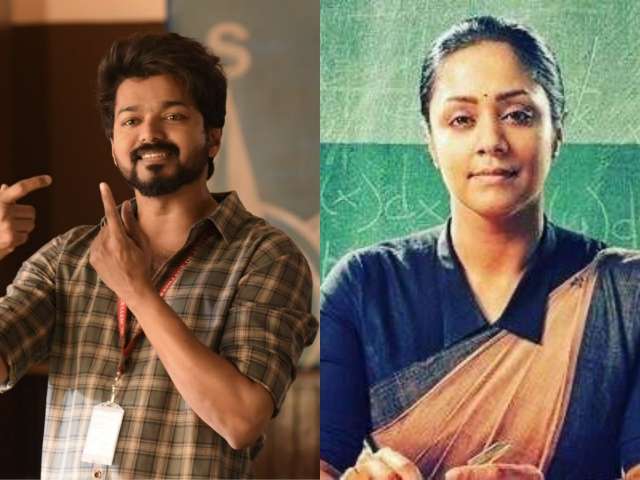 Teacher's Day 2026: From Thalapathy Vijay to Jyothika, 5 popular on-screen gurus from South that became household names
 OTT Releases This Week: Dhamaal 4, Gandhari, DC, Bigg Boss 20; Indian movies, series to watch on Netflix, JioHotstar, ZEE5BRICS Summit 2026: Delhi gears up for world leaders as Russia’s Sergey Lavrov arrives, Putin set to land soonUS H-1B Visa: What ending 60-day grace period could mean for Indian workers BRICS Summit 2026: Delhi airspace restrictions, train diversions from Sept 11-13; all you need to know
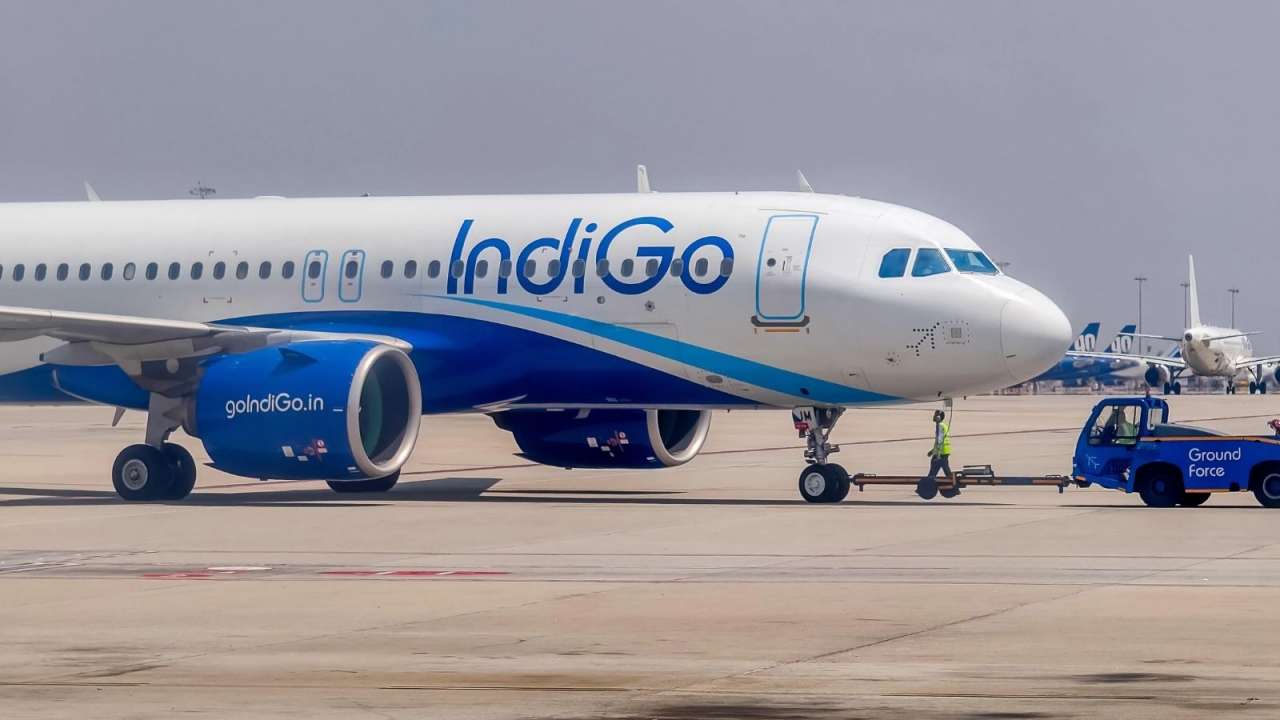 IndiGo Flight Emergency Landing in Ahmedabad: ‘Bomb’ note found, passengers’ handwriting samples collected; details inside
 BRICS Summit 2026: India showcases Sattu, Makhana, Koraput Coffee, Gujarat handicrafts
 NEET PG Exam 2026: When will answer keys be released, how to access? Know here
 Teachers’ Day 2026: Heartfelt wishes, messages to make your favourite teacher feel special
 Who is Gyanendra Kumar Gangwar, IAS officer arrested in KPSC exam irregularities case?
 NLSIU cancels convocation amid row over CJI Surya Kant's proposed presence; CJP reacts
 GATE 2027 Registration: Application form to be available from August 27, check direct link, documents required and more
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
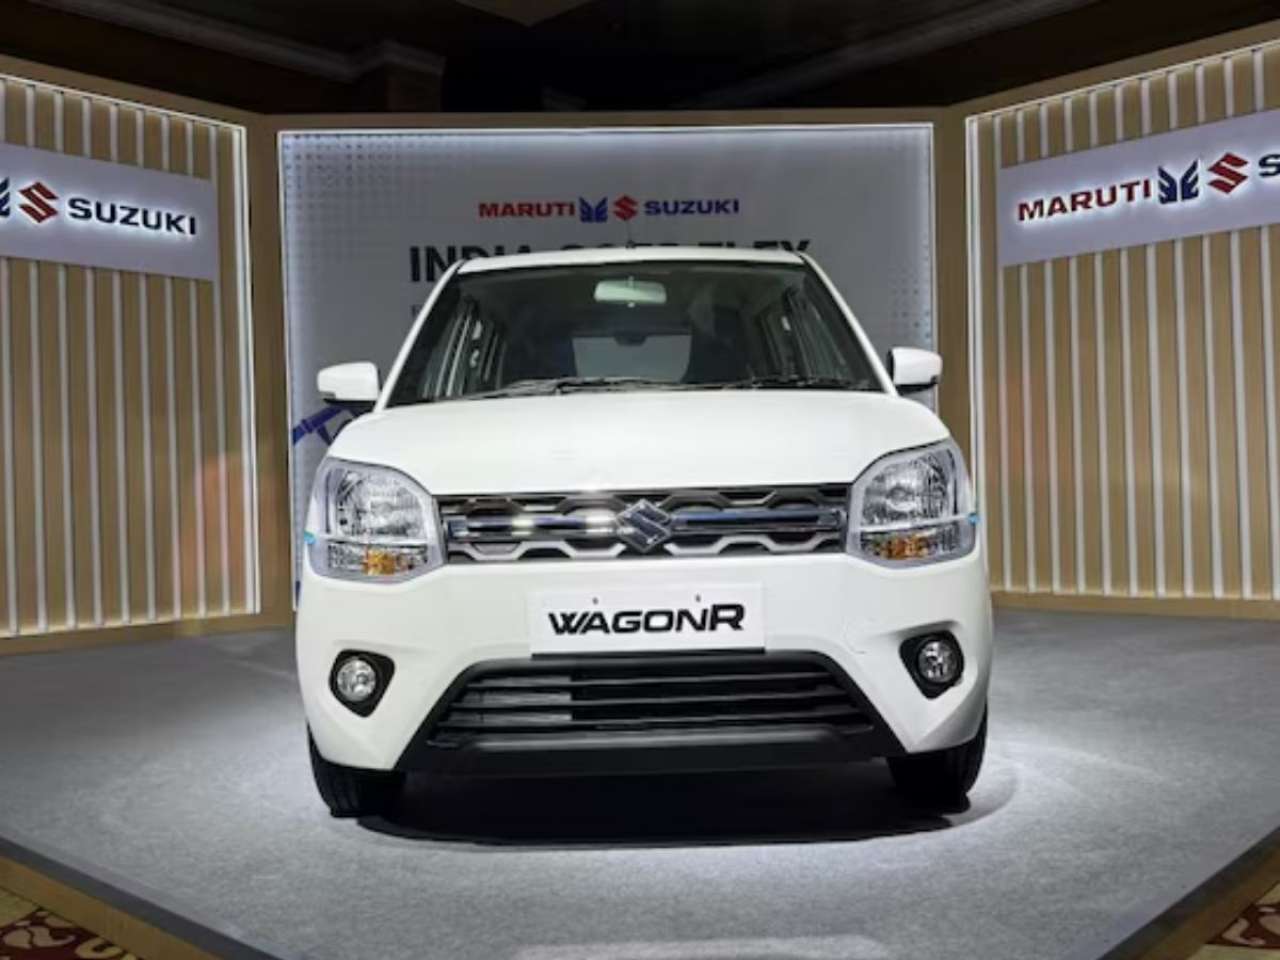 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
PERSONAL FINANCE
DNA Web Team | Dec 06, 2018, 06:29 PM IST
1.No more MCLR benchmark

Currently, banks follow system of internal benchmarks, including Prime Lending Rate (PLR), Benchmark Prime Lending Rate (BPLR), Base rate and Marginal Cost of Funds based Lending Rate (MCLR). MCLR is the floor rate below which banks are not allowed to lend. So based on the cost of funds, banks have a number of MCLRs for one month, one year, and so on. The RBI has decided to remove MCLR rates from April, 2019 and has asked banks to link floating interest rates on personal, home, auto and MSEs to external benchmarks like repo rate or treasury yields.
2.Good news for retail borrowers

The RBI had shown its disappointment on various occasions at the way banks had been deciding MCLR rate. RBI had stated several times that banks were not passing the benefits of reductions in RBI policy repo rate to borrowers.
3.Proposal suggested by internal study group set up by RBI

The proposal to shift to external benchmarking of floating interest rate was suggested by an internal study group set up by the RBI to review the working of the MCLR system.
In its 'Statement on Developmental and Regulatory Policies', the RBI on Wednesday said, "The Report of the Internal Study Group to Review the Working of the Marginal Cost of Funds based Lending Rate (MCLR) System (Chairman: Dr. Janak Raj) released on October 4, 2017 for public feedback, had recommended the use of external benchmarks by banks for their floating rate loans instead of the present system of internal benchmarks [Prime Lending Rate (PLR), Benchmark Prime Lending Rate (BPLR), Base rate and Marginal Cost of Funds based Lending Rate (MCLR)]."
"...it is proposed that all new floating rate (for) personal or retail loans (housing, auto, etc) and floating rate loans to Micro and Small Enterprises extended by banks from April 1, 2019 shall be benchmarked" to repo rate, or 91/182 Treasury Bill yield or any other benchmark market interest rate produced by the Financial Benchmarks India Pvt Ltd (FBIL). The spread over the benchmark rate - to be decided wholly at banks' discretion at the inception of the loan - should remain unchanged through the life of the loan, unless the borrower's credit assessment undergoes a substantial change and as agreed upon in the loan contract," the RBI said.
4.Final guidelines by December end

The RBI will issue the final guidelines linking the interest rate to external benchmarks by the end of this month. Retail customers will get more transparent and a fair pricing for loans as new system will come into effect on April 1, 2019.


5.Borrower-friendly move

It will become difficult for banks to lure customers with lower rates and then raise rates surreptitiously. Under the new regime, banks will have the liberty to fix loan rates based on the present pricing system, but once fixed, it will be linked to an external benchmark announced by RBI. For instance, if it is pegged to the repo rate, whenever that rate changes, it will reflect in interest rates. Banks will not be able to change your interest rates unless the external rates change.
6.What are external benchmarks?

Banks will now have to follow one of the following external benchmarks to set the floating interest rate:
RBI Bank of India policy repo rate or Government of India 91 days Treasury Bill yield produced by the Financial Benchmarks India Private Ltd (FBIL) or Government of India 182 days Treasury Bill yield produced by the FBIL or Any other benchmark market interest rate produced by the FBIL
Currently, the policy repo rate stands at 6.50%. Whereas the overnight treasury yield presented by Financial Benchmarks India Private Ltd (FBIL) shows 6.47% from previous 6.50%.
7.Benchmark rate to remain unchanged

According to a Zee Business report, the spread over the benchmark rate — to be decided wholly at banks’ discretion at the inception of the loan — should remain unchanged through the life of the loan, unless the borrower’s credit assessment undergoes a substantial change and as agreed upon in the loan contract. This means that even if a bank has decided to hike a lending rate in near-term future, the old borrowers interest rate will not be impacted and continue to be remain as it is.