Hanuman Ansh box office collection Day 36: Neem Karoli Baba's biopic defeats Akshay Kumar, Saif Ali Khan; earns 110% more than Haiwaan, collects...
 Haiwaan box office collection Day 1: Akshay Kumar, Saif Ali Khan film takes disastrous opening, lower than flop Batwara 1947, earns only...
 BRICS Summit 2026: PM Modi raises safety of seafarers during meet with Iran's Pezeshkian
 Sandeep Reddy Vanga's brother dares reviewers to 'kill' Prabhas' Spirit, gives open challenge to critics: 'We will see when it...'
 Pageant Queen, Football Devotee: How Miss Argentina Alina Akselrad brought Lionel Messi to Miss World spotlightPageant Queen, Football Devotee: How Miss Argentina Alina Akselrad brought Lionel Messi to Miss World spotlight
 Maharashtra deputy CM Eknath Shinde felicitates Virat Kohli in London, hails India icon as 'down-to-earth'
 'Never asked for a stake': CSK shut down MS Dhoni takeover buzz, put spotlight on his actual shares
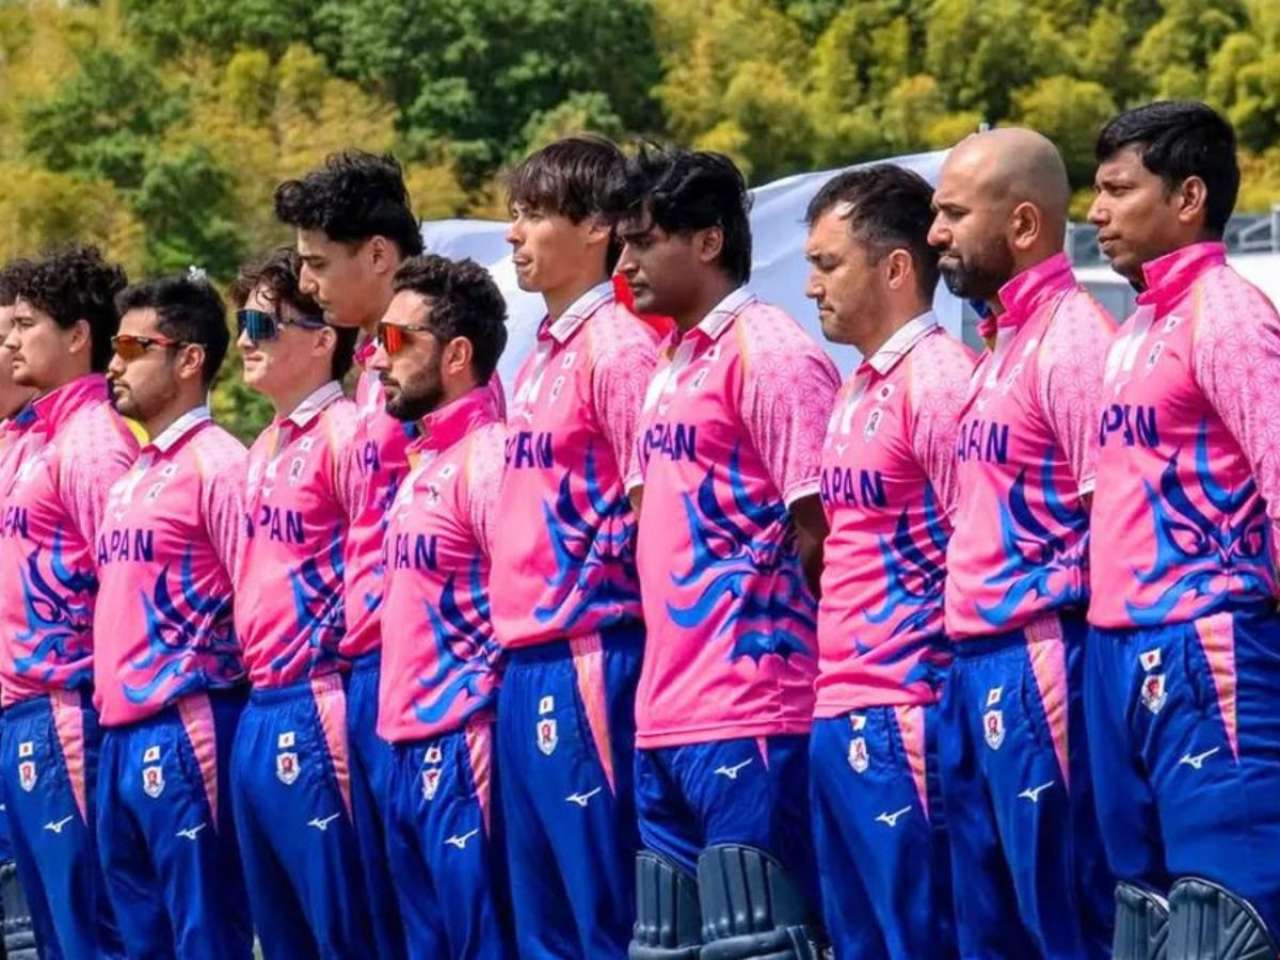 'Not here just to celebrate': Japan captain sends fearless warning ahead of historic T20I against India
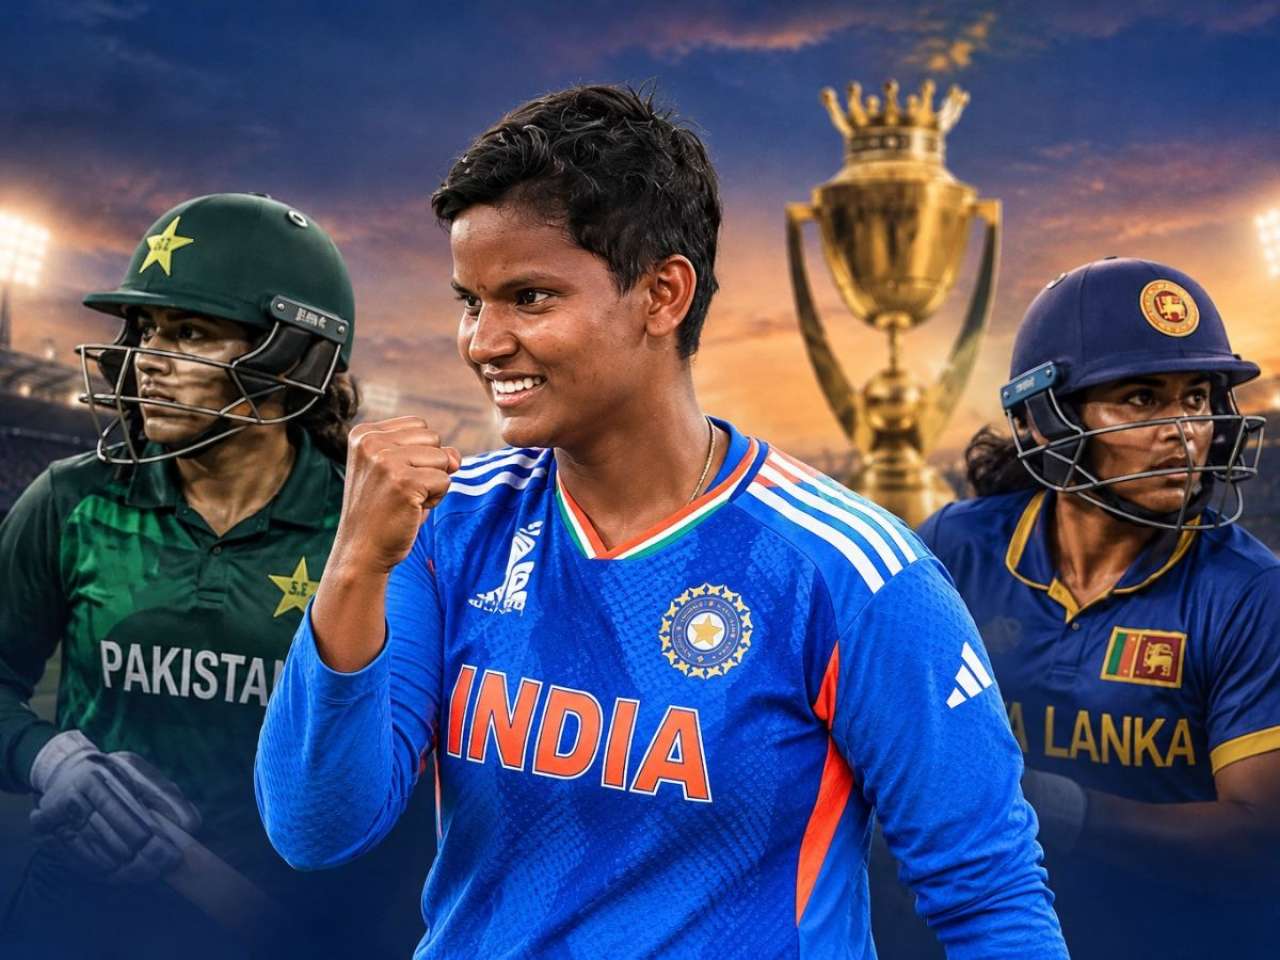 'Doesn’t matter who comes': Deepti Sharma declares India ready for any opponent in Women's Asia Cup title clashHanuman Ansh box office collection Day 36: Neem Karoli Baba's biopic defeats Akshay Kumar, Saif Ali Khan; earns 110% more than Haiwaan, collects...Haiwaan box office collection Day 1: Akshay Kumar, Saif Ali Khan film takes disastrous opening, lower than flop Batwara 1947, earns only...Sandeep Reddy Vanga's brother dares reviewers to 'kill' Prabhas' Spirit, gives open challenge to critics: 'We will see when it...'
 Rashmika Mandanna remembers her humble beginnings, calls aspiring girls to push their limits to 'dream big', partners with brain behind BTS for...
 SS Rajamouli, Mahesh Babu, Samantha Ruth Prabhu, Vijay Deverakonda in trouble? Here's why South stars get SIR notices
 BRICS Summit 2026: India To Push BRICS Digital Currency Link Despite Political & Technical Hurdles
 BRICS 2026: Putin Lands In Delhi For BRICS Summit To Hold Bilateral With PM Modi Today
 iPhone 18 Price: Why Apple iPhone 18 Range Is So Much Costlier In India Than US?
 US Iran News: US Destroys 5 Iranian Oil Tankers, Iran Strikes US Base In Jordan
 Karnataka News: Amazon, Swiggy, Instamart Stores Raided In B'luru; Expired, Mislabelled Items Seized
 8th Pay Commission: Why do Chennai GPO pensioners demand restoration of Old Pension Scheme? Will government do it?
 Crude oil price jumps above USD 108, hits 4-month high amid West Asia crisis; Know how it will impact India
 Gold, silver prices today, September 11, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Zee Business Bond Tokenization Summit 2026 Mumbai: Finance leaders discuss RWA tokenization future of digital bonds
 Gold, silver prices today, September 10, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 MS Dhoni to Virat Kohli: Indian cricket stars turn back time in viral 80s AI photo trend
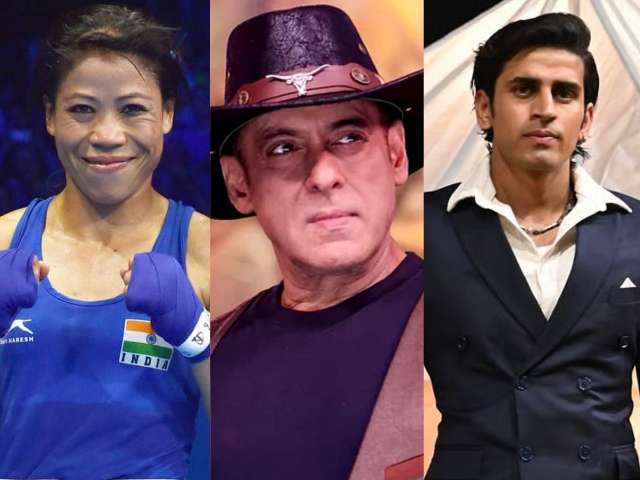 Bigg Boss 20: From Mary Kom, Mahhi Vij to Isha Rekhi, Qazi Touqeer, Rhiti Tiwari, Gullu; final confirmed list of contestants
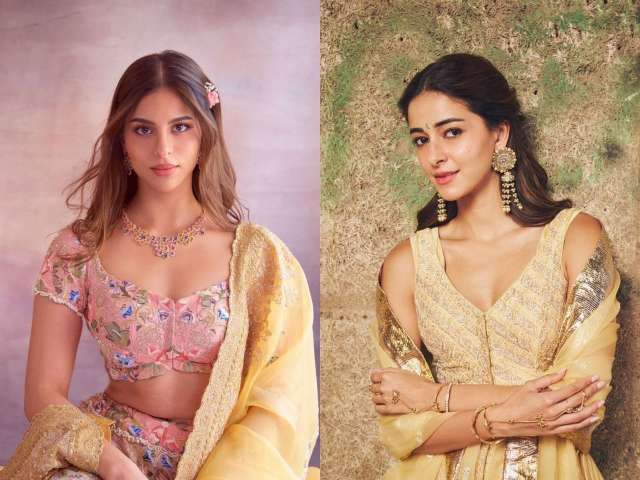 From Suhana Khan to Rasha Thadani, Ananya Panday: Gen-Z actresses acing modern-day Radha look in Janmashtami
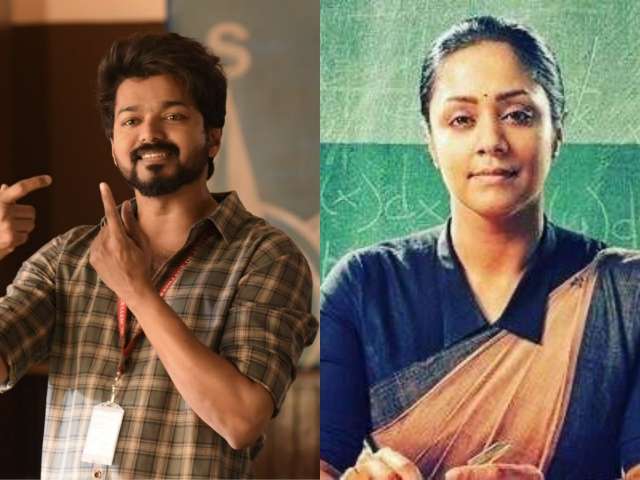 Teacher's Day 2026: From Thalapathy Vijay to Jyothika, 5 popular on-screen gurus from South that became household names
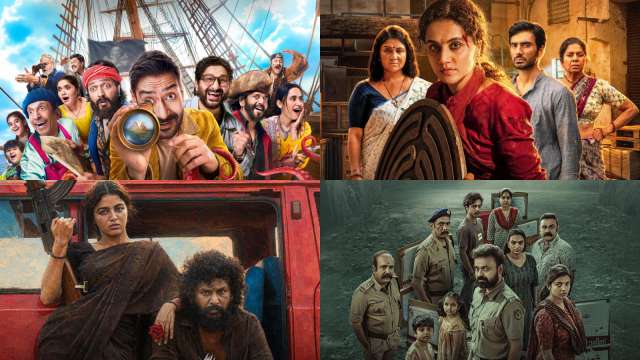 OTT Releases This Week: Dhamaal 4, Gandhari, DC, Bigg Boss 20; Indian movies, series to watch on Netflix, JioHotstar, ZEE5BRICS Summit 2026: PM Modi raises safety of seafarers during meet with Iran's Pezeshkian
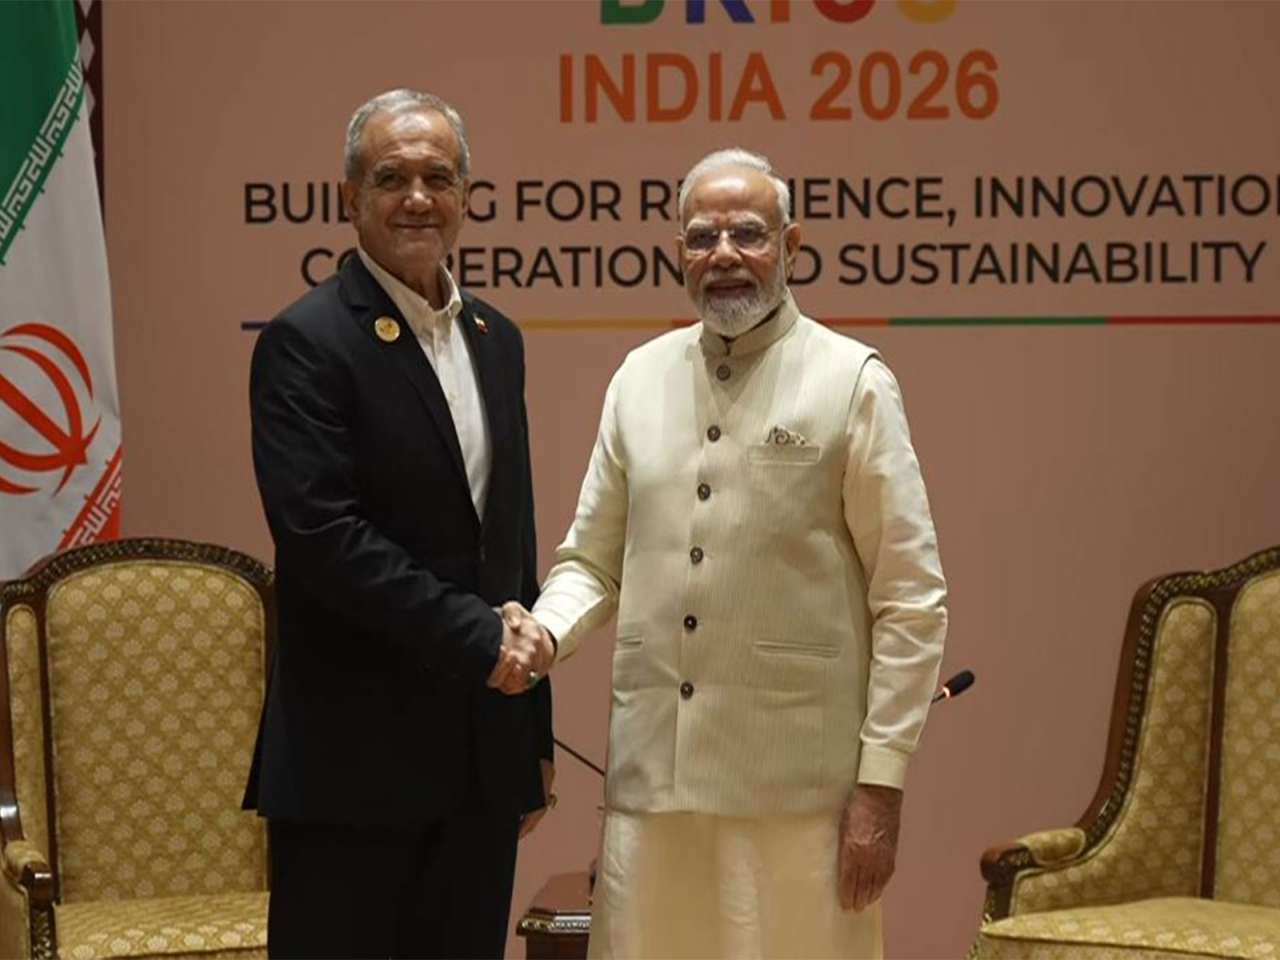 PM Modi holds bilateral meeting with Iran's Pezeshkian on sidelines of BRICS summit
 At BRICS, PM Modi says India building economic bridges: 'Our approach focused on reducing barriers'
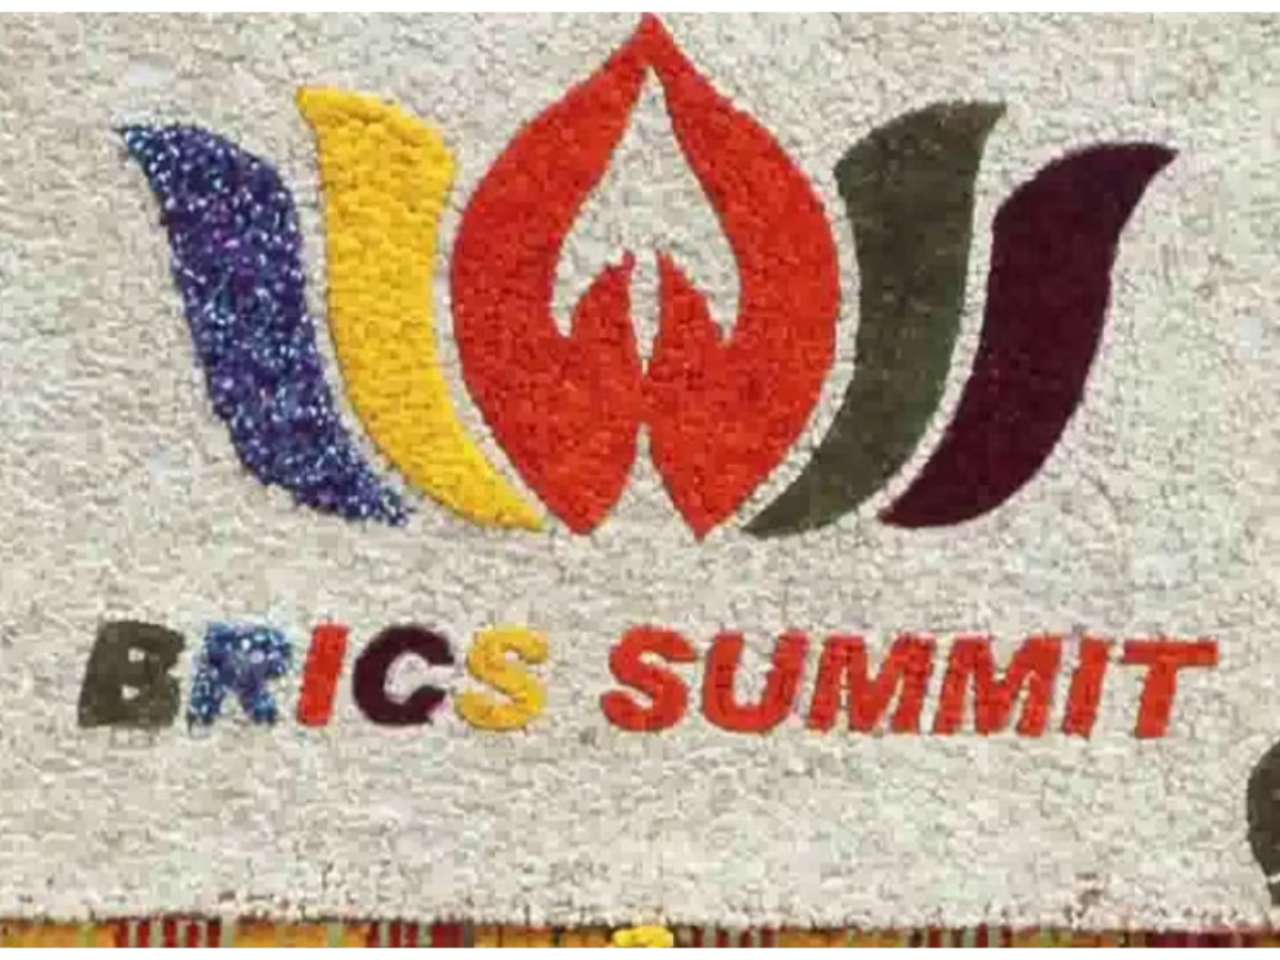 Why does India’s BRICS logo have lotus and ‘Namaste’? Here’s what it means
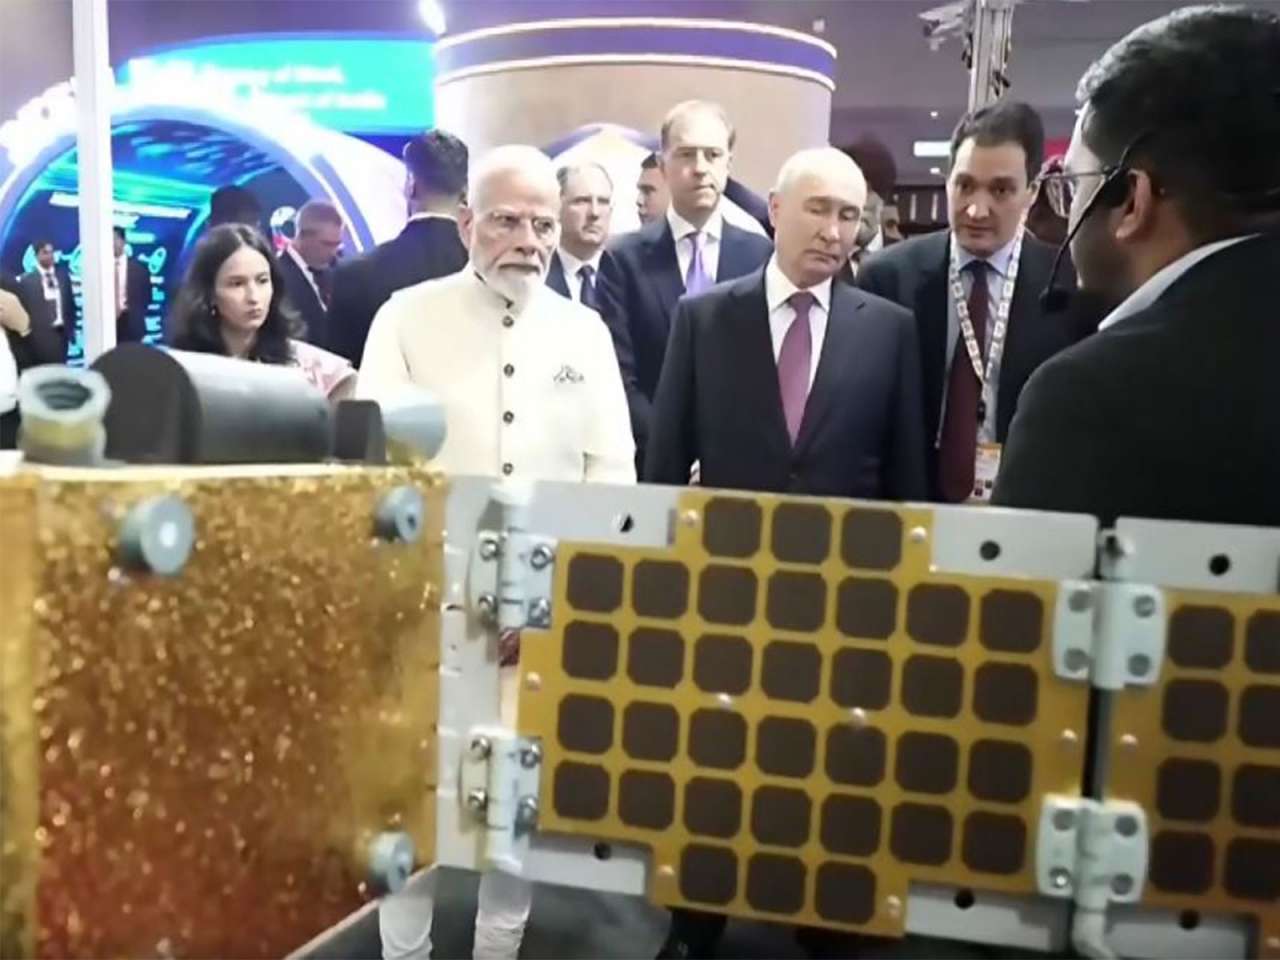 BRICS 2026: PM Modi, Putin visit INNOPROM exhibition after holding bilateral meet
 NEET PG Exam 2026: When will answer keys be released, how to access? Know here
 Teachers’ Day 2026: Heartfelt wishes, messages to make your favourite teacher feel special
 Who is Gyanendra Kumar Gangwar, IAS officer arrested in KPSC exam irregularities case?
 NLSIU cancels convocation amid row over CJI Surya Kant's proposed presence; CJP reacts
 GATE 2027 Registration: Application form to be available from August 27, check direct link, documents required and more
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
INSIGHTS
New tax slabs for 2025-26 increase tax-free income to ₹12.75 lakh for salaried individuals (including ₹75,000 standard deduction) and lower rates, boosting take-home pay.

Updated : Jun 11, 2025, 12:04 PM IST


The Union Budget 2025-26 was presented by the honourable Finance Minister Nirmala Sitharaman on February 1, 2025. It recommended several changes to India’s income tax system.
Majorly, the income tax slabs under the new regime were updated (along with several other policy changes). These amendments now significantly reduce the tax burden, particularly for middle-class salaried employees. This lets you keep more money in hand, which increases your disposable income.
Want to know about the latest changes? In this article, let’s study the latest income tax slab rates and learn how you can save more tax now! Also, we will see how you can use an income tax calculator to instantly calculate your tax liability.
The Union Budget 2025-26 has brought significant changes to the income tax slabs and corresponding tax rates (under the new regime). Let’s check them out through the table below:
|
Income slab |
Old tax rate |
New income tax slabs |
New tax rate |
|
Rs. 0 – Rs. 3 lakh |
Nil |
Rs. 0 – Rs. 4 lakh |
Nil |
|
Rs. 3 – Rs. 7 lakh |
5% |
Rs. 4 – Rs. 8 lakh |
5% |
|
Rs. 7 – Rs. 10 lakh |
10% |
Rs. 8 – Rs. 12 lakh |
10% |
|
Rs. 10 – Rs. 12 lakh |
15% |
Rs. 12 – Rs. 16 lakh |
15% |
|
Rs. 12 – Rs. 15 lakh |
20% |
Rs. 16 – Rs. 20 lakh |
20% |
|
Above Rs. 15 lakh |
30% |
Rs. 20 – Rs. 24 lakh |
25% |
|
|
|
Above Rs. 24 lakh |
30% |
Firstly, you must note that the basic exemption limit has been increased to Rs. 4 lakhs (from the previous limit of Rs. 3 lakhs). This extra Rs. 1 lakh at zero tax lets you save Rs. 5,000 in taxes directly.
Additionally, updated income tax slabs offer you the following benefits:
1. Lower tax on mid-level income (Rs. 8 lakhs to Rs. 16 lakhs)
Earlier, if your income was between Rs. 8 to 12 lakhs, you paid 10–15% tax. Now, you pay just 10%. Similarly, Rs. 12–16 lakh is now taxed at 15%, instead of up to 20%. This lowers the total tax you pay if your salary is in this bracket.
2. 30% tax now starts at Rs. 24 lakhs (Earlier Rs. 15 lakhs)
High-income earners (above Rs. 15 lakhs earlier) were paying 30%. Now, that rate is applicable only if your income exceeds Rs. 24 lakhs. This again leads to less income tax liability.
3. Increased standard deduction
Earlier, the standard deduction allowed for salaried employees was Rs. 50,000. Now, in the Union Budget 2025-26, this limit has been increased to Rs. 75,000 (under the new regime).
The revised income tax slab rates under the new regime are a big relief for middle-class salaried individuals like you. Earlier, you paid zero tax if your income (after standard deduction) was up to Rs. 7.75 lakh.
But now, from FY 25-26 onwards, this zero-tax limit has been raised to Rs. 12.75 lakh. This means if your salary (after Rs. 75,000 standard deduction) is Rs. 12.75 lakh or less, you will not have to pay any income tax under the new regime.
This lets you save more money and retain a bigger part of your salary. Also, it increases your ability to spend or invest.
However, please note that this tax rebate doesn’t apply to special incomes like capital gains (profit from selling shares, mutual funds, etc.). They are taxed separately at special rates.
Example showing zero tax on a salary of Rs. 12.75 lakh
Say your gross taxable income is Rs. 12.75 lakhs. Now, after applying the standard deduction of Rs. 75,000, your net taxable income gets reduced to Rs. 12 lakhs. Let’s see how this income will be taxed as per the latest income tax slabs (FY 2025–26):
|
Income tax slab |
Tax rate |
Tax amount |
|
Rs. 0 – Rs. 4,00,000 |
0% |
0 |
|
Rs. 4,00,001 – Rs. 8,00,000 |
5% |
20,000 |
|
Rs. 8,00,001 – Rs. 12,00,000 |
10% |
40,000 |
|
Total tax before rebate |
|
Rs. 60,000 |
|
Less: Rebate under Section 87A |
Up to Rs. 12.75 lakh |
Rs. 60,000 |
|
Net tax payable |
|
Rs. 0 |
We can clearly observe that though the calculated tax is Rs. 60,000, you get a full rebate under Section 87A. So, your final tax is Rs. 0.
Calculate your tax liability instantly with an income tax calculator
An income tax calculator is a simple online tool. Using it, you can easily calculate your accurate income tax liability under the new regime. The calculator comes loaded with:
Also, it allows you to input details like interest and principal paid on the home loan. Let’s learn how you can use it step-by-step:
Step I: Enter your annual income
The first slider lets you input your total taxable income for the year. As a salaried person, this usually includes your:
Step II: Input home loan interest
The second slider is for interest paid on a home loan. Under the new income tax regime, the Section 24(b) deduction for home loan interest is not available for self-occupied properties. However, if the property is let out (rented), you can still claim this deduction.
For more clarity, check out the table below:
|
Property type |
Old tax regime |
New tax regime |
|
Self-occupied |
A deduction of up to Rs. 2 lakh on home loan interest |
Not allowed |
|
Let-out (Rented) |
Full interest deduction without any upper limit |
Allowed |
Step III: Input principal repayment
The third slider refers to the principal portion of your home loan EMI. Under Section 80C of the old regime, this is eligible for deduction up to Rs. 1.5 lakh. This benefit is not available under the new tax regime.
After entering all the required information, the income tax calculator instantly calculates your income tax liability.
Conclusion
The revised income tax slabs under the new regime (as introduced in Budget 2025–26) are a significant advantage for middle-class salaried individuals. With the tax-free limit now raised to Rs. 12.75 lakh (after a Rs. 75,000 standard deduction), many taxpayers will have zero tax liability. This will result in greater take-home pay.
Additionally, further relief has been provided by:
To avoid manual calculations and instantly calculate your accurate income tax liability, you can start using an income tax calculator. It comes pre-loaded with all the latest amendments and has a user-friendly interface.
Disclaimer
This article is from the Brand Desk. User discretion is advised.