 US Treasury Secretary Bessent blames Commerce Dept for failure to blacklist Megaspeed in Nvidia scandal
 Air India suspends flights to Riyadh, Dammam, Jeddah amid Houthi attacks on Saudi
 Vijay Sethupathi reunites with Super Deluxe's director Thiagarajan Kumararaja after 7 years with Pocket Novel, announces Hindi release
 Kabaddi Champions League: Former India star Mohit Chhillar backs it for next generation
 Will Trump succumb to Netanyahu's pressure to attack Iran again? Israel intel chief visits WashingtonAir India suspends flights to Riyadh, Dammam, Jeddah amid Houthi attacks on Saudi
 Manipur: 4 killed as armed men ambush vehicles on NH-202 in New Heaven Village
 Who are Sonia Gandhi's sisters? What does she reveal about Nadia, Anoushka in 'Belonging: A Journey of Love '?
 Rasgulla Bomb? Man dies in MP as explosive hidden inside sweet explodes in mouth
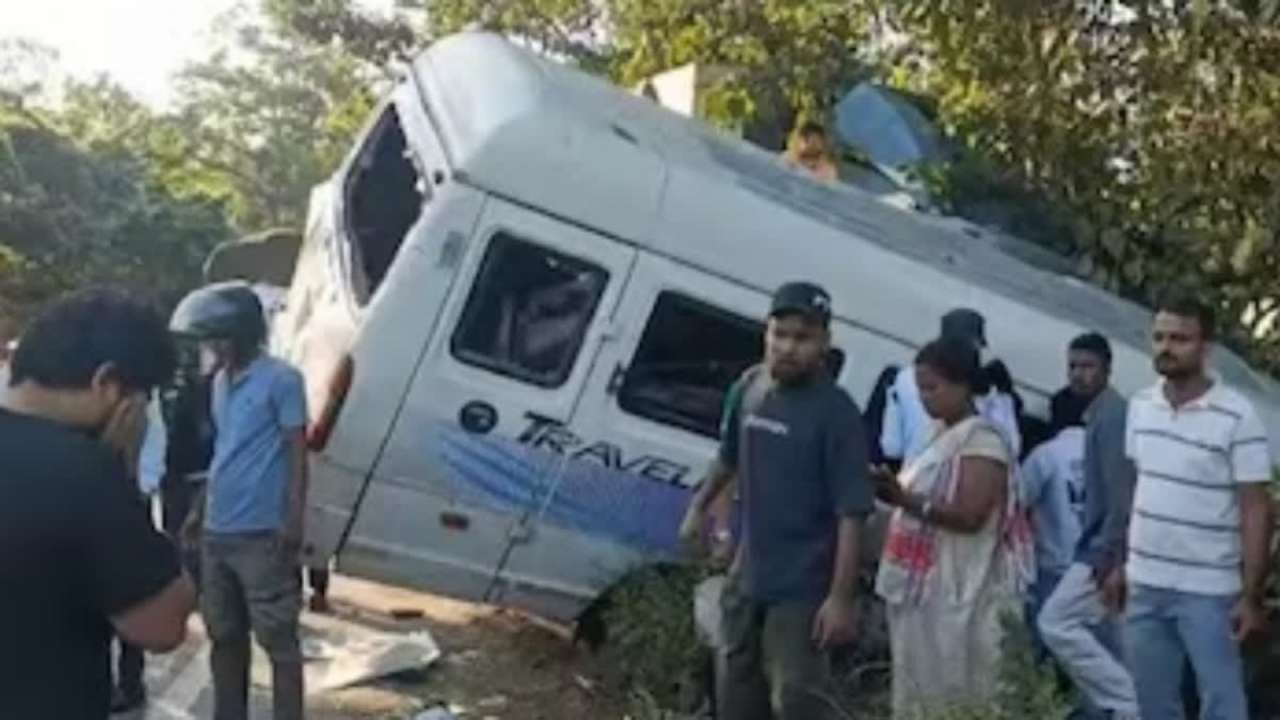 Assam Accident: 23 killed, several injured as truck hits traveller in KazirangaUS Treasury Secretary Bessent blames Commerce Dept for failure to blacklist Megaspeed in Nvidia scandalWill Trump succumb to Netanyahu's pressure to attack Iran again? Israel intel chief visits Washington
 Microsoft 365 Outage Update: Outlook, Teams restoration underway, 48-hour email delay continues
 Was Alice Huang Really A Chinese Spy? US intel has no definitive proof, divided over Jensen Huang affair
 From cleaning toilets to $4.5 trillion empire: Who is Jensen Huang? His Nvidia exit, China spy controversy
 Microsoft Global Outage: Why did Outlook stop working? How were airlines in India affected?
 Nvidia After Jensen Huang: Will India's AI dream face chip shortage or open door for new rivals?
 Why does inflation soar to 6.09% despite falling fuel prices, US-Iran war halt? RBI's next move under focus
 UP Elections 2027: Will Asaduddin Owaisi and Chandrashekhar Azad defeat BJP or help Yogi win?
 From Nvidia CEO Jensen Huang to top officials: 5 Alleged Chinese 'honey trap' cases that shocked worldVijay Sethupathi reunites with Super Deluxe's director Thiagarajan Kumararaja after 7 years with Pocket Novel, announces Hindi release
 Ayushmann Khurrana on celebrating Chhath Puja for first time with Yeh Prem Mol Liya, calls it 'beautiful tradition, completely new' to him
 Amrita Rao’s sister married: Preetika Rao ties knot in intimate ceremony, gets blessings of Spiritual leader Ravi Shankar
 Moushumi Chatterjee's husband, producer Jayanta Mukherjee, passes away at his Mumbai home
 Tinnu Anand makes FIRST big statement after suffering 5 rib fractures and punctured lung, shares health update
 Who will replace Jensen Huang at Nvidia? 3 Indian-origin executives in the race
 Zee Entertainment announces Rs 600 crore share buyback at Rs 91 per share
 Who may replace Nvidia CEO Jensen Huang? THIS Indian tech executive emerged among top contenders
 When CA Mukesh Jain Tested Kwala Intel: Inside the AI market wizard that money managers now swear by
 Tata Group Power Struggle Intensifies: Noel Tata quits boards of six companies, what next?Kabaddi Champions League: Former India star Mohit Chhillar backs it for next generation
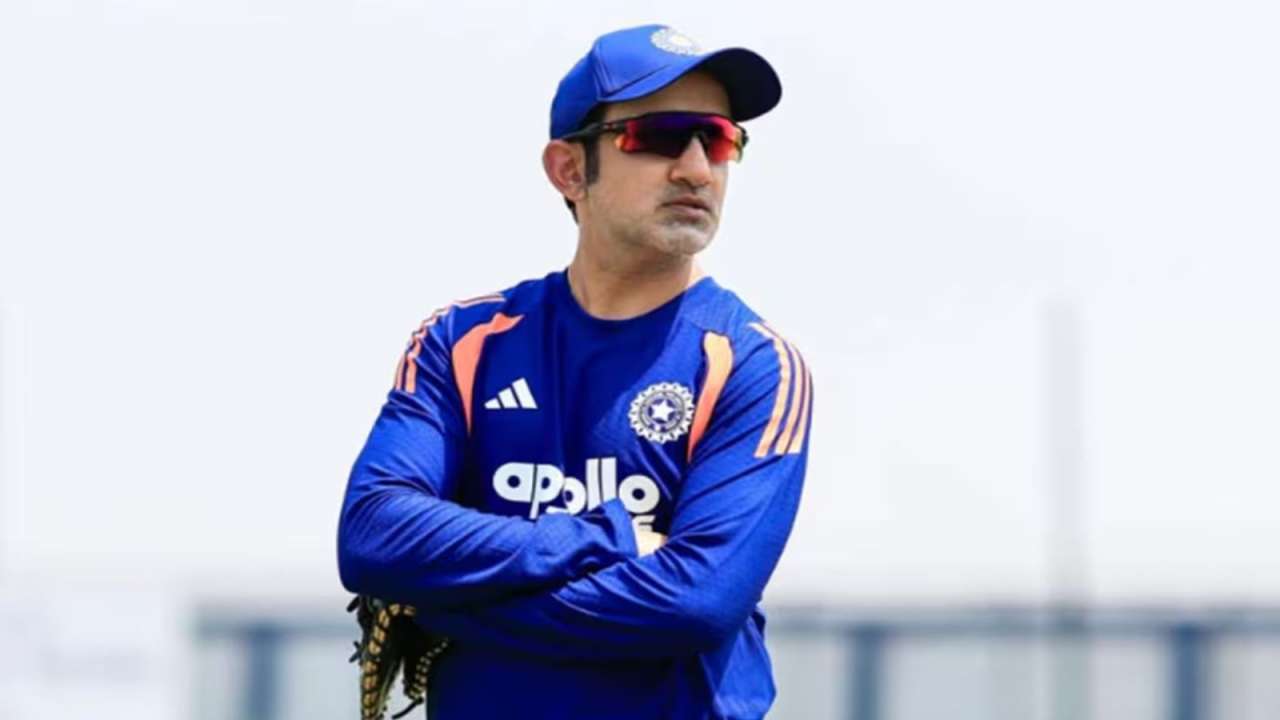 Gautam Gambhir loses patience after India's 89-run collapse against New Zealand, refuses to spare batters, slams Rohit, Kohli, Iyer
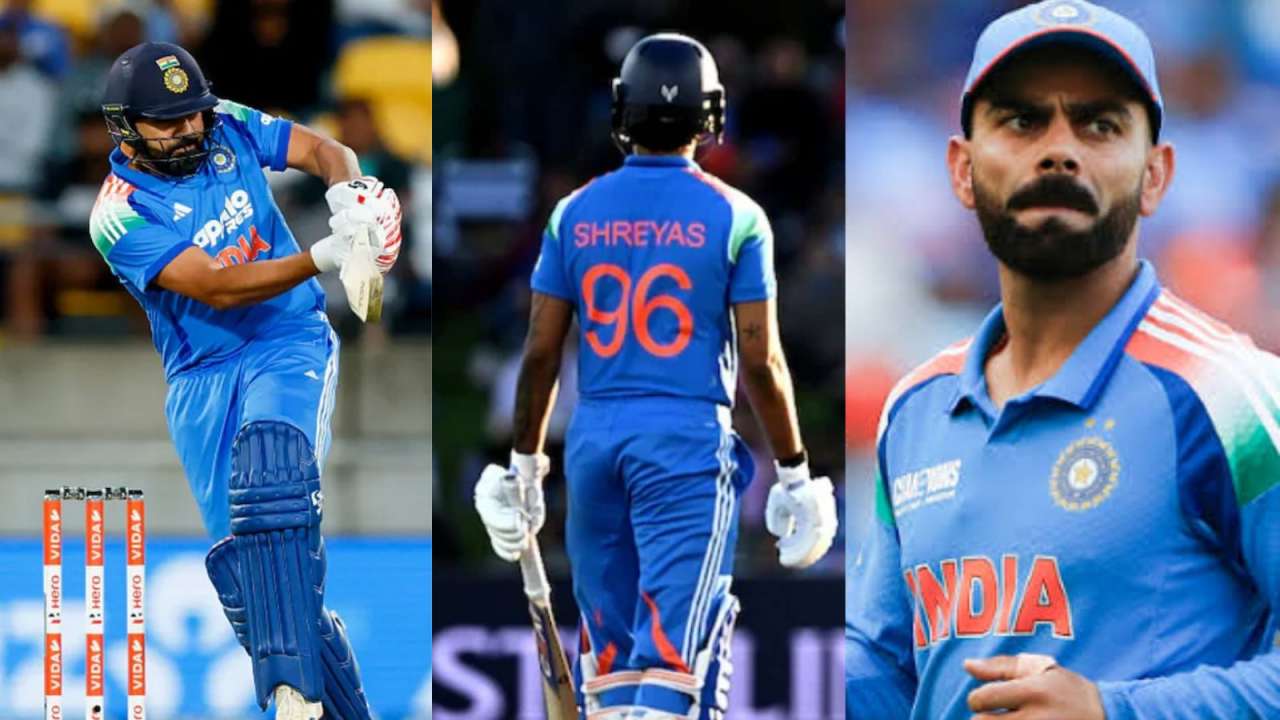 Rohit, Kohli, Shreyas Iyer fall for ducks! India suffer humiliating 89 all-out collapse
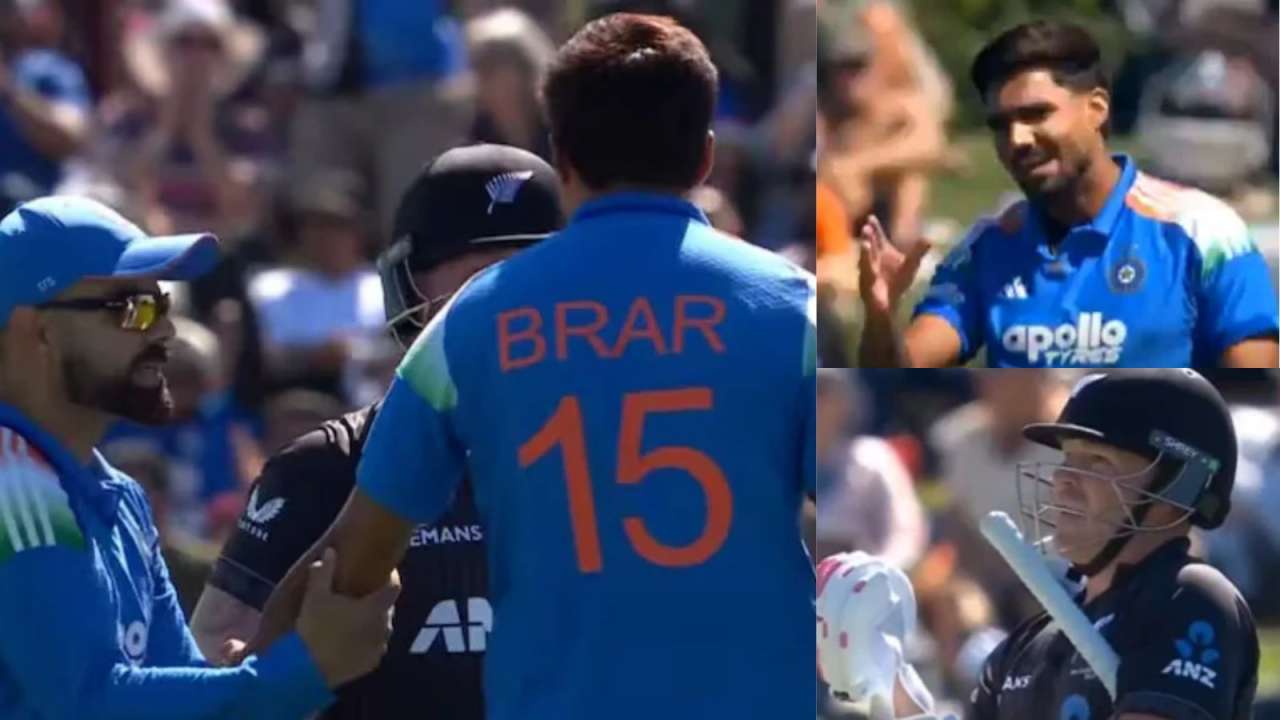 IND vs NZ 4th ODI: Virat Kohli's calm act goes viral after Gurnoor Brar clashes with Tim Seifert, Watch video
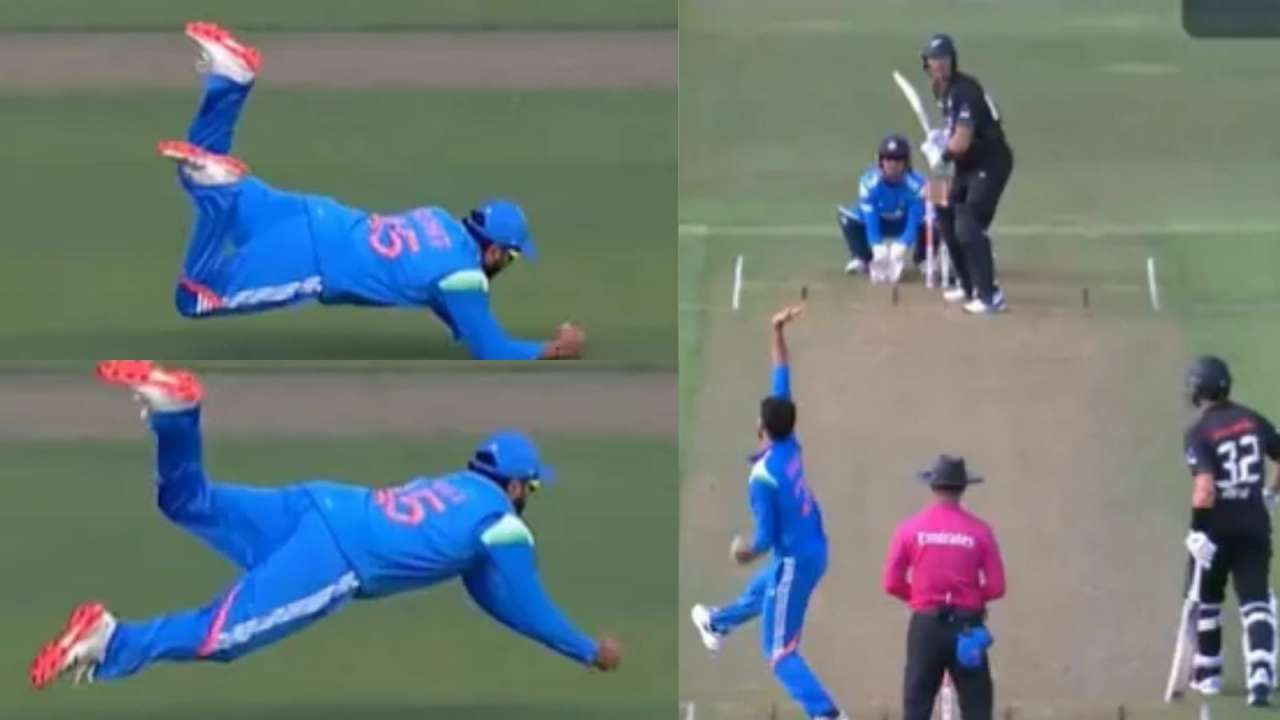 IND vs NZ ODI Series: Rohit Sharma's diving catch goes viral after he dismisses Finn Allen for 41, Watch
 Kaziranga Road Accident Update: Death Toll Rises To 24; Mini-Bus Had 13 Overspeeding Challans
 Bay of Bengal Cyclone Alert: Low-Pressure Area To Intensify By November 16; Yellow Alert In Odisha
 Microsoft 365 Outage Update: Gradual Recovery Underway After 20 Hours; Email Timeout Doubled to 48 Hrs
 Nvidia-Jensen Huang News: 'Would Be An Honor To Hire Him...' Will Musk Save Huang After Resignation
 J&K News: 'Won't Spare You...' 2 Days Before Kulgam Attack, CRPF Got Unexpected Warning By Boy
INSIGHTS
Installment loans are replacing high-APR payday loans due to flexible terms, lower interest rates, technological access, and regulatory support for sustainable credit.

Updated : Nov 21, 2025, 03:48 PM IST


A Powerful Story Told by Numbers
As the Americans are getting exposed to unprecedented charges and shaky bills, a huge change is being undertaken that would see the borrowers save thousands of dollars in fees in the long run in the personal lending arena. According to the recent report by TransUnion on the credit industry, the industry including the independent market on installment loans has gone bigger to reach 150-billion in 2024. This represents 45% growth over the last three years- this is in comparison to the 23% decline in the conventional volume of payday loans. Why is this dramatic change taking place?
The solution is in the fundamentals of the human psychology. The average payday loan interest rate (APR) is 400-700 per annum and is fully paid in 14 days.
On the other hand, installment loans have APRs of 36-199 and might take as long as six months and as many as years to be repaid. It is a difference that is dramatic to the borrowers concerned about their finances as it can make the difference between paying $150 in fee over a loan of one thousand dollars and spending 600 dollars and above!
Getting out of the Debt trap Cycle
In cases where borrowers can repay their loans in months rather than weeks, their chances of entering rollover cycles, which puts them into a vicious cycle of debts are 67 per cent less. Individuals who have had an installment loan not only spent their money in a more appropriate way but they also could significantly decrease both financial stress and credit score.
This is not only on timeframes where this flexibility can be found. It has such features as customized payment dates, so with the help of such services as Payday loans eLoanWarehouse service, LendingClub and Upstart, consumers can organize the process of repaying the loan in accordance with their paychecks. Other ones permit you to pay on installment when you are going through rough financial times.
Jonathan Reed, Founder and CEO at BestUSAPayday.com: "There has been a major shift in the expectations of borrowers being experienced now. People do not want to have a quick income anymore, but they desire the solution that will be available in the long term. Our eLoanWarehouse is a platform that we use to set up relationships between our borrowers and payment options that are priced at between 100 and 5000 dollars. The reason is that we have understood that flexibility is one of the most crucial aspects of becoming financially stable. When the customers are provided with the option of determining their own repayment conditions, the default rate will reduce by forty percent.
Technology Levels the Playing Field
The digital revolution has dramatically increased the speed at which access to installment loans can be realized. The development of financial technology allows making an approval immediately, fund the company on the same day, and perform complex risk evaluations, not limited to the standard credit score.
Avant and OppLoans businesses achieve the approval of borrowers who may struggle with more traditional lending institutions, using alternative data points such as employment history, education history and cash flow patterns.
This technological advance is particularly beneficial to poor populations. Although recent Federal Reserve statistics show that 39 percent of Americans are unable to pay an emergency cost of 400 dollars without involving themselves in debt, there is a positive change to what was the case a year ago where the figure stood at 40 percent. Ready installment loans are to the rescue of such individuals. The mobile-first platforms have cut application times by hours down to minutes and some lenders say they are giving approval to applicant verified to 80 percent.
The Regulatory Environment Changes
Since 2022 state governments have observed how 18 states have issued rules that prefer installment loans to payday loans. The Fair Access to Credit Act of California, as one example, restricts interest rates and increases the minimum conditions of repayment. In practice, this compels lenders in a direction of an installment product. These policy reforms indicate that as time went by we have realised that the truly sustainable lending practices must be the norm due to their positive effects to the society at large.
The leaders in the industry are changing fast. The portfolios of the traditional payday lenders, including ACE Cash Express and Check 'n Go, have more than 60 percent installment loans. Lending clubs are not left behind in the game, credit unions are also joining the fray with their own installment based payday alternative loans which can also have an APR that will be limited to 28% also.
Future: The Future of Flexible Lending
It is possible to expect the installment loan space will become even more innovative as we proceed. There is even a promise of even more personalized repayment plans by using artificial intelligence (AI) and such could theoretically alter conditions in response to the financial circumstances prevailing at the time. The blockchain technology will further reduce costs and this will be transferred to the borrowers. Several financial institutions are already doing some experiments in terms of hybrid models in which the flexibility of installments is mixed with the stimuli of early repayment.
The move toward installment loans can be seen as an indication of a radical reevaluation of the role of credit in the contemporary America, as it not only marks a tendency in the banking industry. The lending sector is adapting to the increasing demand of the borrowers towards the financial products to be respectful, flexible and sustainable by devising solutions that would consider the complexity of real life.
The United States is filled with millions of people who are struggling to make ends meet and the spread of the flexible installment loans gives them worthy choices. The ability to pay in their conditions, credit-building and meeting daily needs, and escape the tyrannical grip of rollover debt are all achievements that can be attained. This flexibility is not only convenient but a revolution in a currently experiencing escalation in the occurrence of financial shocks in an economy.
Disclaimer:
This article is from the Brand Desk. User discretion is advised.