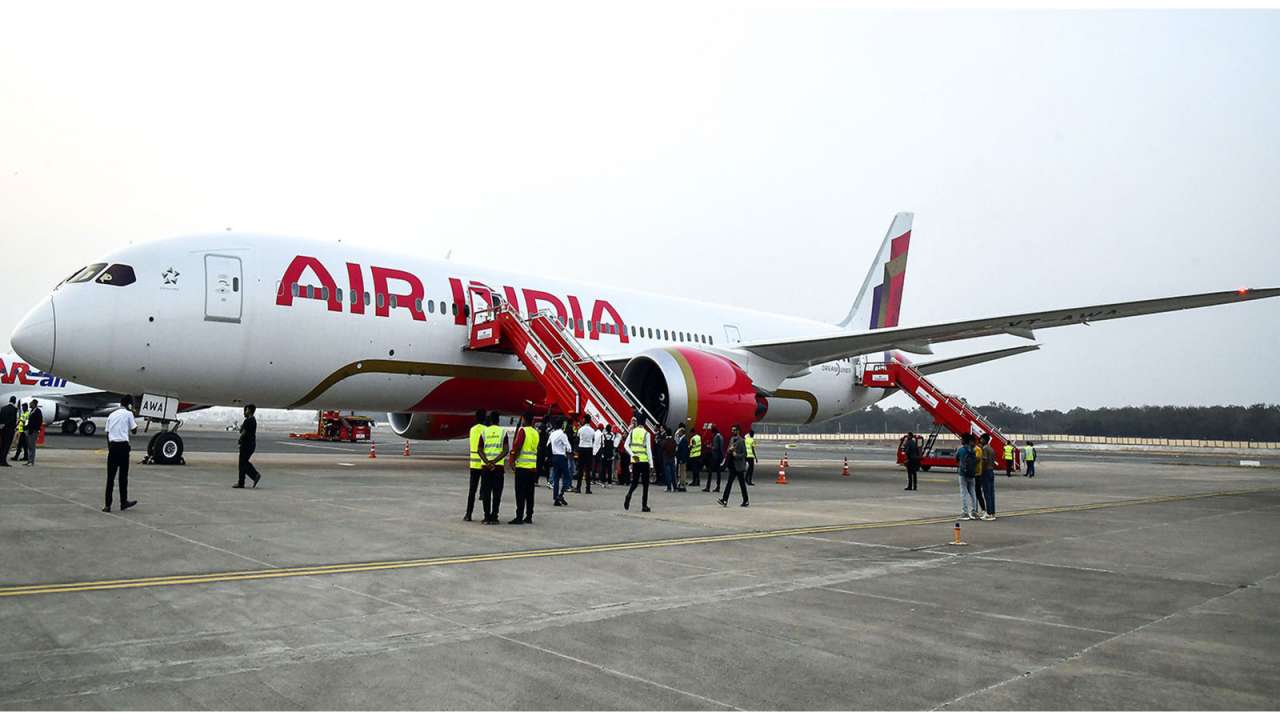
 Air India suspends flights to Riyadh, Dammam, Jeddah amid Houthi attacks on Saudi
 Vijay Sethupathi reunites with Super Deluxe's director Thiagarajan Kumararaja after 7 years with Pocket Novel, announces Hindi release
 Kabaddi Champions League: Former India star Mohit Chhillar backs it for next generation
 Will Trump succumb to Netanyahu's pressure to attack Iran again? Israel intel chief visits Washington
 Ayushmann Khurrana on celebrating Chhath Puja for first time with Yeh Prem Mol Liya, calls it 'beautiful tradition, completely new' to himAir India suspends flights to Riyadh, Dammam, Jeddah amid Houthi attacks on Saudi
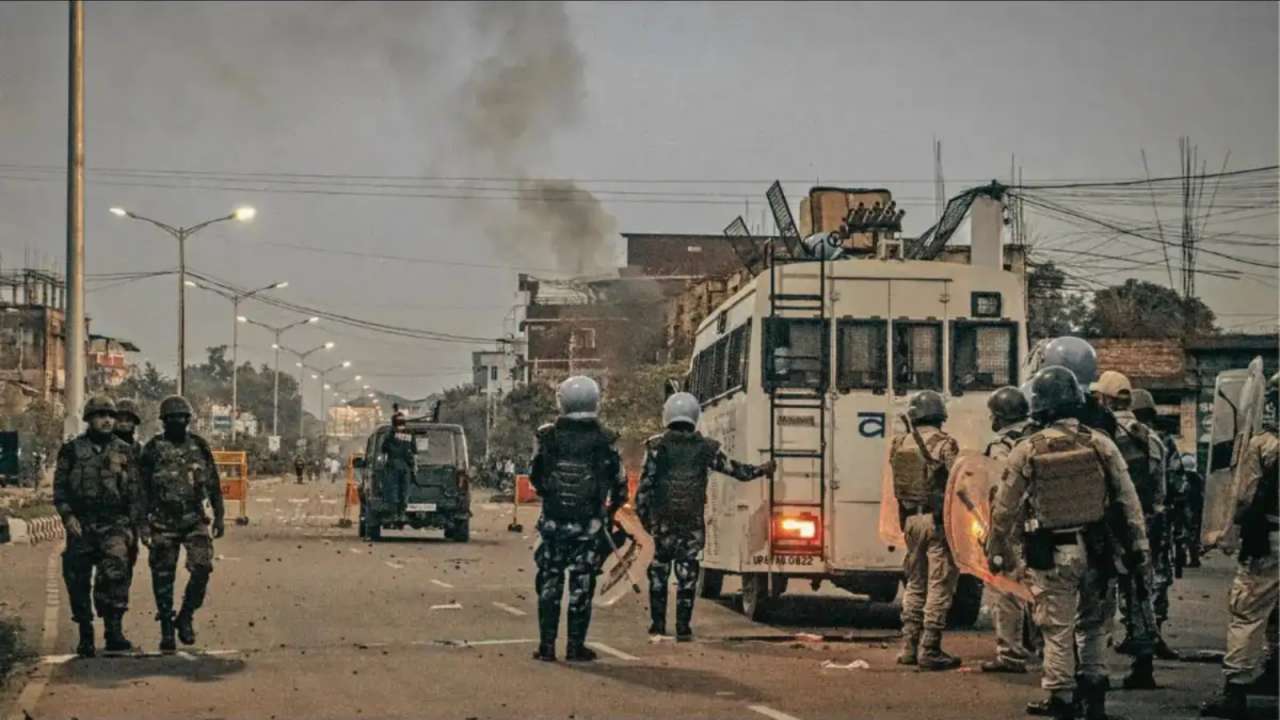 Manipur: 4 killed as armed men ambush vehicles on NH-202 in New Heaven Village
 Who are Sonia Gandhi's sisters? What does she reveal about Nadia, Anoushka in 'Belonging: A Journey of Love '?
 Rasgulla Bomb? Man dies in MP as explosive hidden inside sweet explodes in mouth
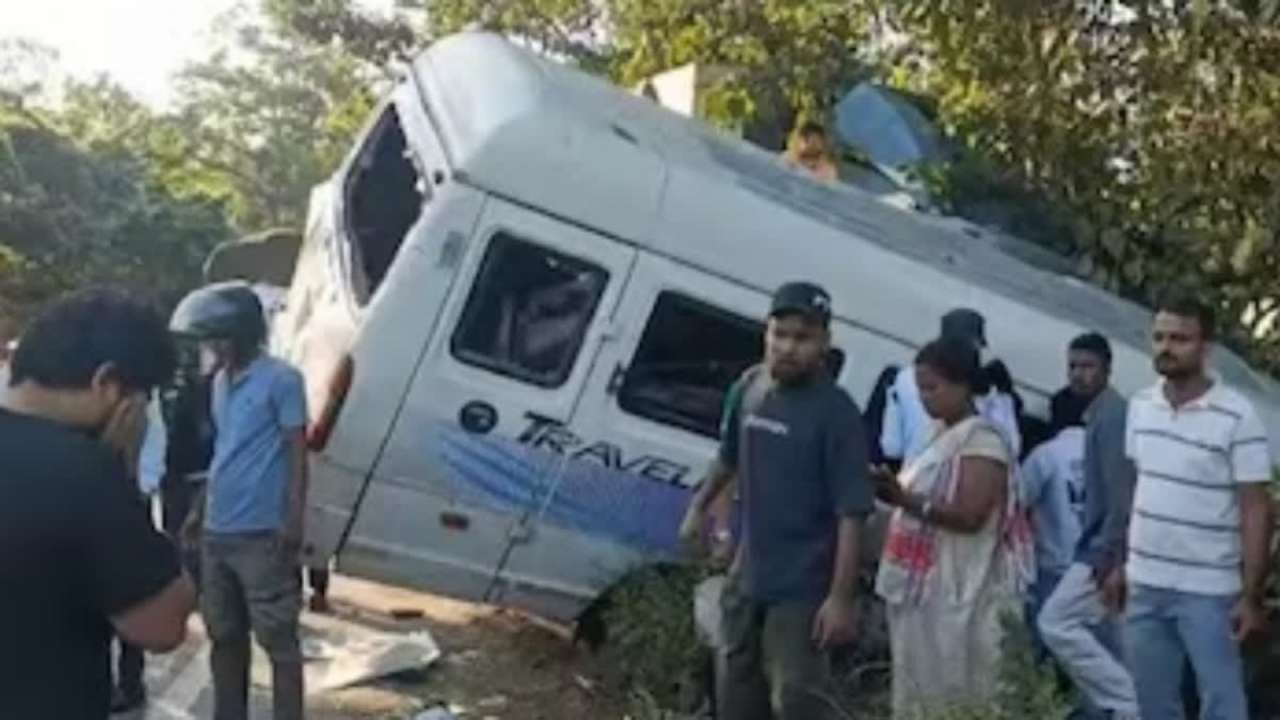 Assam Accident: 23 killed, several injured as truck hits traveller in KazirangaWill Trump succumb to Netanyahu's pressure to attack Iran again? Israel intel chief visits Washington
 Microsoft 365 Outage Update: Outlook, Teams restoration underway, 48-hour email delay continues
 Was Alice Huang Really A Chinese Spy? US intel has no definitive proof, divided over Jensen Huang affair
 From cleaning toilets to $4.5 trillion empire: Who is Jensen Huang? His Nvidia exit, China spy controversy
 Nvidia CEO's Pathetic Final Hours In Office: Shattered Jensen Huang turns penitent, says, 'I am a piece of sh*t'
 Microsoft Global Outage: Why did Outlook stop working? How were airlines in India affected?
 Nvidia After Jensen Huang: Will India's AI dream face chip shortage or open door for new rivals?
 Why does inflation soar to 6.09% despite falling fuel prices, US-Iran war halt? RBI's next move under focus
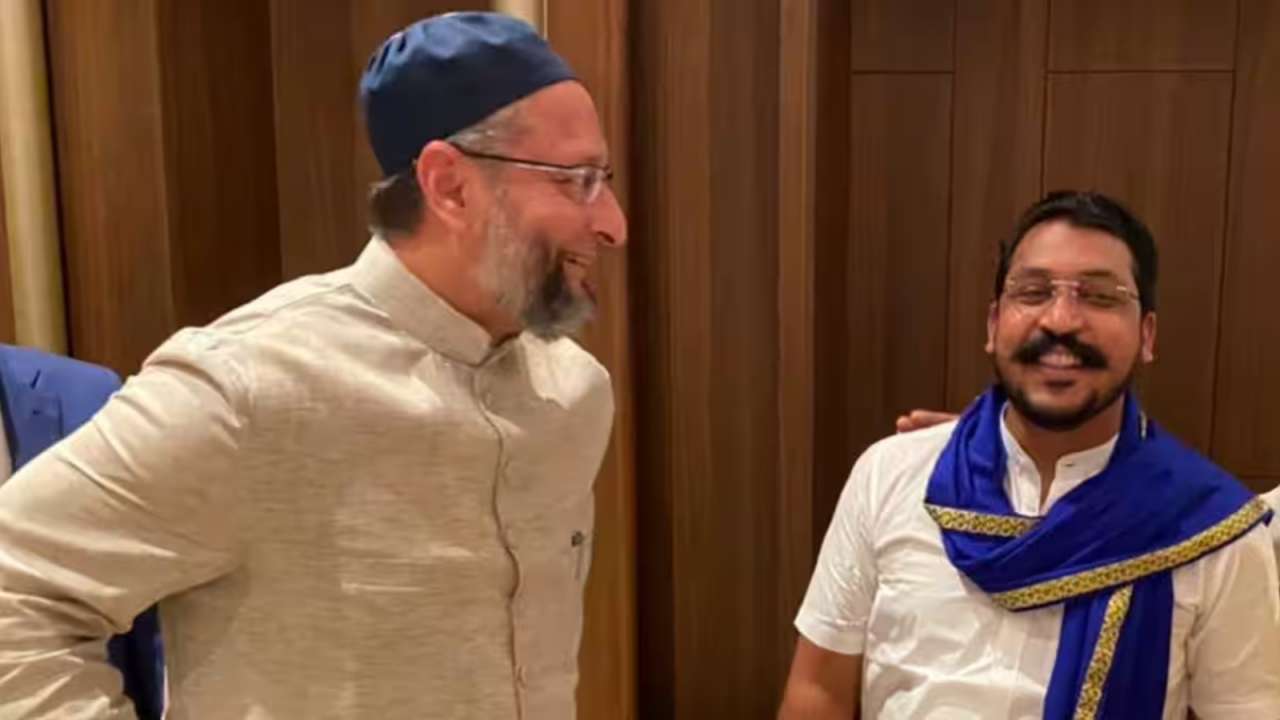 UP Elections 2027: Will Asaduddin Owaisi and Chandrashekhar Azad defeat BJP or help Yogi win?
 From Nvidia CEO Jensen Huang to top officials: 5 Alleged Chinese 'honey trap' cases that shocked worldVijay Sethupathi reunites with Super Deluxe's director Thiagarajan Kumararaja after 7 years with Pocket Novel, announces Hindi releaseAyushmann Khurrana on celebrating Chhath Puja for first time with Yeh Prem Mol Liya, calls it 'beautiful tradition, completely new' to him
 Amrita Rao’s sister married: Preetika Rao ties knot in intimate ceremony, gets blessings of Spiritual leader Ravi Shankar
 Moushumi Chatterjee's husband, producer Jayanta Mukherjee, passes away at his Mumbai home
 Tinnu Anand makes FIRST big statement after suffering 5 rib fractures and punctured lung, shares health update
 Who will replace Jensen Huang at Nvidia? 3 Indian-origin executives in the race
 Zee Entertainment announces Rs 600 crore share buyback at Rs 91 per share
 Who may replace Nvidia CEO Jensen Huang? THIS Indian tech executive emerged among top contenders
 When CA Mukesh Jain Tested Kwala Intel: Inside the AI market wizard that money managers now swear by
 Tata Group Power Struggle Intensifies: Noel Tata quits boards of six companies, what next?Kabaddi Champions League: Former India star Mohit Chhillar backs it for next generation
 Gautam Gambhir loses patience after India's 89-run collapse against New Zealand, refuses to spare batters, slams Rohit, Kohli, Iyer
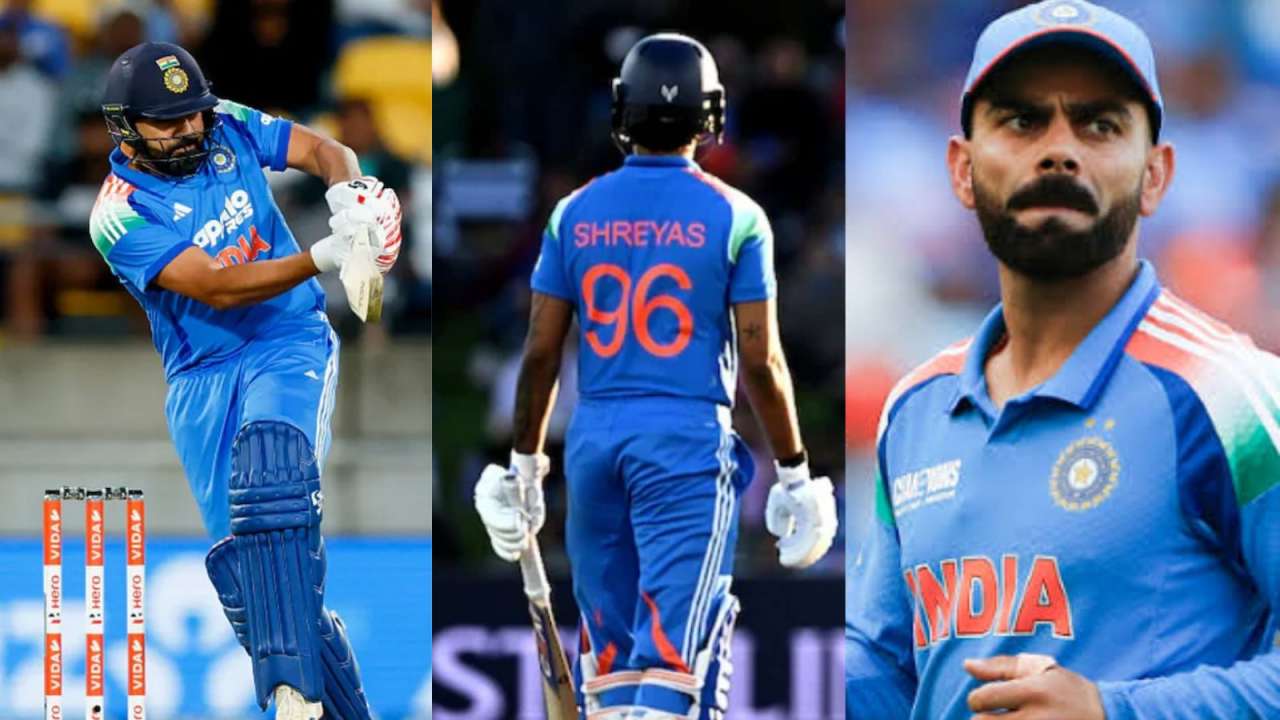 Rohit, Kohli, Shreyas Iyer fall for ducks! India suffer humiliating 89 all-out collapse
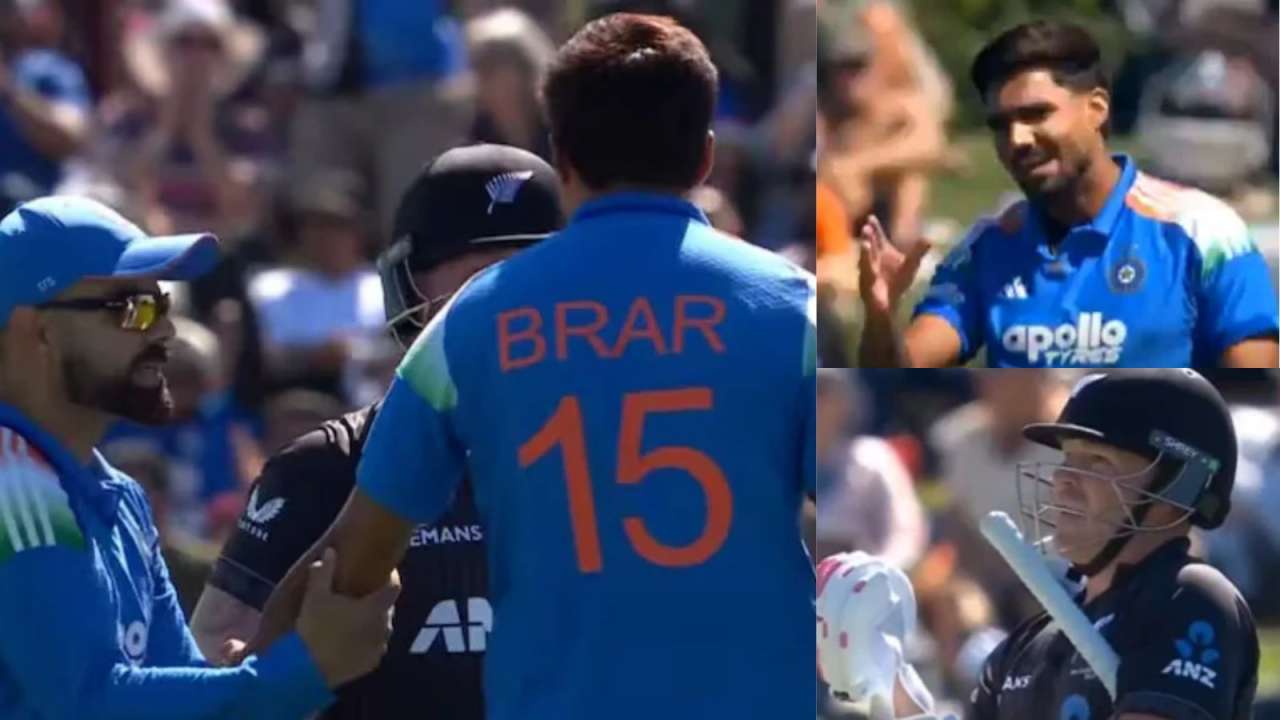 IND vs NZ 4th ODI: Virat Kohli's calm act goes viral after Gurnoor Brar clashes with Tim Seifert, Watch video
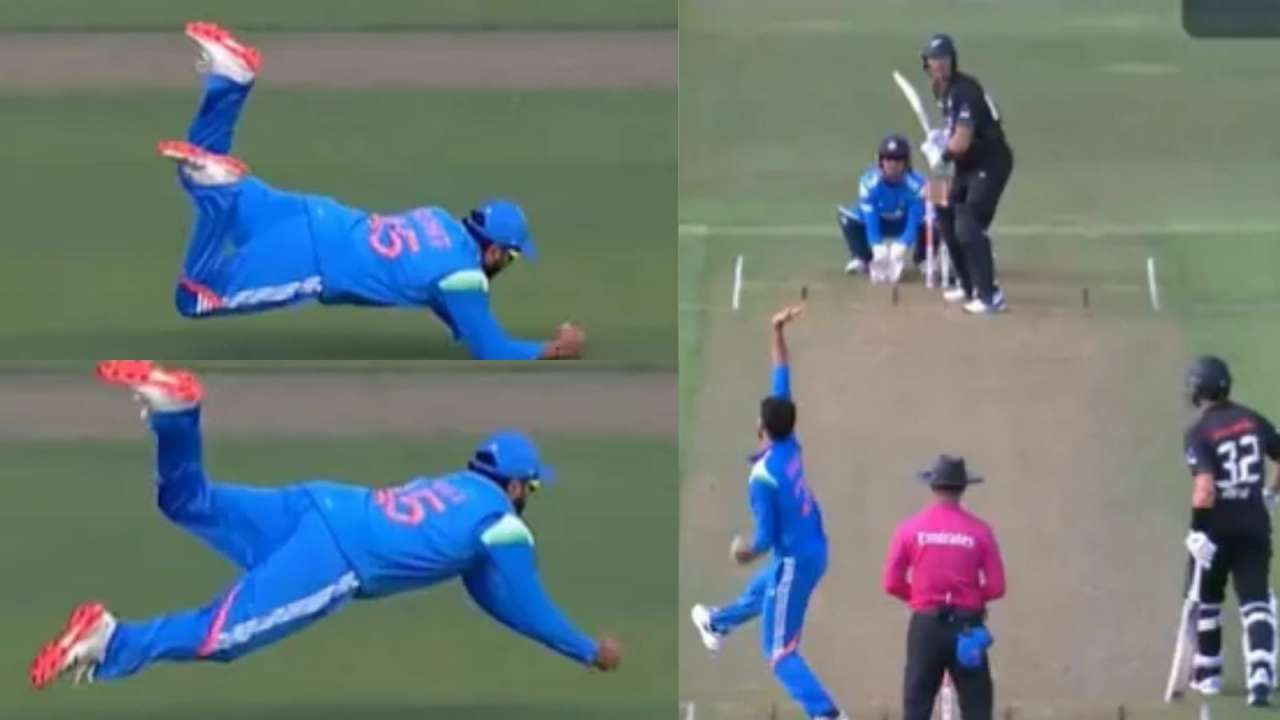 IND vs NZ ODI Series: Rohit Sharma's diving catch goes viral after he dismisses Finn Allen for 41, Watch
 Nvidia-Jensen Huang News: 'Would Be An Honor To Hire Him...' Will Musk Save Huang After Resignation
 J&K News: 'Won't Spare You...' 2 Days Before Kulgam Attack, CRPF Got Unexpected Warning By Boy
 J&K News: Two Special Police Officers Who Went Missing In Kishtwar District Found Dead
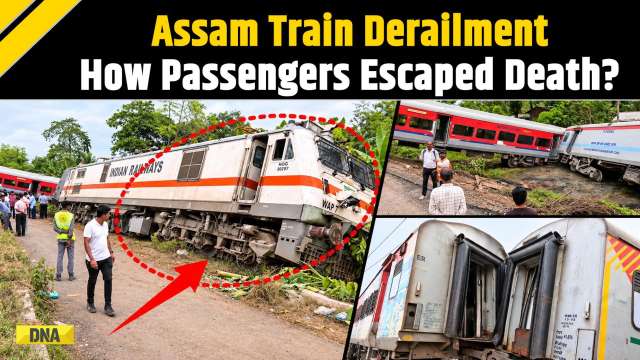 Assam Train Accident: 'Break Failure Or Control Loss...' 300 Passengers Escape Death; What Happened?
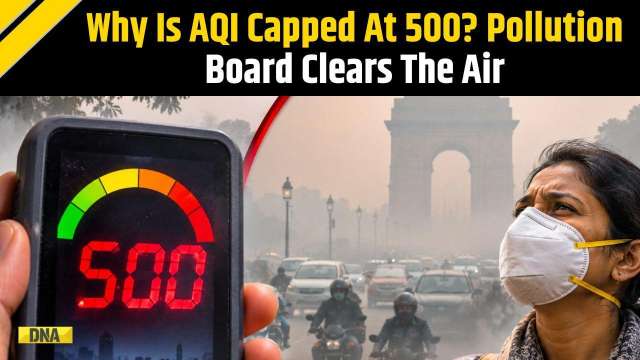 Delhi AQI News: Why India’s Official AQI Stops At 500 While Private Apps Show Readings Above 1,500
BUSINESS
A seemingly innocuous statement by the US Treasury secretary set the tone for pessimism – with equities yet again selling off and Treasury yields dropping to nine-month lows.

Updated : Dec 31, 2018, 05:25 AM IST


In a truncated, Christmas mood and holiday ridden week, there was not much of lull in the market. And each passing week still looks like the last. Fundamentally there was nothing much to write home about, but investor sentiment is palpably getting worse by the day. A seemingly innocuous statement by the US Treasury secretary set the tone for pessimism – with equities yet again selling off and Treasury yields dropping to nine-month lows.
The investment-grade bond segment saw some volatility which was mostly driven by year-end portfolio rebalancing. Indian equity markets clawed back the previous week's sell-offs, currency remained stable but bond yields, however, ended the week sharply higher on news of large farm waiver.
While one expected the quarter-per cent US Fed's rate hike, the accompanying comments continue to rattle markets. The statements appear to suggest uncertainty and worrisome pointers to growth momentum. Adding fuel to fire was Treasury's Mnuchin statement when he said through twitter that "he had conferred with executives of the nation's largest banks that there was no liquidity crisis and all was well". By raising a pre-emptive assurance when one thought all was indeed well, his assurances wrought an opposite effect.
 Markets could well open in the new year with cautious optimism. To take a balanced view without emotions, one would note that neither economists nor financial analysts share the pessimism that investors do. It is, therefore, more than likely that the market sell-off has been overdone. In other developments, US-China tensions had been abating but resurfaced on espionage rumours. The volatility is just not confined to prices but also to the quality of news on the twitterati. Trumps week-end tweets are assuring enough. Data releases appeared to have little impact on markets as the government shutdown was forcing some delays in data reports.
Indian markets continued its good run into the past week. Bonds remained well bid until Thursday. Equities inched up and one may have thought the magical 11000-mark in the Nifty index must have have been surmounted. The rupee traded with a strengthening bias, more a function of a weaker dollar in overseas markets. What however soured the weekend was the sell-off in bonds post auction results on Friday. While the auction was well bid and the cutoffs came as expected, it was some news about the quantum of budgetary allocation that may need to be allocated for farm waiver. The numbers are all over the place with estimates ranging from Rs 1-3 lakh crore. While there is not much of clarity, it clearly is a sentiment-dampener. Bond valuations may suffer hard if this sell-off continues.
Spreads continue to lag the sharp bond rally. State development loan papers and triple-A bond yields continue to remain sticky and the compression in yields which would have been an endorsement of a change in sentiment is missing. The 10-year bond should range between 7.25-7.45 with a bias to trade closer to the lower end of the range.
The writer is a market expert