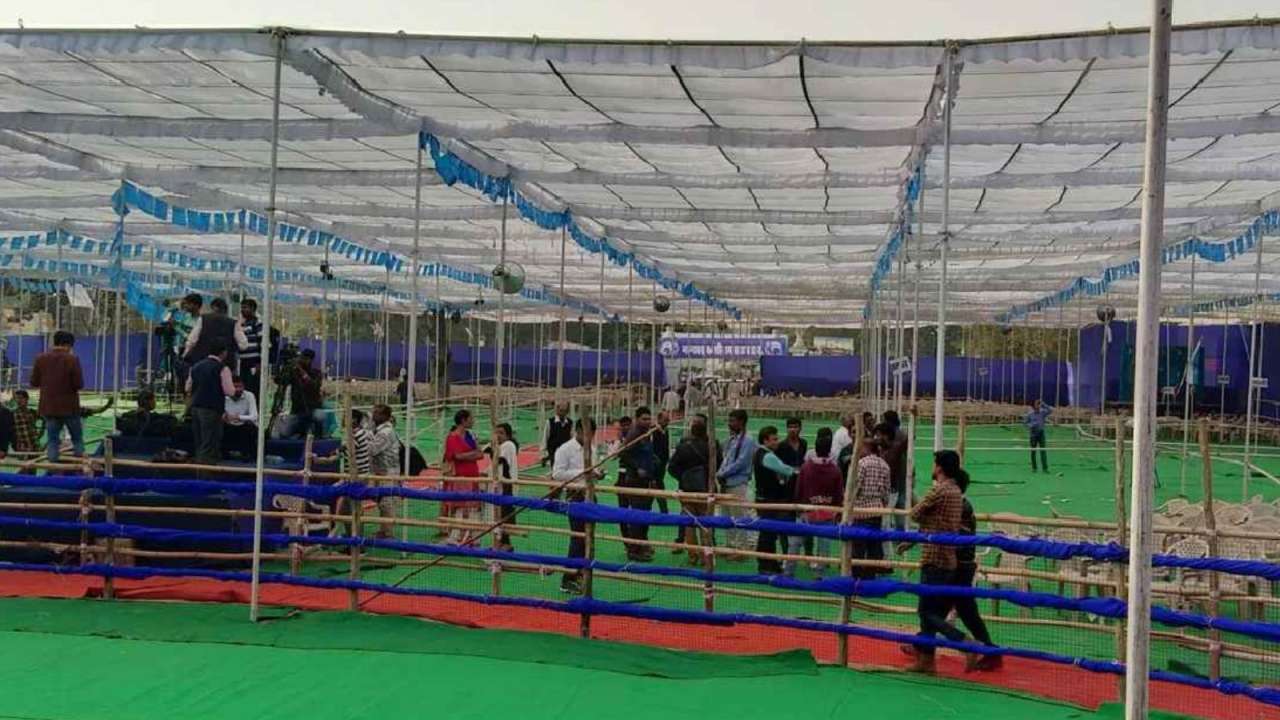
 Want to protest at Ramlila Maidan? Delhi's new protest cost Rs 1.21 lakh daily, check booking booking details, slots and more
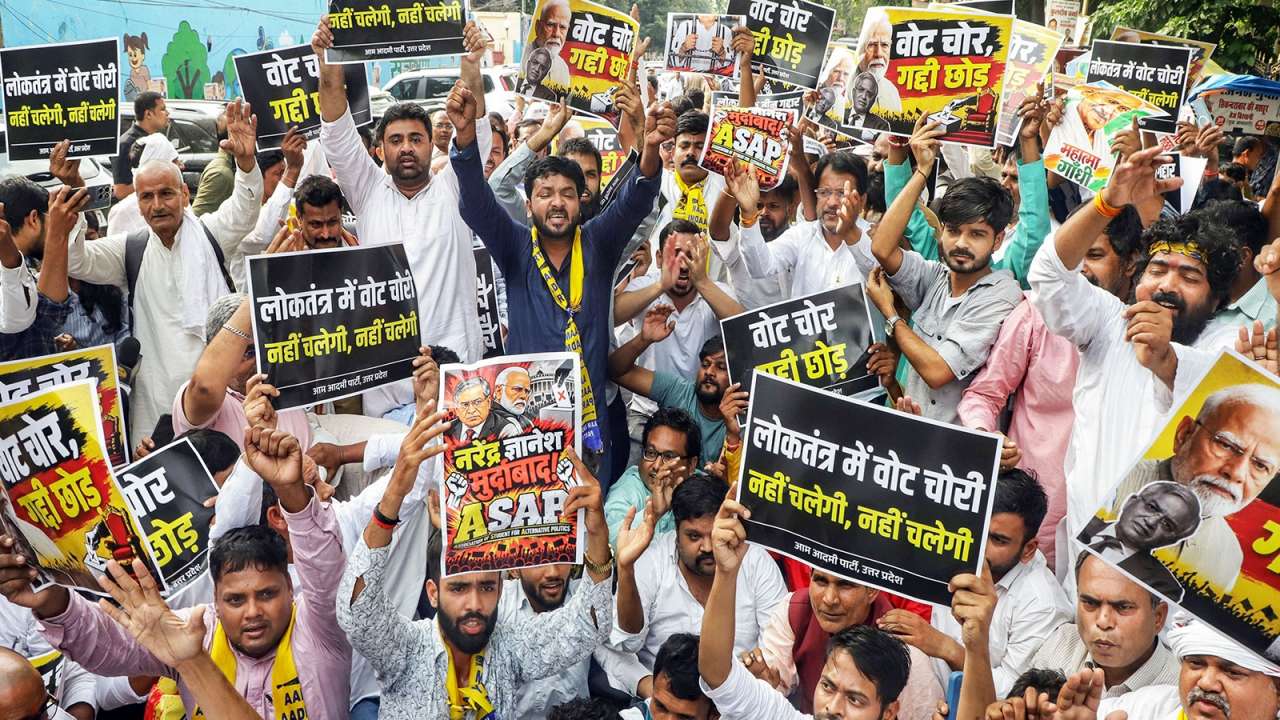 Kerala Congress sacks worker for 'irresponsible' CJI post, deletes message after BJP criticism
 How BJP government is fighting back as Delhi protest against CEC Gyanesh Kumar deepens?
 AAP leaders to hold one-day hunger strike against CEC Gyanesh Kumar on Oct 15
 Supreme Court registry flags 14 defects in INDIA bloc's petition over SIR irregularities: What are they
 Will match venue change for India vs Sri Lanka 1st ODI from Delhi to Ahmedabad? BCCI finally breaks silence
 Why Neeru Dhanda chose to dedicate her Asian Games medals to Indian Army?
 PCB changes match venues after emergency declaration in Pakistan province
 'Terrible human being’: Ex-India pacer Venkatesh Prasad takes scathing dig at Elon Musk amid escalating Starlink India row
 Fact Check: Did Virat Kohli really play in Mumbai’s Kanga League? Mystery behind viral No. 18 clip revealed
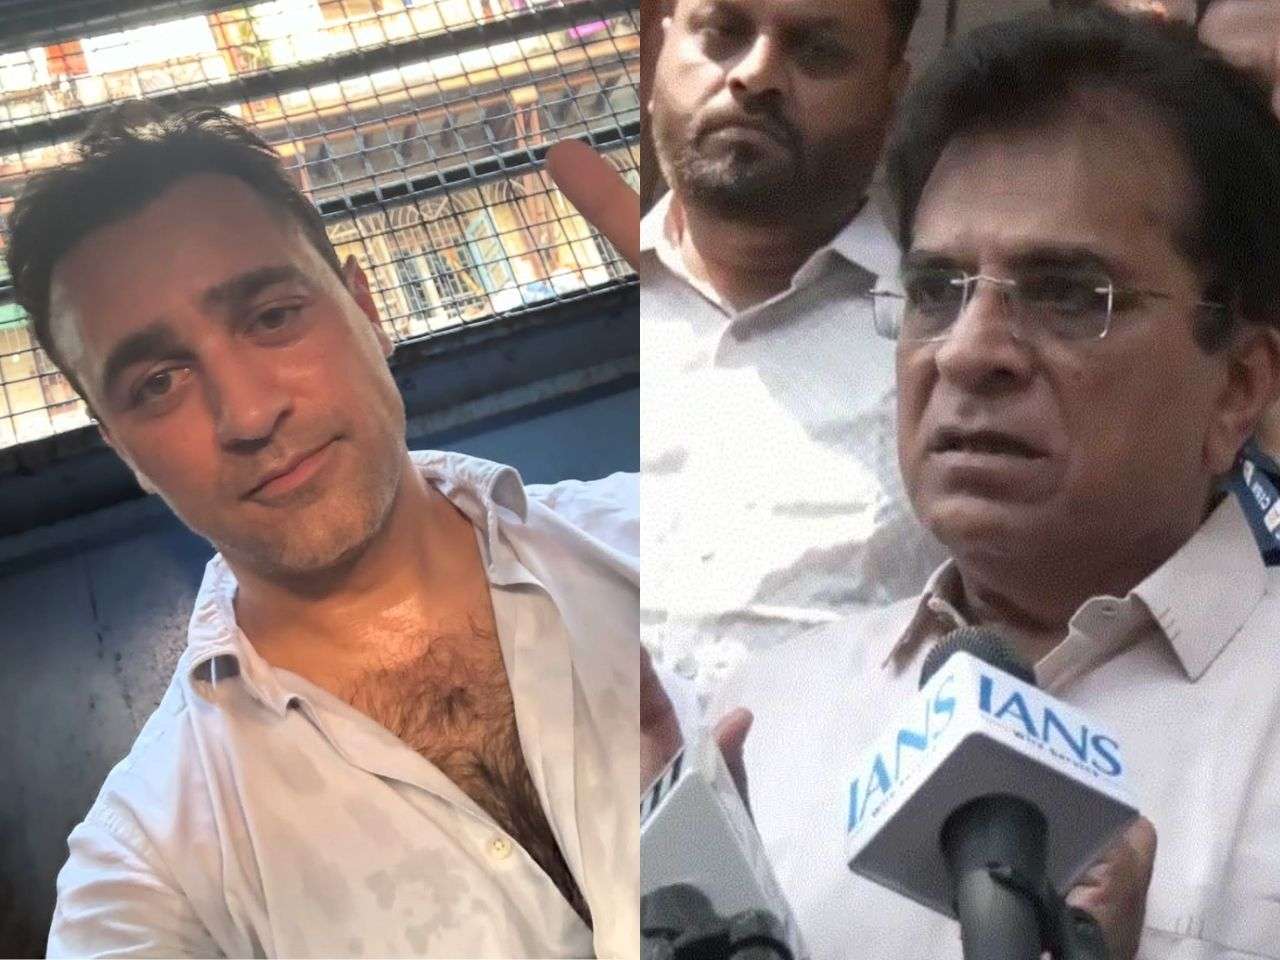 'Imran Khan is attempting to create anarchy': BJP Kirit Somaiya demands immediate arrest of Aamir Khan's nephew, alleges their Pakistani connection
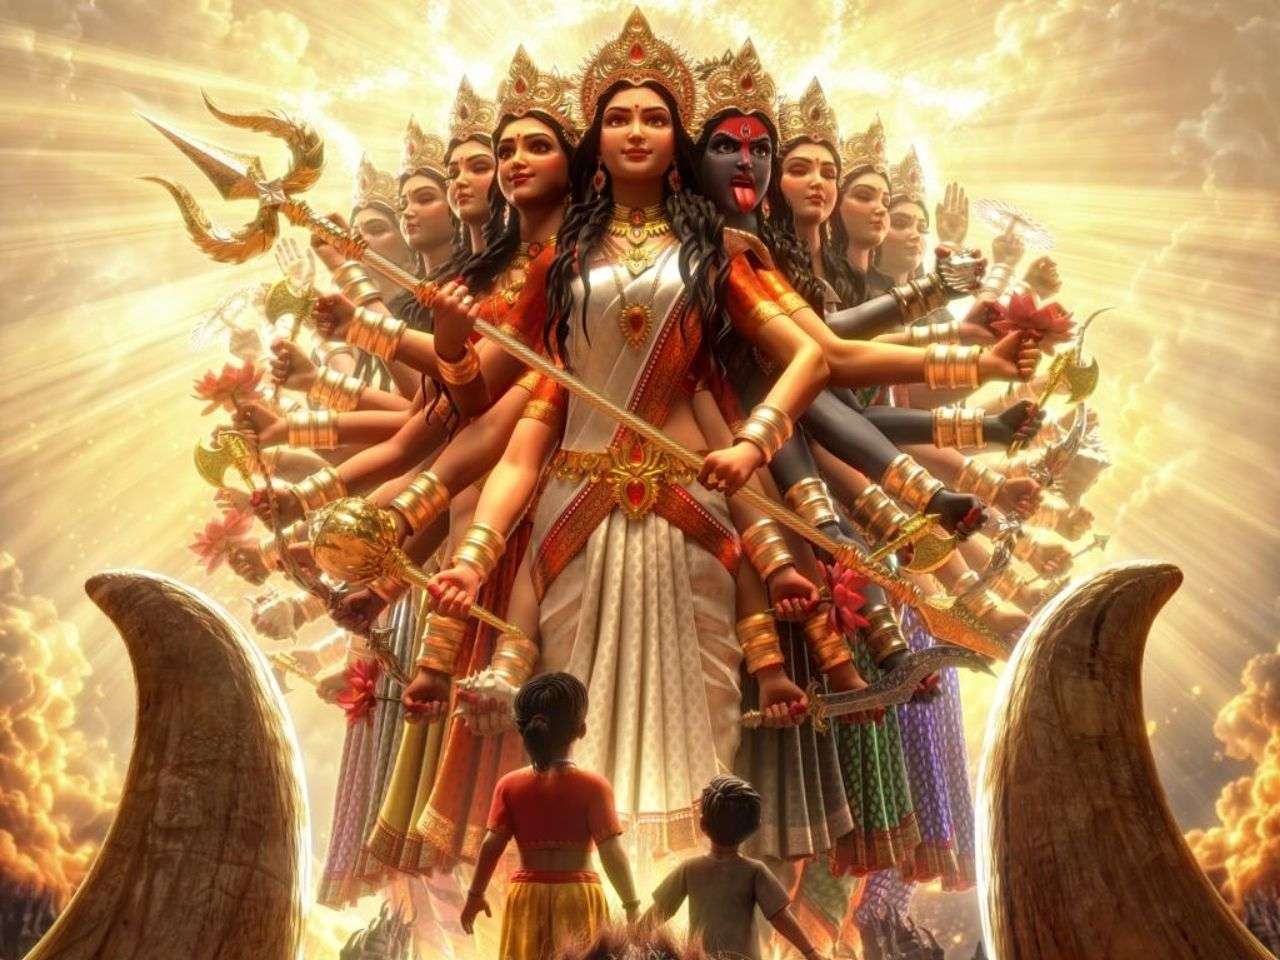 Maha Devi Adishakti trailer: After Mahavatar Narsimha, Maa Durga vs Mahishasura's epic battle gets adapted into 'impressive' animation flick, netizens react
 Koffee with Karan 9: Salman Khan to kickstart Karan Johar's last season of popular chat show, hints juicy reveal: 'Kahi bhi ja sakta hai'
 After Nana Patekar, Marathi cinema suffered another big loss, Madhu Kambikar, veteran Marathi actor, passes away at 73
 Viral video: Mohanlal reviews Ajay Devgn's Drishyam 3, admits he's 'truly impressed' with conclusion, calls it 'so well done'
 CJP Protest: 'Jantar Mantar De-Notified'; Govt Replaces Historic Protest Site With 3 New Venues
 CEC Resignation Row: Rahul Gandhi Announces Supreme Court Plea Over Voter Roll Fraud
 Saudi Houthi War: Saudi Coalition Releases CCTV Of Deadly Houthi Strike On Riyadh Airport
 Saudi Houthi War: India Issues Urgent Advisory To Citizens In Saudi After Riyadh Airport Attack
 CJP Protest: 7,000 CRPF Personnel Rushed To Capital Ahead Of CJP's Oct 10 March
 Retail inflation rises to 5.54% in September: Experts warn of pressure on purchasing power, expect more RBI rate hikes
 Gold, Silver prices today, October 10, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Reliance Jio IPO: Price Band likely at Rs 1065-1119 per share, issue may open on October 21; check details
 How to bypass H-1 B visa restrictions? Can Indian professionals use L-1 and O-1 visas as alternative routes to enter US?
 US Green Card Row: TCS says PERM suspension won't impact business, applications in single digits
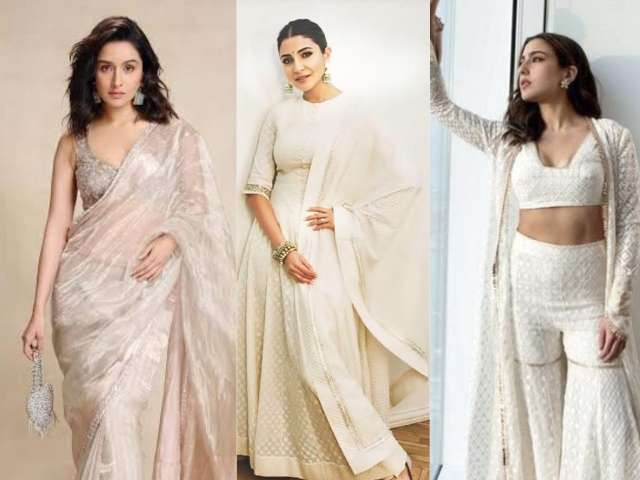 Navratri 2026: From Alia Bhatt to Sara Ali Khan, Shraddha Kapoor, take inspiration from Bollywood actresses to stun everyone in white
 Ranbir Kapoor-Sai Pallavi, Yami Gautam-Addinath Kothare, Rajkummar Rao-Wamiqa Gabbi: 5 fresh on-screen jodis to watch out for in 2026
 OTT Releases This Week (October 5-11): Awarapan 2, Khalifa, Mandaadi; new India movies, shows to watch on Netflix, Prime Video
 OTT Releases This Week (Sept 28 - Oct 4): Dupahiya 2, Pooja Meri Jaan; new movies and shows to watch this Gandhi Jayanti weekend
 From Neeti Mohan, Heer, Sarthak Kalyani; Ahead of Sa Re Ga Ma Pa, 5 musical geniuses championed by AR RahmanWant to protest at Ramlila Maidan? Delhi's new protest cost Rs 1.21 lakh daily, check booking booking details, slots and moreKerala Congress sacks worker for 'irresponsible' CJI post, deletes message after BJP criticismHow BJP government is fighting back as Delhi protest against CEC Gyanesh Kumar deepens?AAP leaders to hold one-day hunger strike against CEC Gyanesh Kumar on Oct 15Supreme Court registry flags 14 defects in INDIA bloc's petition over SIR irregularities: What are they
 Third Language Row: SC extends relaxation to Class 6 students, asks CBSE to grant exemption, here's what it means
 NEET PG 2026 Result Out: Check how to download scorecard from natboard.edu.in; Know category-wise cut-off and more
 Five-year BTech programmes? Ex-IIT director makes proposals amid IIT suicide controversy
 CBSE Date Sheet 2027: When will Class 10, 12 timetable be released? Check details here
 From Rs 150 in 1947 to powerful student body: The story of DUSU’s rise | Explained
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
BUSINESS
While filing the Income Tax Return, never claim false deduction under sections 80C, 80D and other sections as it may create problems because the Income Tax Department can successfully track your expenditures or investments using Artificial Intelligence.

Updated : Jun 18, 2025, 06:42 PM IST

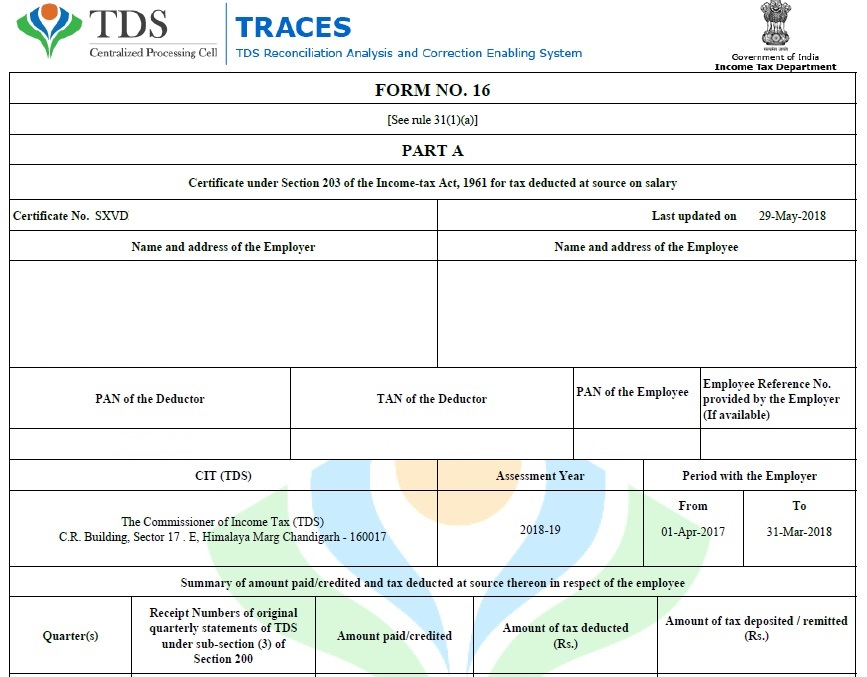
The deadline for filing the Income Tax Return for the Financial Year 2024-25 has been extended to September 15. You have enough time, but you can start early to avoid a last-minute rush and related complications. It has come as a big relief, particularly for those taxpayers who have received their Form 16 by June 15 and are expected to complete the formalities by July 31. Form 16 is a TDS certificate issued by the employer for the following financial year. It is issued after the end of the financial year in which the income was earned.
While filing the Income Tax Return, never claim false deduction under sections 80C, 80D and other sections as it may create problems because the Income Tax Department can successfully track your expenditures or investments using Artificial Intelligence. The Income Tax Department has sent notices to hundreds of thousands of taxpayers in the last three years. Some taxpayers have misused this facilities as there is no need to attach documentary evidence while submitting I-T returns.
However, it may create problems as the Income Tax Department I-T can track and analyse your finance data using Annual Information Statement (AIS) and AI tools. It can send you a notice asking you to furnish proof and explain the discrepancies.
It is important to note that the Income Tax Department has made certain changes in the Income Tax forms and has notified them. It notified ITR forms for FY 2024-25 (Assessment Year 2025-26) last month, incorporating the changes announced in Union Budget 2024-25.
Salaried individual taxpayers with less complicated tax information should opt for ITR-1, which is a simple form with pre-filled details. It is for those taxpayers, who have a total annual income of Rs 50 lakh or less, which can include salary, pension, interest, dividend, and agricultural income of up to Rs 5,000.

ITR-2 is for those taxpayers, who have no income under the head ‘profits and gains from business or profession’. In other words, the salaried individuals who are not eligible to use ITR-1 should choose ITR-2.
ITR-3 is for those people who go for stock trading activities like intra-day or F&O trading, these activities will be treated as business income. Besides, ITR-3 should also be chosen by those Individuals and Hindu Undivided Families (HUF) who have income under the head ‘profits and gains of business or profession.