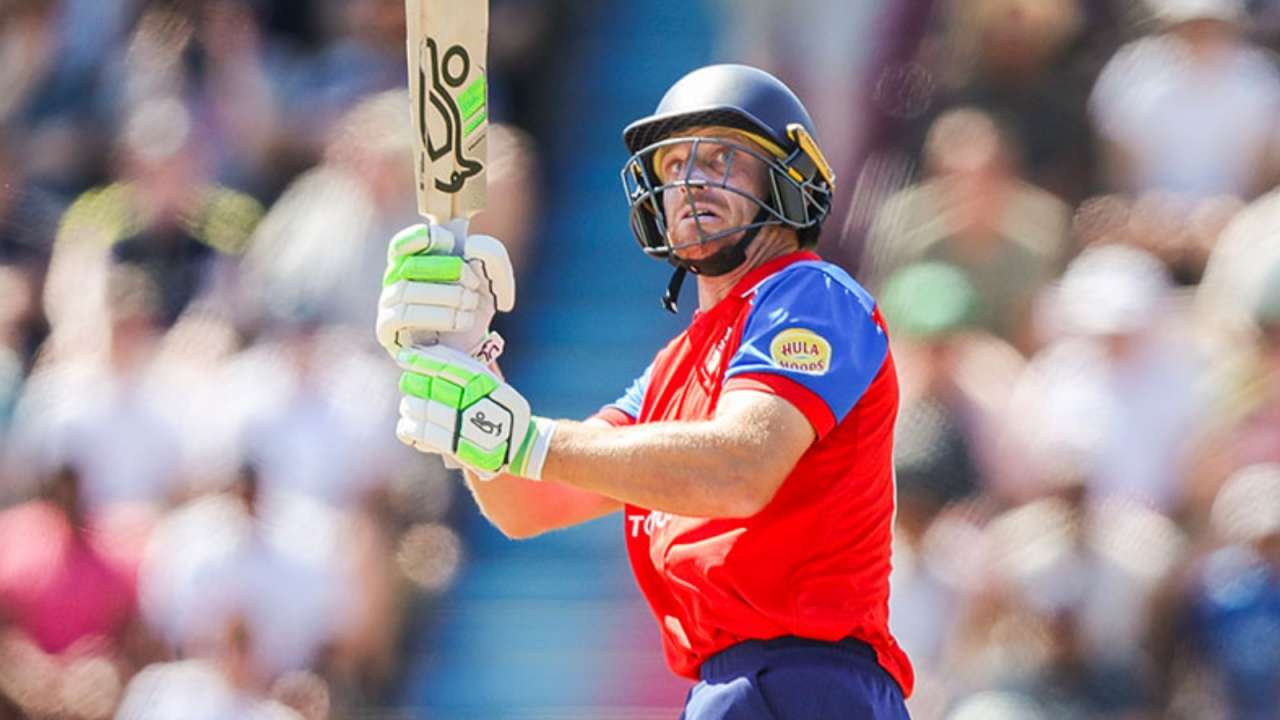
 Jos Buttler surpasses ex-India captain to become second-highest run-scorer in T20I history
 Salman Khan teases Varun Sharma during Ganpati Visarjan, video goes viral: 'Aur kitna wish...' | Watch
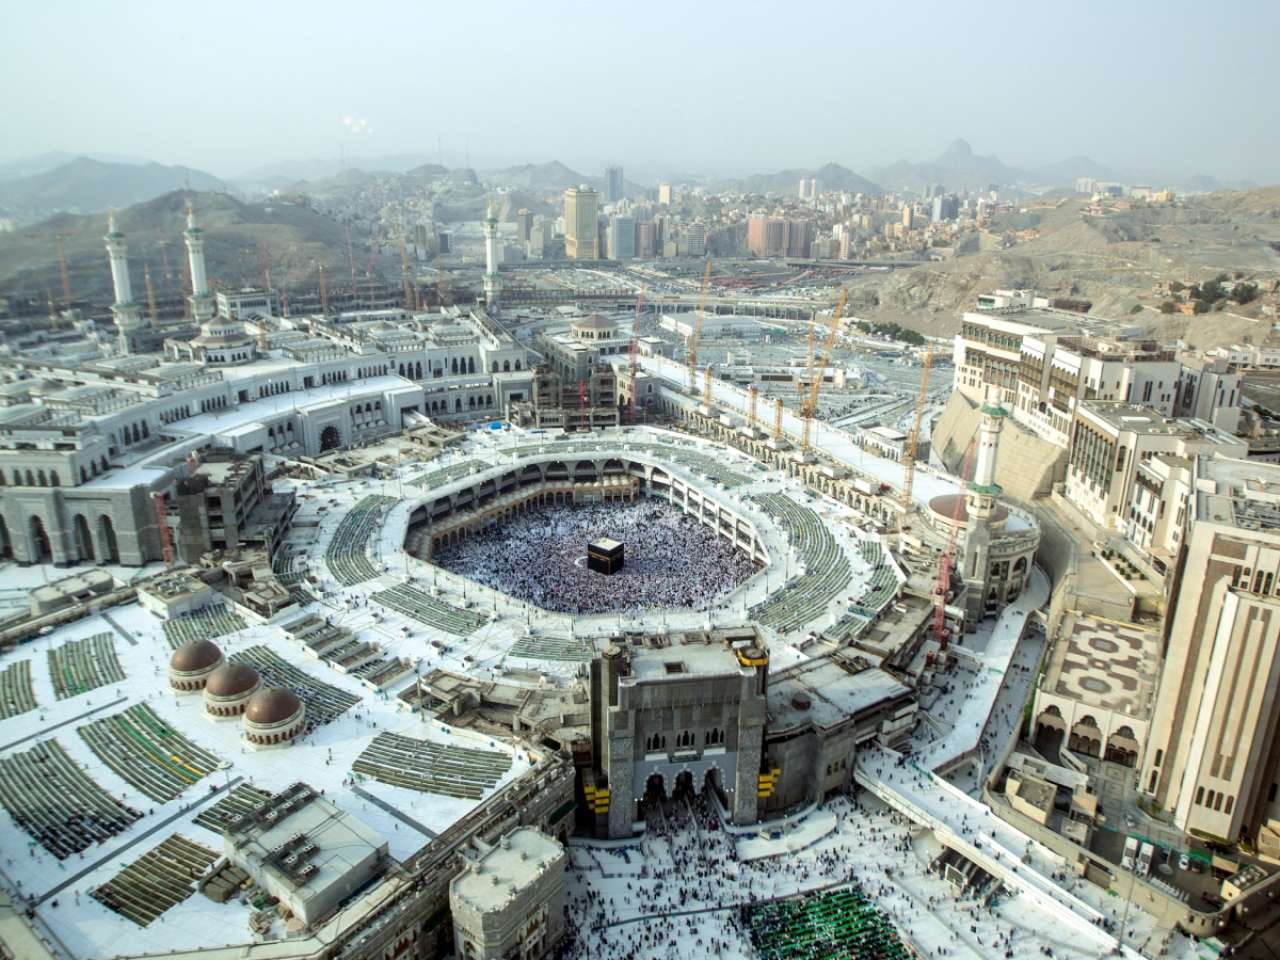 Saudi Arabia issues first-ever air raid alert in holy city of Mecca amid Houthi attacks
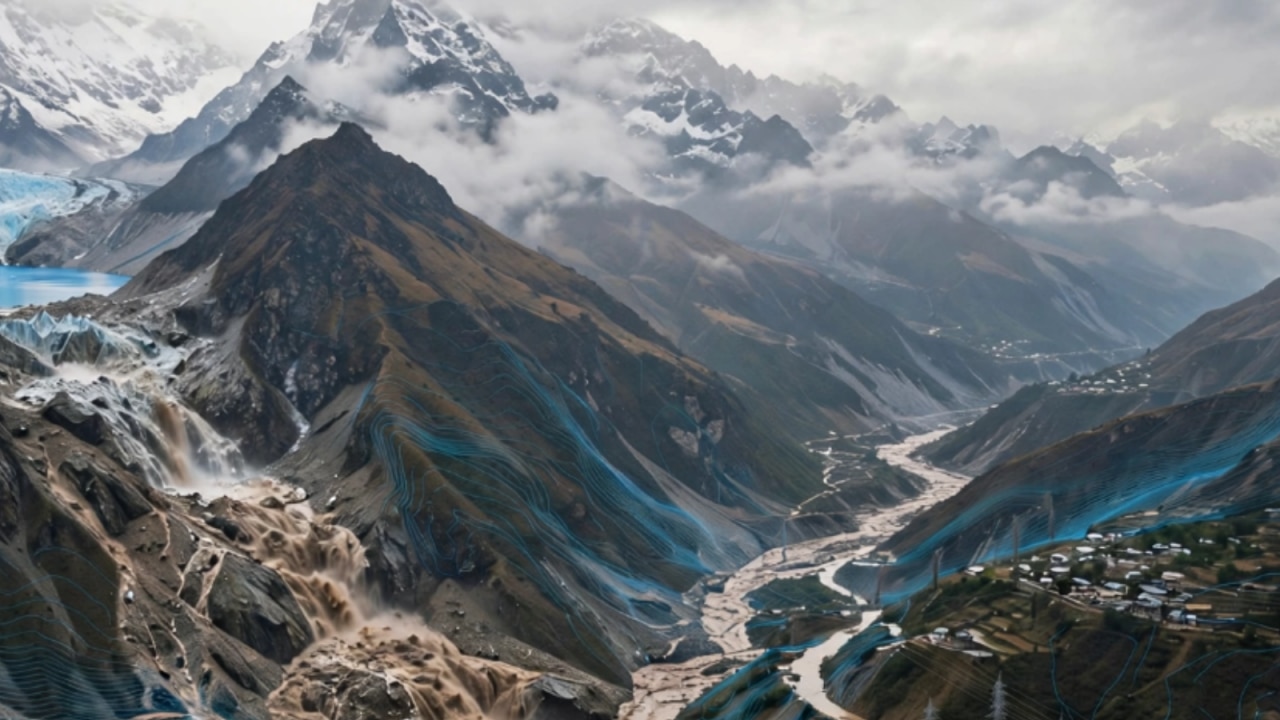 GLOF, Flash Flood Risk in Indian Himalayas: What has India actually fixed, and what remains exposed?
 CM Vijay’s London event cancelled after hundreds gather at venueJos Buttler surpasses ex-India captain to become second-highest run-scorer in T20I history
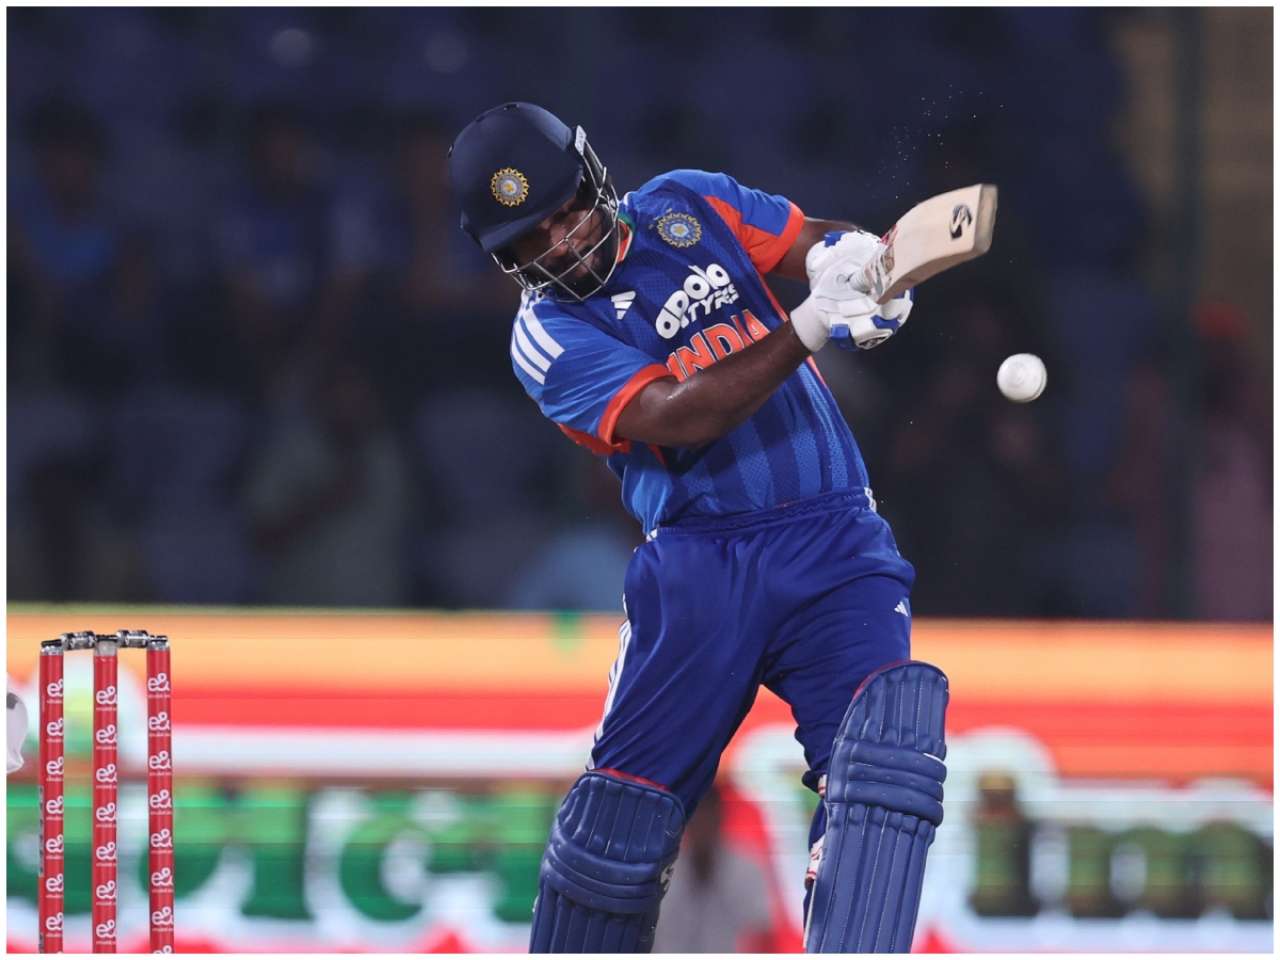 India vs Afghanistan, 2nd T20I: Sanju Samson answers critics with six-hitting show, seals series win
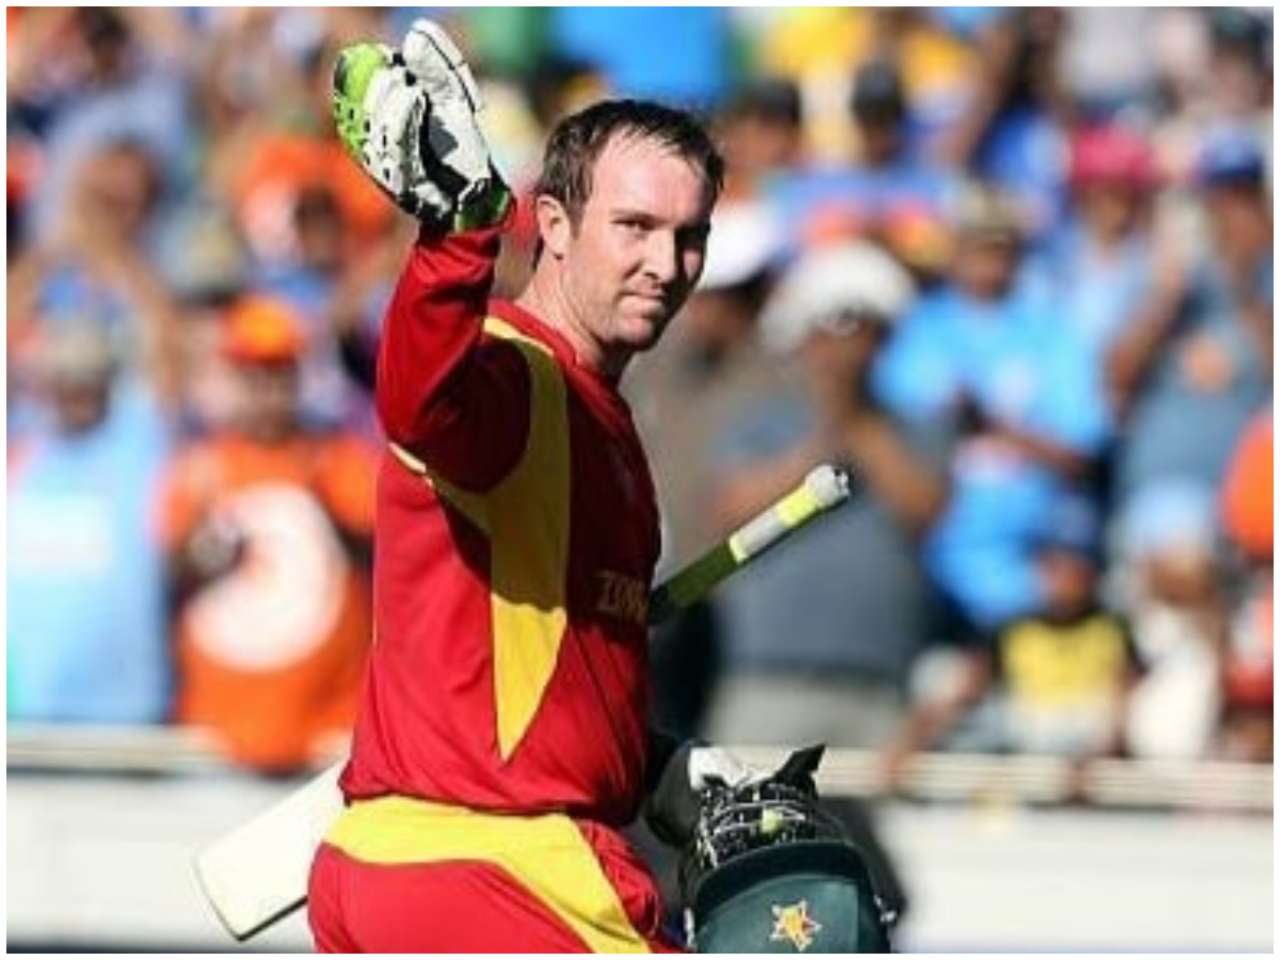 Sachin Tendulkar’s long-standing ODI record finally falls, Zimbabwe star makes history
 Vaibhav Sooryavanshi misses out again: Why is India not picking the teen sensation?
 Did MEA play a role in India’s Asia Cup trophy decision? Ministry clarifiesSalman Khan teases Varun Sharma during Ganpati Visarjan, video goes viral: 'Aur kitna wish...' | Watch
 ‘They’re repeating’: Jiah Khan’s mother reacts to Sooraj Pancholi’s name in Disha Salian case
 Bigg Boss 20: ScoutOp slammed for ‘threatening’ Arishfa Khan, telling gaming community ‘khatam kar do ise’ on national TV| VIDEO
 How does Shah Rukh Khan and his family celebrate Ganesh Chaturthi? King actor shares details
 Salman Khan praises The Revolutionaries after watching Prime Video OTT show with Bhuvan Bam and Nikkhil Advani
 Gurugram News: Woman Biker Questions Driver’s Decision To Flee Says, 'Could Have Died'
 US Iran War: '7000 Foot Hike With Broken Bones' US Fighters 50 Hour Iran Survival Story
 Gurugram Hit-And-Run: Kalyan Bainsla Identified As Driver Who Rammed Woman Biker
 Houthi Attack Saudi Arabia: Houthis Snatch Key Red Sea Gateway Mocha; Big Shock For Saudi | US-Iran
 BRICS Summit 2026: India To Push BRICS Digital Currency Link Despite Political & Technical Hurdles
 Gold, silver prices today, September 16, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 UPI payments up to Rs 2000 to remain charge-free: What Centre’s new rule says
 Gold, silver prices today, September 15, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Gold, silver prices today, September 13, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Bernard Arnault out of world's top 10 richest list for first time since 2017, net worth falls to USD 143 billion
 MS Dhoni to Virat Kohli: Indian cricket stars turn back time in viral 80s AI photo trend
 Bigg Boss 20: From Mary Kom, Mahhi Vij to Isha Rekhi, Qazi Touqeer, Rhiti Tiwari, Gullu; final confirmed list of contestants
 From Suhana Khan to Rasha Thadani, Ananya Panday: Gen-Z actresses acing modern-day Radha look in Janmashtami
 Teacher's Day 2026: From Thalapathy Vijay to Jyothika, 5 popular on-screen gurus from South that became household names
 OTT Releases This Week: Dhamaal 4, Gandhari, DC, Bigg Boss 20; Indian movies, series to watch on Netflix, JioHotstar, ZEE5CM Vijay’s London event cancelled after hundreds gather at venue
 India has extended two invitations to Bangladesh PM Tarique Rahman: MEA
 Yamuna will be cleaned by 2029, says Union Home Minister Amit Shah
 Delhi-bound IndiGo flight, carrying 103 passengers, diverted to Lucknow after midair smoke warning
 Gurugram Hit-And-Run Case: Accused Kalyan Bainsla tried to flee from Police custody citing 'toilet break', suffered injuries during chase
 NEET PG 2026 Answer Key: Check expected date, step-by-step guide to download response sheet at nbe.edu.in here
 UGC NET: NOIDA protest accused cracks exam, scores 99.3 percentile, says how made preparations in jail
 NEET PG Exam 2026: When will answer keys be released, how to access? Know here
 Teachers’ Day 2026: Heartfelt wishes, messages to make your favourite teacher feel special
 Who is Gyanendra Kumar Gangwar, IAS officer arrested in KPSC exam irregularities case?
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
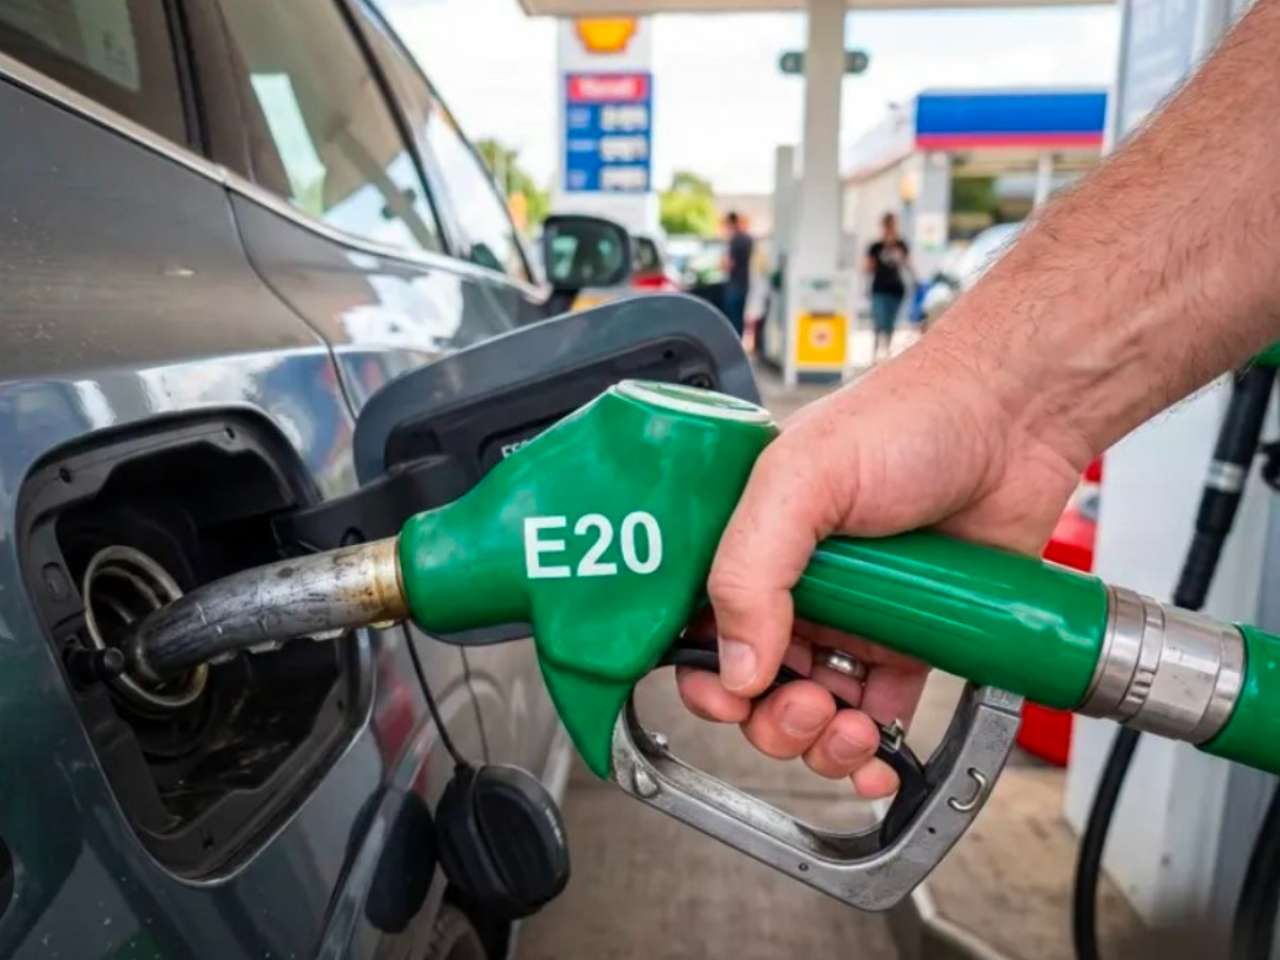 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
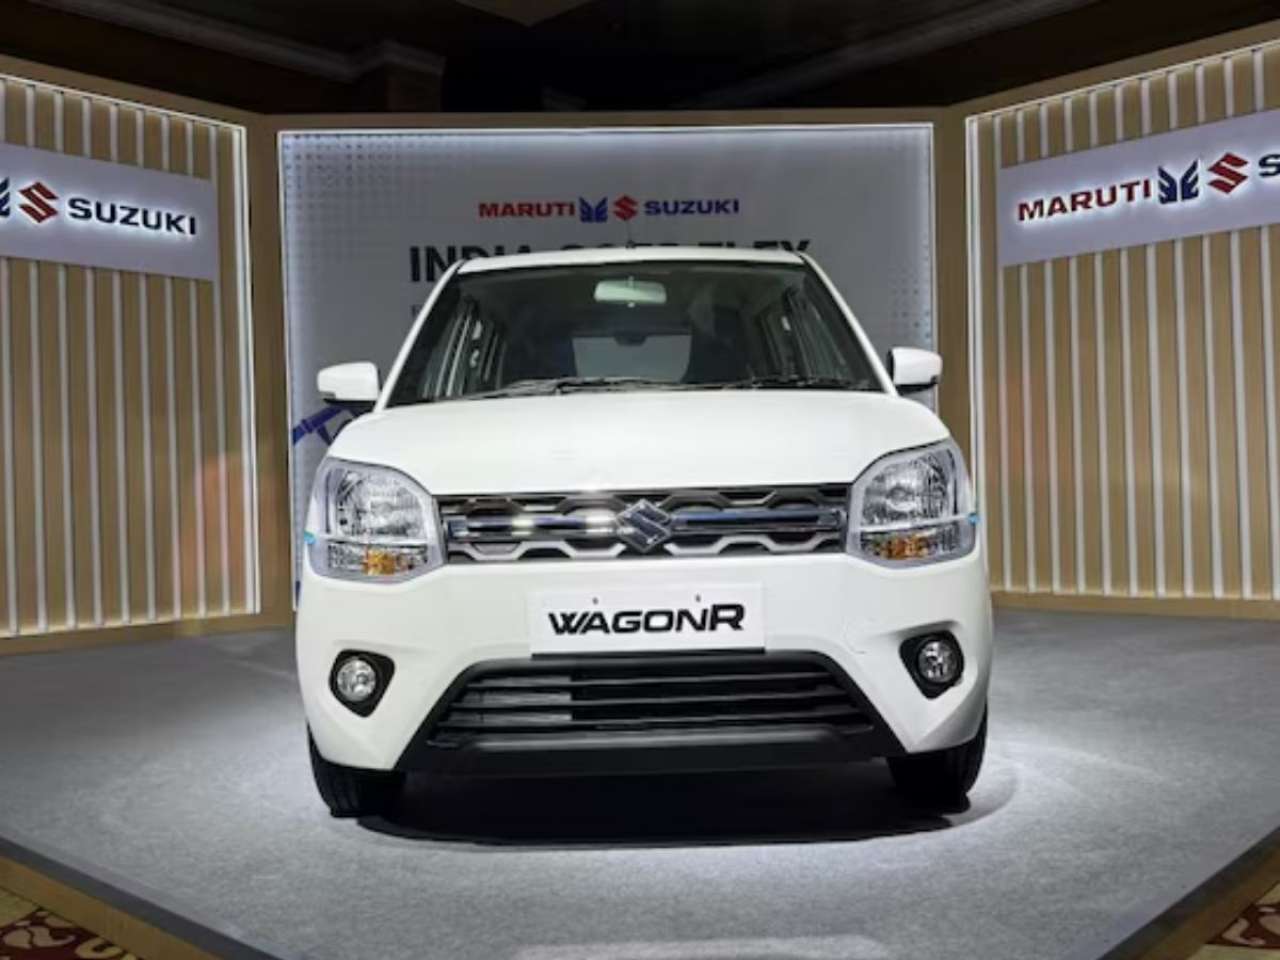 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
BUSINESS
The bad performance battered the shares of the bank, which closed 7.77% lower than the previous day's close

Updated : May 19, 2017, 07:45 AM IST


IDBI Bank's huge concentration of loans to troubled sectors like power and iron and steel sectors continued to plunge the bank into deep losses.
For the quarter ended March 31, 2017, the bank reported a loss of Rs 3,199.76 crore and if it was not for a tax writeback of Rs 1620.02 crore the losses would have been higher. The bad performance battered the shares of the bank, which closed 7.77% lower than the previous day's close.
Gross non-performing assets (NPAs) soared 80% to Rs 44,752.59 crore at the end of the March quarter from Rs 24,875.07 crore a year ago. The bank reported gross NPA of Rs 35,245.33 crore a quarter ago. Provisions jumped 39.54% to Rs 6,209.58 crore from Rs 4,450.15 crore year on year.
The only silver lining is the positive growth both in the net interest income (NII) and the Net Interest margin (NIM). The growth in the NII which is the core income of the bank grew 14.44% to Rs 1,633.29 crore from Rs 1,427.24 crore in the year-ago period. NIM for the full year climbed eight basis points to 1.75 % during the quarter. However, the other income which includes fees or the non-core income of the bank declined 21.17% to Rs 1,061.52.
Rating agency S&P said in a release, "We expect earnings to remain weak over the next 12-18 months, largely because of IDBI's high credit costs (given its weak asset quality and low reserve coverage) and low net interest margins (NIMs)."
IDBI Bank's performance has been weak over the past two years with stressed asset quality and high credit costs straining its earnings. Its NPLs spiked to 21.3% as of March 31, 2017, from 15.2% in the previous quarter. The bank reported a loss of Rs 5,070 crore for full fiscal 2017.
S&P said the Prompt Corrective Action (PCA) by the Reserve Bank of India will entail the latter's frequent and focused monitoring of IDBI, as well as restrictions on distributing dividends, expanding its branch network, or undertaking any major capital expenditures.
PCA may accelerate capital conservation by shedding high-risk assets and reducing the concentration of loans to high-risk sectors. PCA may also be accompanied by asset quality reviews, which could lead to broader recognition of weak loans, accelerated provisioning and a tighter loan-review mechanism.