 Drishyam 3 box office collection Day 6: Despite minor drop, Ajay Devgn earns his biggest hit, beats Tanhaji, earns over Rs 350 crore
 Gyanesh Kumar row: Congress declares October 8 ‘Black Day’ after Rahul, Priyanka detention
 India squad for New Zealand tour delayed: Why selectors are waiting until next week to pick ODI team
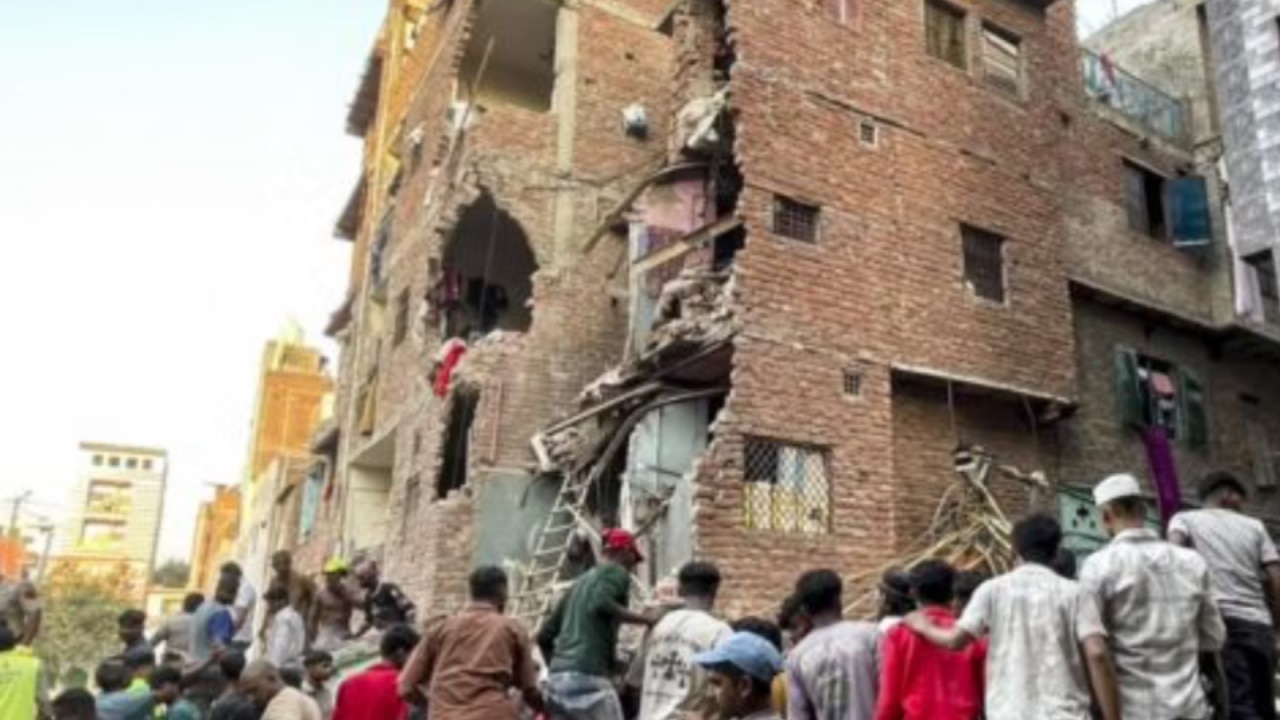 Delhi Building Collapse: Death toll rises to 3, several injured after collapse in New Seemapuri
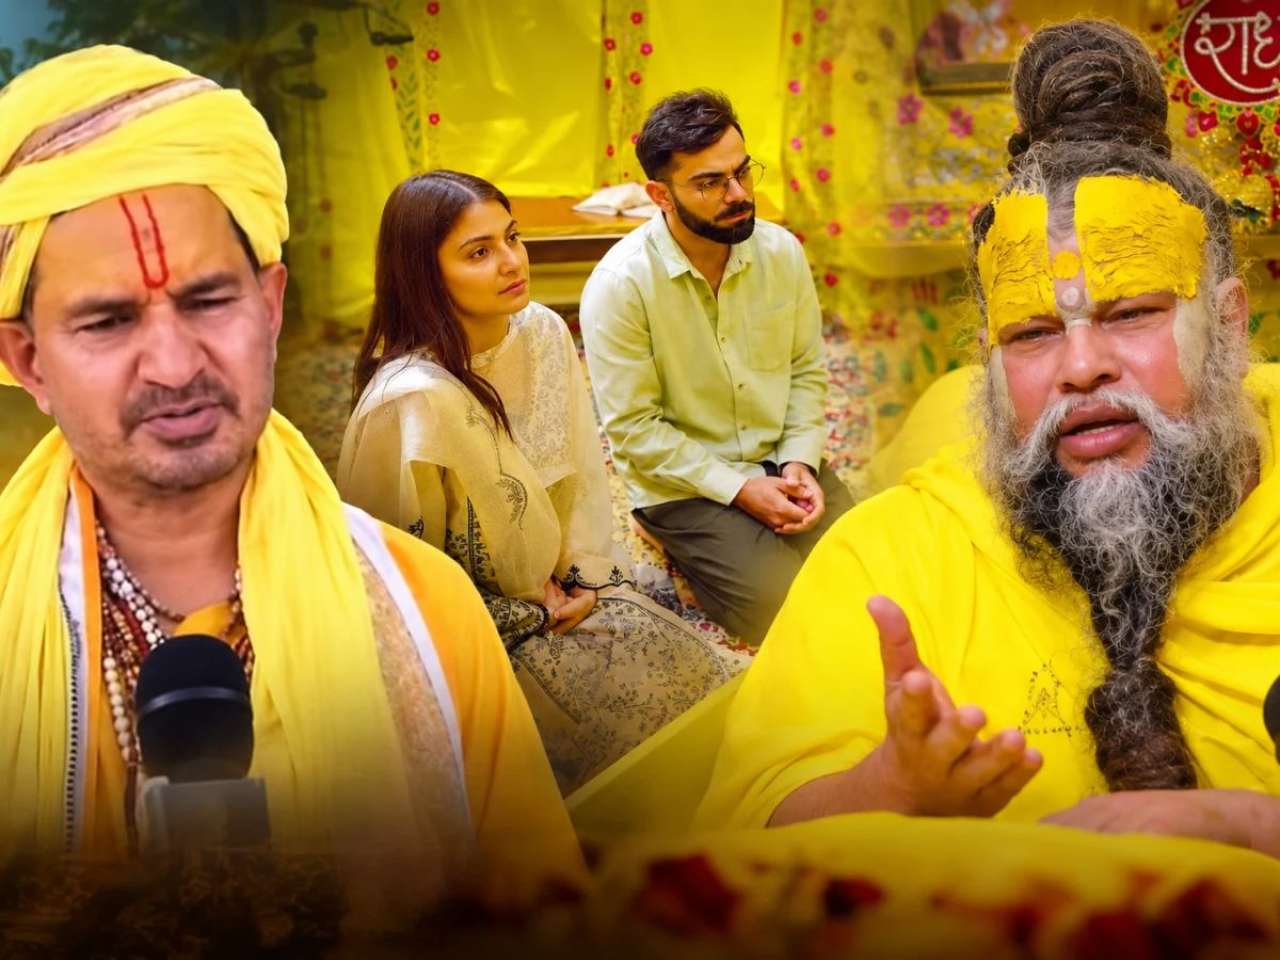 Virat Kohli–Premanand Maharaj Rs 5 crore row escalates: Dinesh Falahari fires back, demands audit of company accountsIndia squad for New Zealand tour delayed: Why selectors are waiting until next week to pick ODI teamVirat Kohli–Premanand Maharaj Rs 5 crore row escalates: Dinesh Falahari fires back, demands audit of company accounts
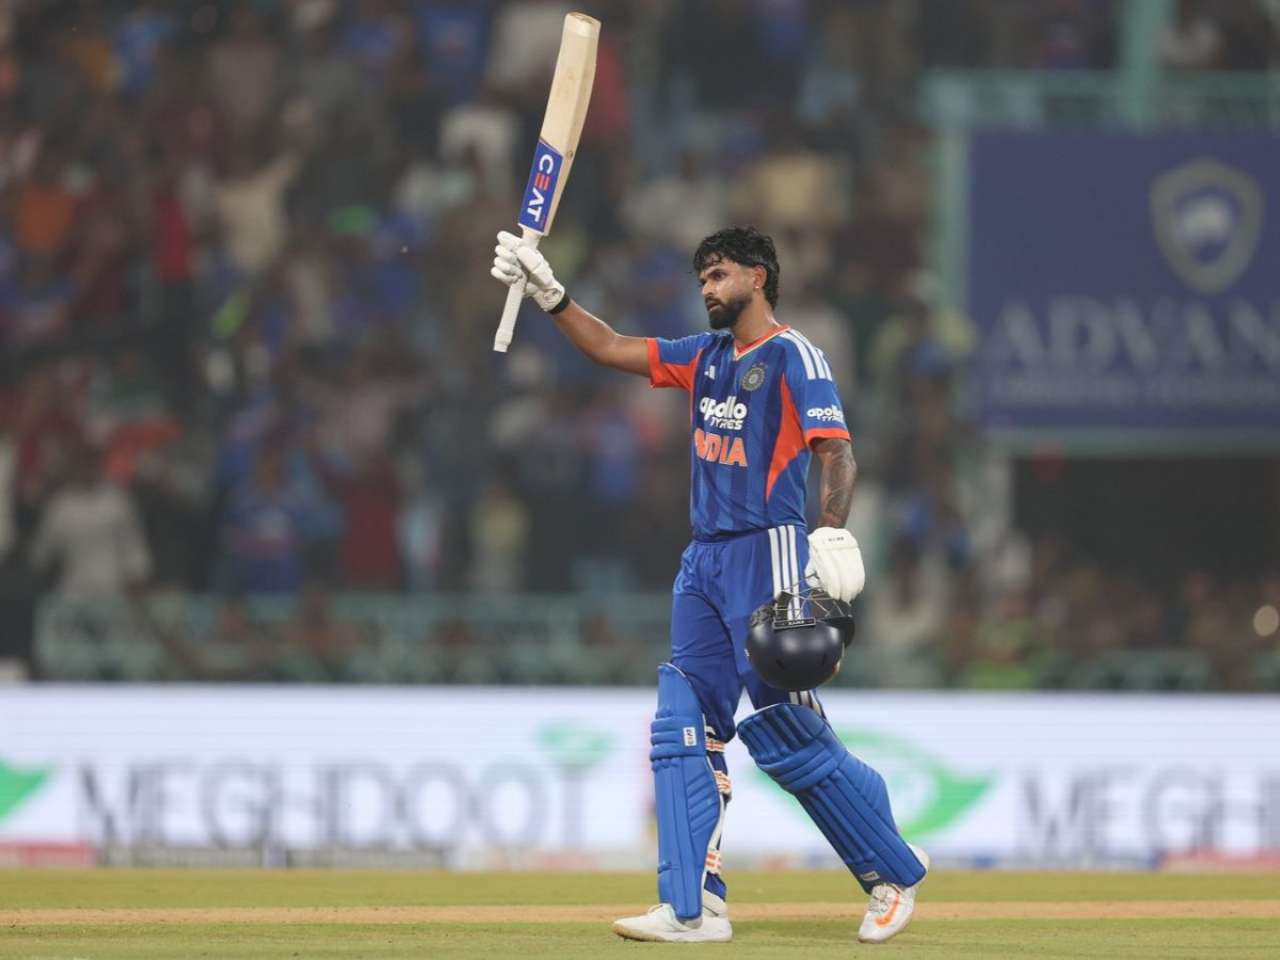 ICC Rankings: Shreyas Iyer soars to No. 7 in T20Is, KL Rahul gains while Virat Kohli displaced to 3rd in ODIs
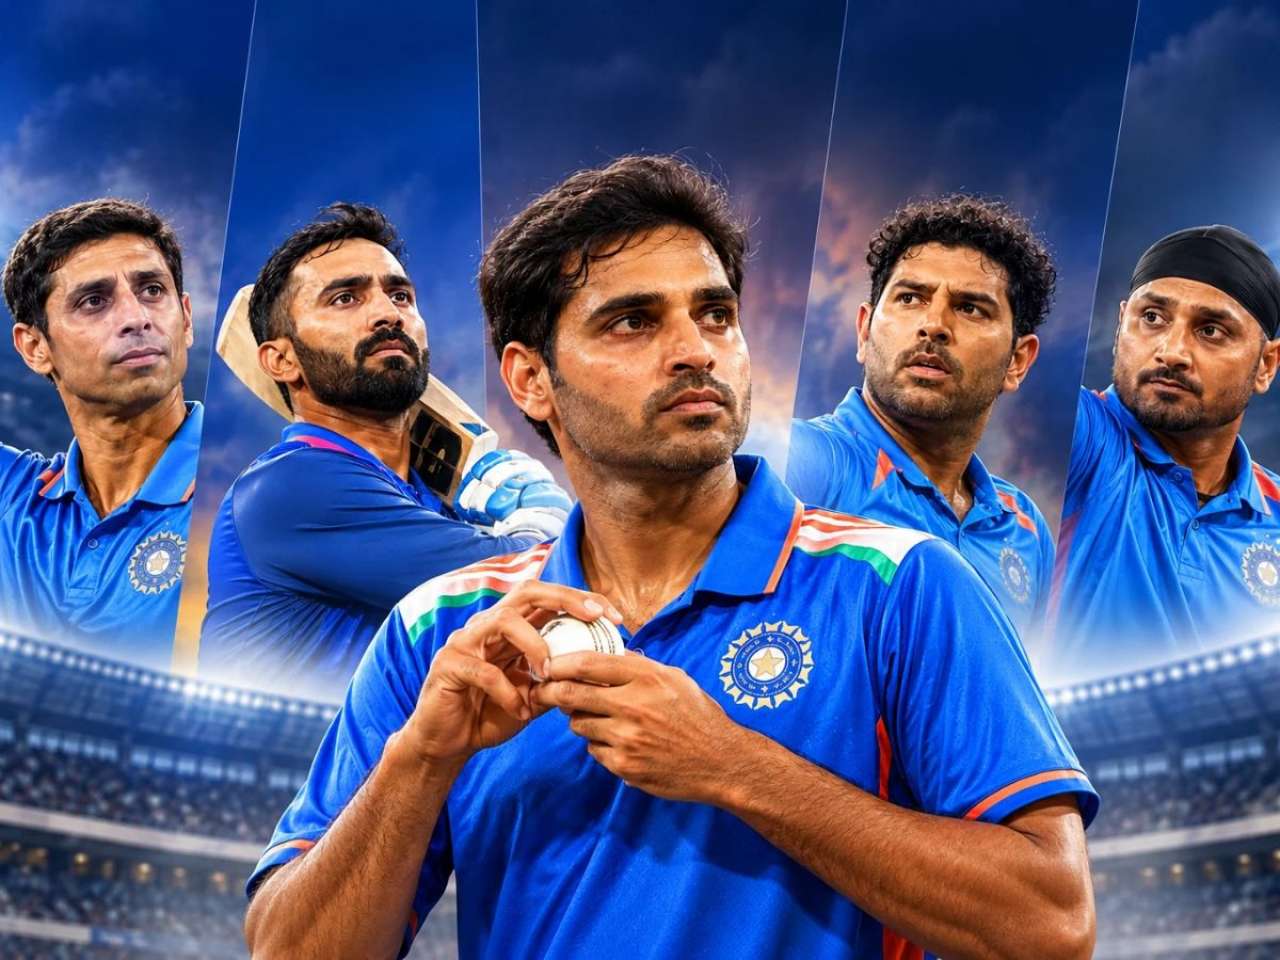 Bhuvneshwar Kumar back in Indian team after 4 years: How past veterans responded to T20I comebacks
 Can Sourav Ganguly coach Delhi Capitals while heading CAB? Former BCCI boss responds to big controversyDrishyam 3 box office collection Day 6: Despite minor drop, Ajay Devgn earns his biggest hit, beats Tanhaji, earns over Rs 350 crore
 Jailer 2: CBFC rating, runtime revealed, bad news for Rajinikanth fans, his latest film isn't suitable for...
 Kangana Ranaut's first reaction on PM Modi completing 25 years as head of government
 Rajpal Yadav cheque-bounce case: Actor gets 'major relief' from Supreme Court, gets final opportunity of two weeks: 'Loans aren't taken out for...'
 Ramayana in trouble month before release, Ranbir Kapoor, Yash film's production hit major hurdle as producer Namit Malhotra....
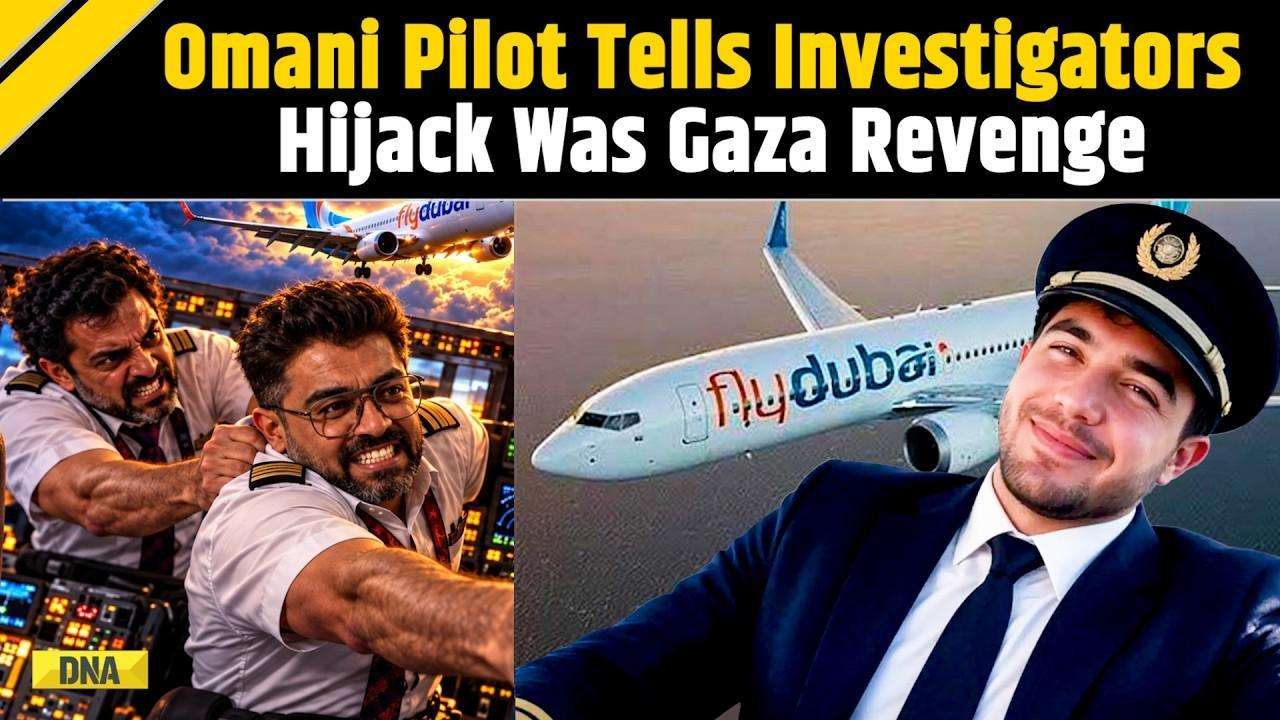
 Flydubai Flight News:'Revenge For Gaza'; Flydubai Co-Pilot Hamam Al-Hammami Confesses To Terror Plot
 Delhi Building Collapse: 5-Storey Building Collapses In Seemapuri; Emergency Teams Rush To Spot
 PM Modi News: Congress Attacks Modi Over Repo Rate Hike, Says ‘Achhe Din’ Became ‘Vasooli Wale Din’
 CJP News: CJP Announces ‘Chappal Protest’ in Bengaluru On October 8 | CEC Gyanesh Kumar Resignation
 Flydubai Attack: Israeli Dentist Reveals How He Helped Save Captain Smit After Flydubai Attack
 Rupee slips despite RBI rate hike: Why is the Indian currency under pressure against US dollar?Rupee slips despite RBI rate hike: Why is the Indian currency under pressure against US dollar?
 Your loan EMIs are about to rise: RBI hikes interest rates by 0.25%
 GST Council October 8 meeting: No rate changes expected; reforms on refunds, ITC and registration on agenda
 Cabinet approves Rs 10,000 crore SME Growth Fund: What it means for small businesses
 OTT Releases This Week (Sept 28 - Oct 4): Dupahiya 2, Pooja Meri Jaan; new movies and shows to watch this Gandhi Jayanti weekend
 From Neeti Mohan, Heer, Sarthak Kalyani; Ahead of Sa Re Ga Ma Pa, 5 musical geniuses championed by AR Rahman
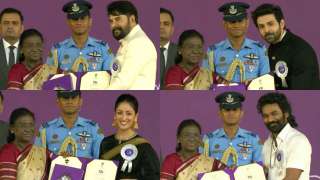
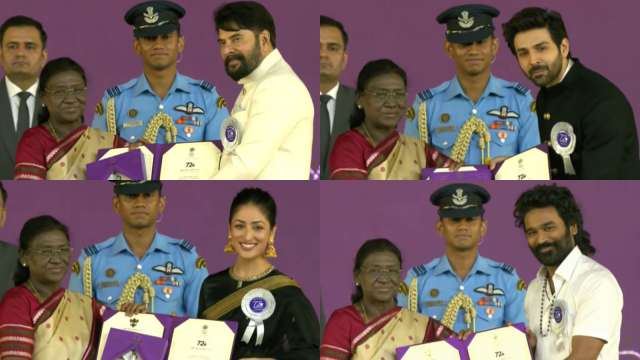 72nd National Film Awards 2024: Kartik Aaryan, Yami Gautam, Aditya Dhar, Mammootty, Dhanush, Anant Nag accept honours
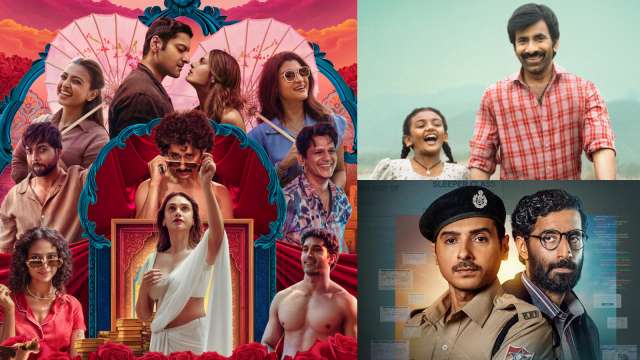 OTT Releases This Week (September 14-20): Lust Stories 3, Irumudi, Thudakkam; Indian movies, series to watch on Netflix, Prime Video, JioHotstar
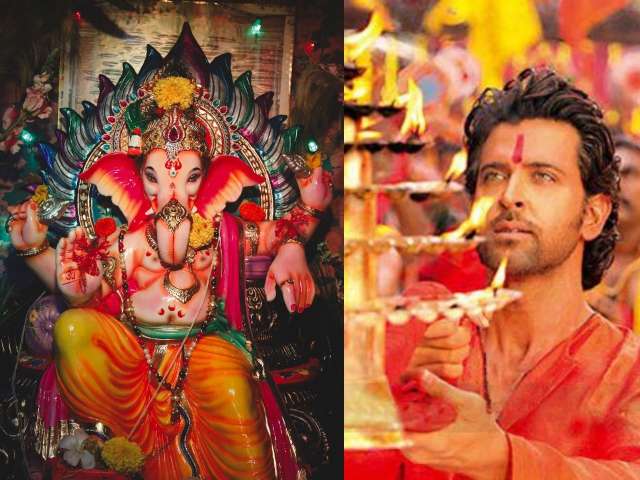 Ganesh Utsav 2026: Deva Shree Ganesha, Sindoor Lal Chadayo; 5 iconic Ganpati songs that should be must-haves in your playlistGyanesh Kumar row: Congress declares October 8 ‘Black Day’ after Rahul, Priyanka detentionDelhi Building Collapse: Death toll rises to 3, several injured after collapse in New Seemapuri
 CJI Surya Kant to attend NLSIU Bengaluru convocation on Oct 17 after cancellation row
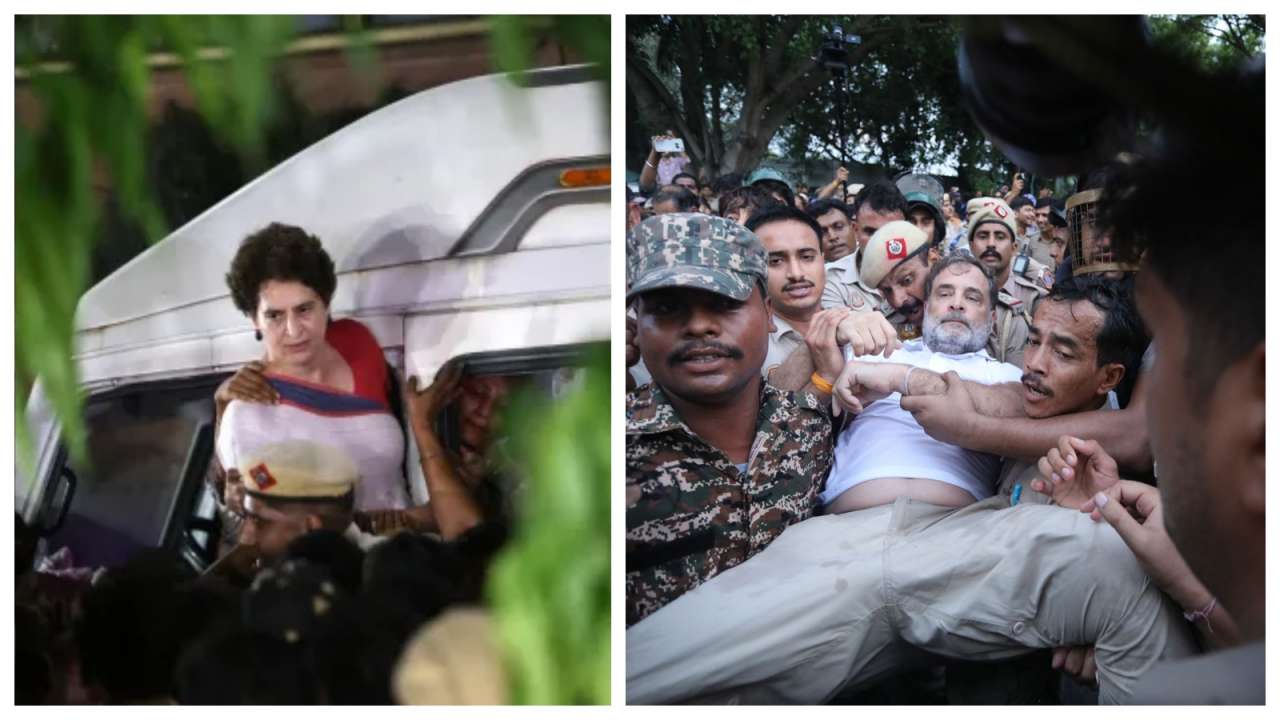 Protest Against CEC Gyanesh Kumar: Rahul Gandhi, Priyanka released after two hours of detention
 Building collapses in Delhi again! After Satya Niketan, many residents feared trapped under debris at Seemapuri
 Third Language Row: SC extends relaxation to Class 6 students, asks CBSE to grant exemption, here's what it means
 NEET PG 2026 Result Out: Check how to download scorecard from natboard.edu.in; Know category-wise cut-off and more
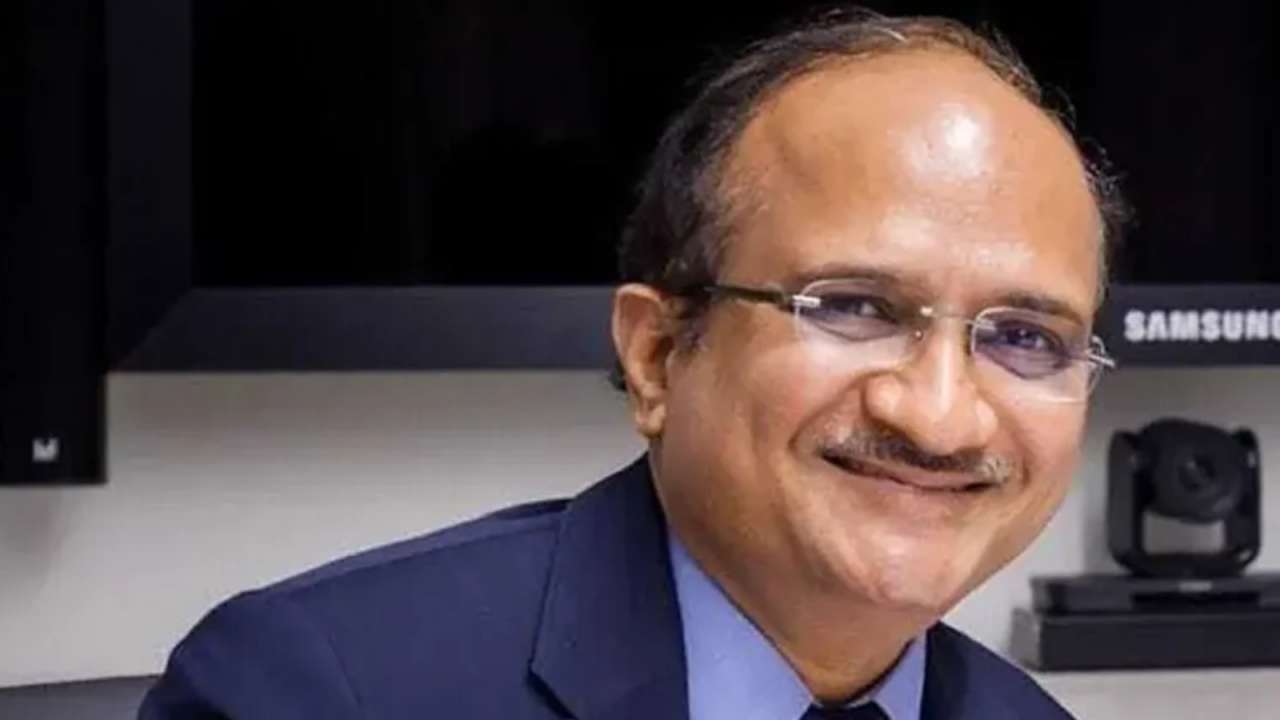 Five-year BTech programmes? Ex-IIT director makes proposals amid IIT suicide controversy
 CBSE Date Sheet 2027: When will Class 10, 12 timetable be released? Check details here
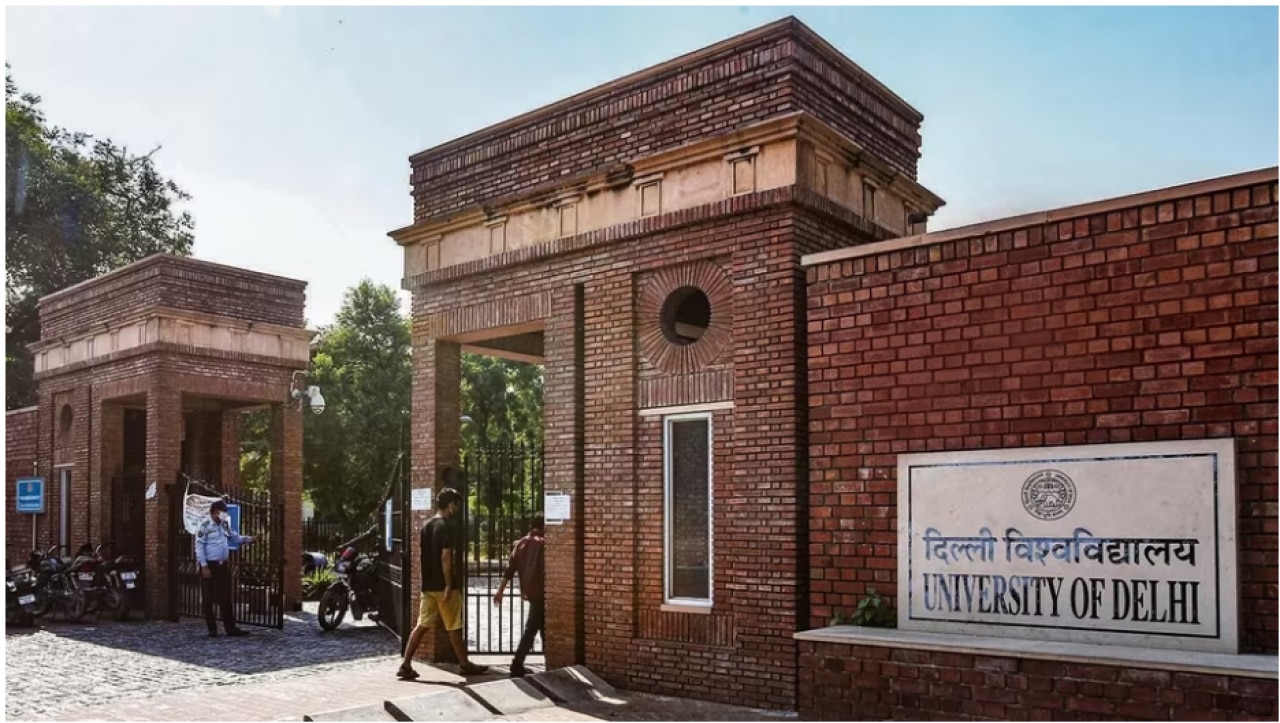 From Rs 150 in 1947 to powerful student body: The story of DUSU’s rise | Explained
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
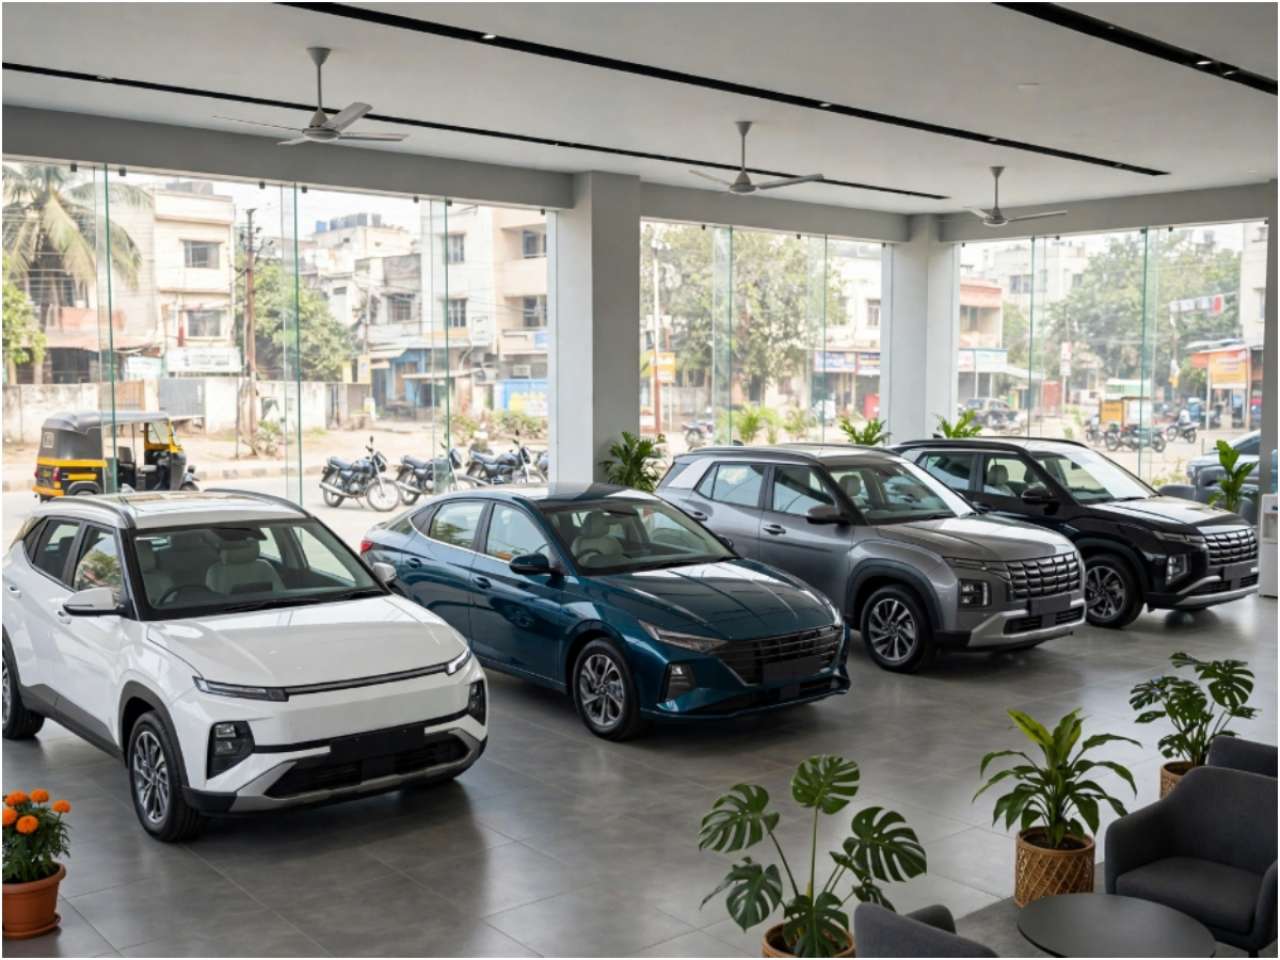 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
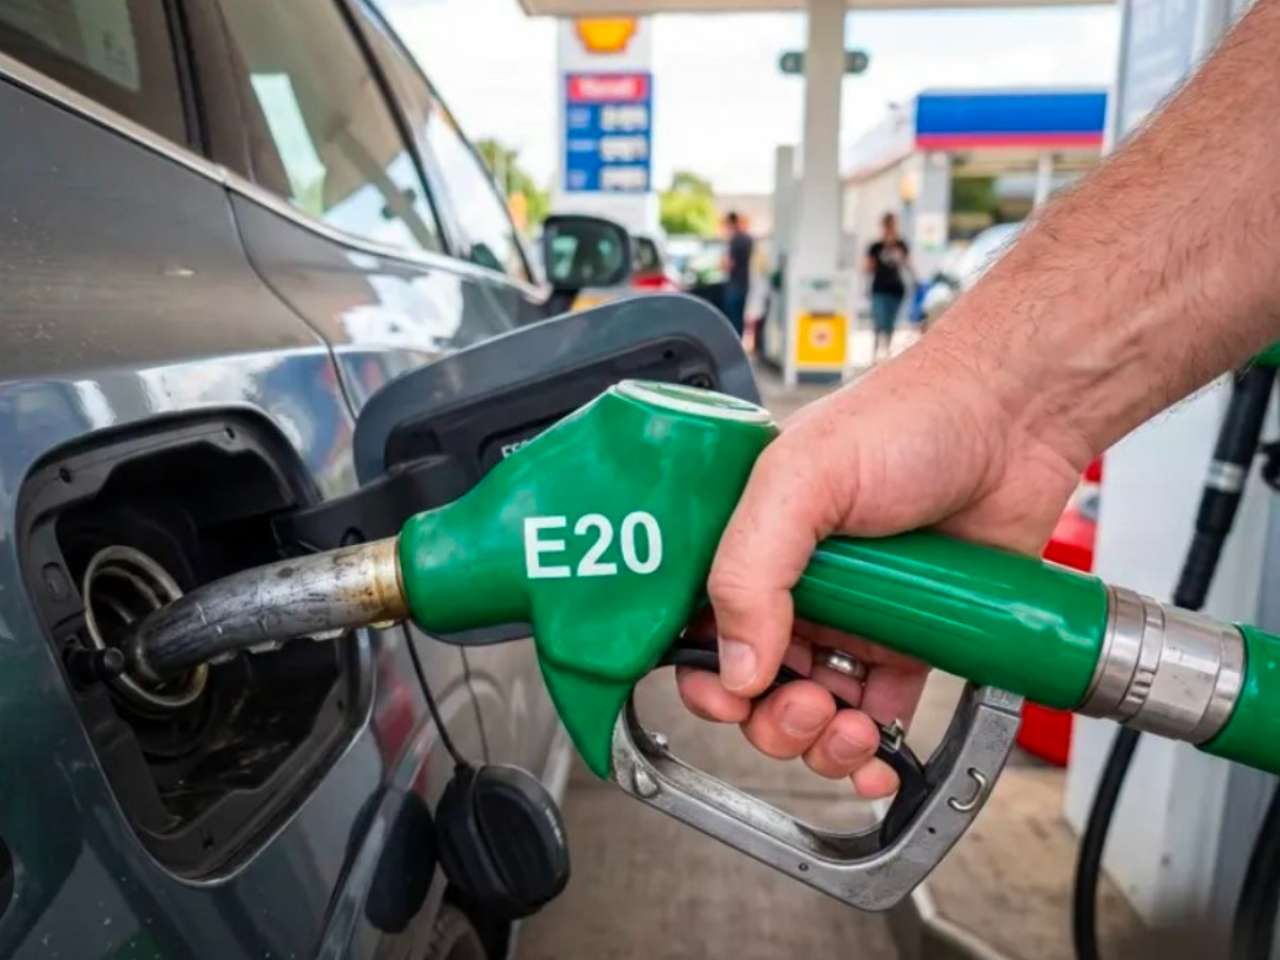 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
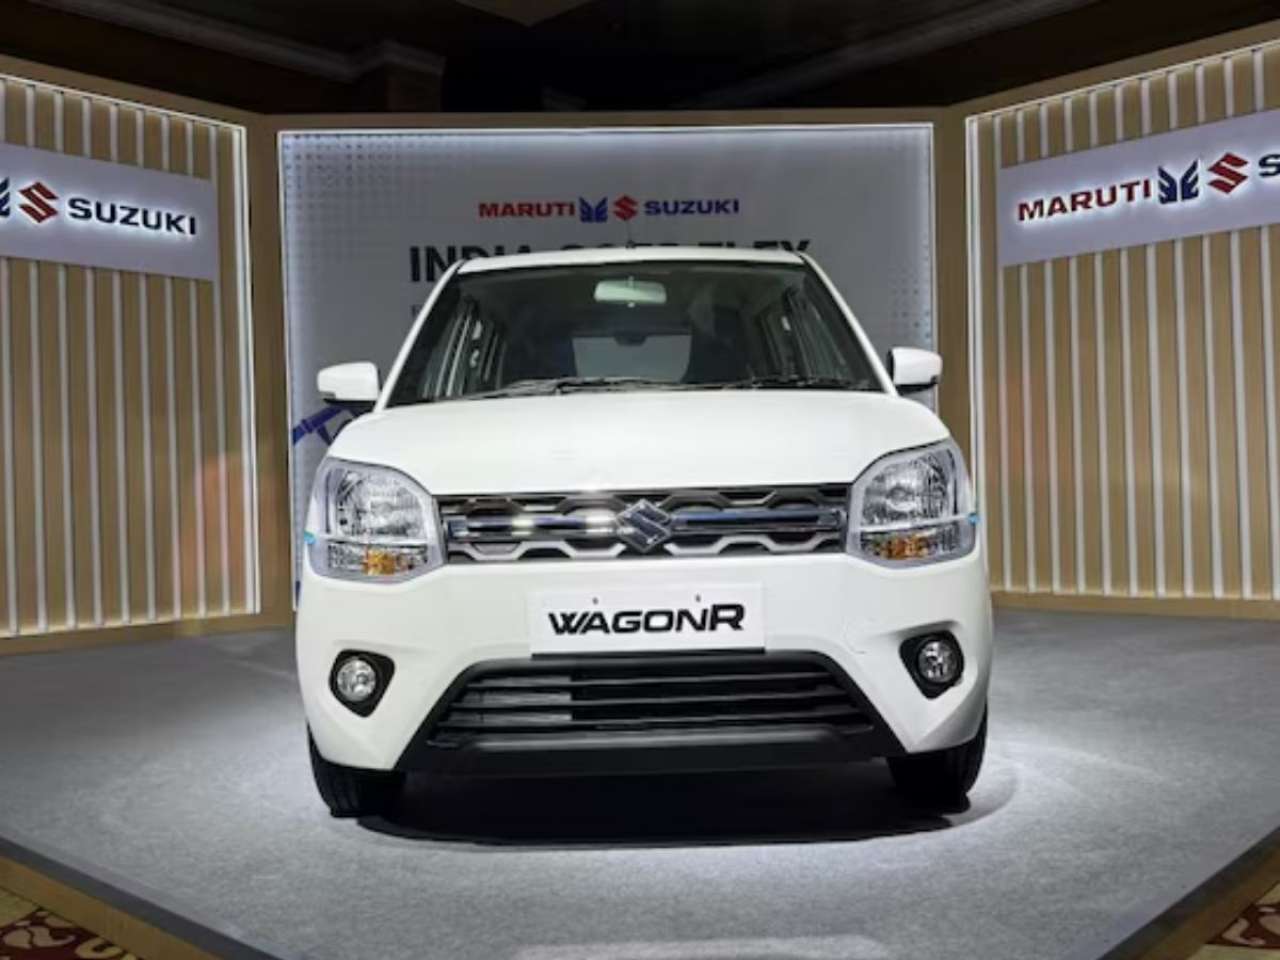 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
BUSINESS
Exemption under Section 54 should be available even if the loan taken for new property is not yet paid

Updated : May 18, 2017, 07:25 AM IST

For the sake of clarity, let me assume some facts :
Virar property – sales proceeds – as stated by you
Rs 25.90 lakh
Assumed indexed cost of acquisition (say) Rs 5.90 lakh
Taxable capital gains Rs 20.00 lakh
Mumbai property purchase price (say) Rs 60.00 lakh
Less : loan taken Rs 45.00 lakh
Net amount invested by you in Mumbai property Rs 15.00 lakh
Further, you have paid back
Rs 25 lakh of the loan amount of Rs 45 lakh after selling the Virar property. Therefore, you now have only Rs 20 lakh loan outstanding. As long as the amount utilised by you in buying the new house (Rs 15 lakh downpayment plus Rs 25 lakh loan repayment – total Rs 40 lakh), is greater than the taxable capital gains of Rs 20 lakh, the exemption under Section 54 should definitely be available. In any case, even if you had not paid back the loan on the Mumbai property, in my opinion, the exemption under Section 54 would still have been available, though it is debatable due to some adverse judicial decisions. In my opinion, as long as the cost of the Mumbai property (whether funded by yourself or through a loan) is higher than the amount of taxable capital gains on the Virar property, the exemption should be available. However, there have been some adverse judicial decisions regarding non allowability of the capital gain exemption, if the new property bought after the sale of the taxable property is bought by taking a loan. Whatever be the merit of those decisions, in any case, those adverse decisions cannot possibly apply where the new property was bought before the sale of the taxable property and the capital gain portion of the sale proceeds is greater than the downpayment made on the new property plus the loan repayment of the new property made from the sale proceeds.
It is not clear from your email whether your husband’s new employer offers the EPF facility or not. In case they do not offer this facility (because they have lower than the minimum required number of employees), your husband can withdraw the entire amount lying to his credit in his provident fund (PF) account (both employee and employer contribution), two months after leaving his former employer. There will be no tax on such withdrawal since your husband has been a member for more than five years.
The required forms are Form no 19 (for EPF) and Form no 10C (for employees pension scheme). However, if your husband’s new employer offers the provident fund facility, he will not be allowed to withdraw this amount especially if he opts for the PF facility at his new employer. He has an option to opt out of the PF scheme if his basic salary is greater than Rs 15,000 per month.