Crude oil price jumps above USD 108, hits 4-month high amid West Asia crisis; Know how it will impact India
 Donald Trump administration pulls down 'Mr Singh' self-deportation ad after backlash over racism, Sikh groups slam DHS campaign
 PM Modi expresses 'confidence on positive talks' for global welfare ahead of BRICS Summit
 BRICS Summit 2026: Delhi roads under restrictions, traffic diversions announced, rail services hit from Sept 11-13
 Russian President Vladimir Putin arrives in New Delhi to attend 18th BRICS Summit; bilateral talks with PM Modi in focus
 Hitman begins preparations for West Indies ODIs: Is Rohit Sharma sending 2027 World Cup message?
 ‘Disrespected’ Australian legend reveals what PCB still owes him after Pakistan coaching stint
 Will India-Afghanistan 1st T20I move from September 13? Here’s the latest update
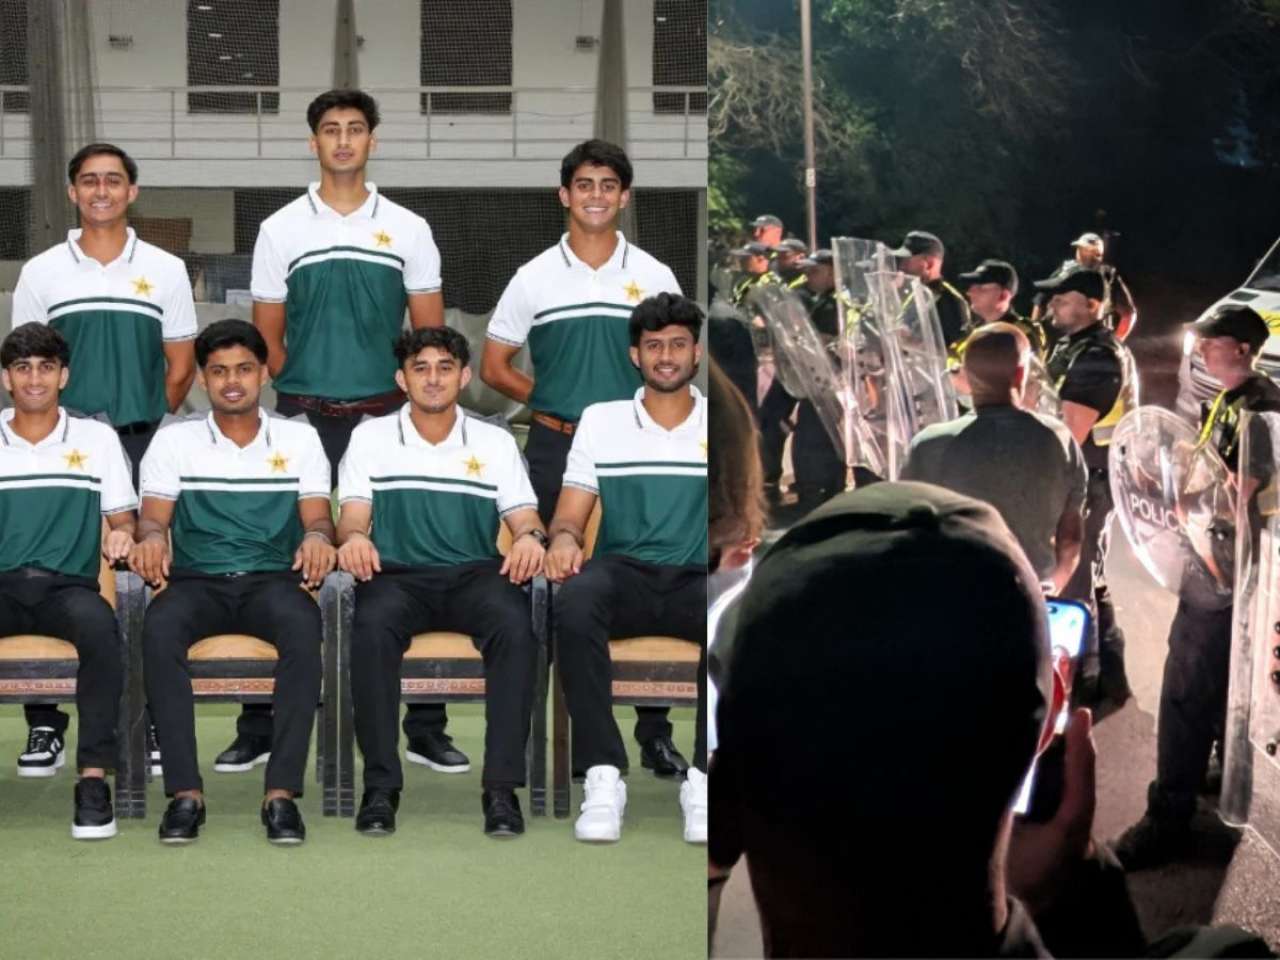 Pakistan U-19 team mistaken for asylum seekers: What actually happened outside their hotel?
 IND vs BAN Women’s Asia Cup Semi-Final: Can Bangladesh finally break India’s 8-game streak?
 Akanksha Chamola to seek alimony from Gaurav Khanna amid divorce? Orry drops major hint
 Double win for Shweta Tripathi: Amid Mirzapur The Movie's success, actress will screen her queer love story, Mujhe Jaan Na Kaho Meri Jaan at...
 Bigg Boss 20: Kushal Tanwar called out by ScoutOp's team over 'betrayed by a friend' narrative after captaincy task
 Shrimad Bhagavatam Part I Vishnurata: Amid Hanuman Ansh's blockbuster run, Ramanand Sagar's grandsons announce 7-part film universe, will release from...
 Bipasha Basu seeks Tukaram Mundhe's help, tags FDA's chief after claiming she found worms in THIS product: 'You're our only hope'
 iPhone 18 Price: Why Apple iPhone 18 Range Is So Much Costlier In India Than US?
 US Iran News: US Destroys 5 Iranian Oil Tankers, Iran Strikes US Base In Jordan
 Karnataka News: Amazon, Swiggy, Instamart Stores Raided In B'luru; Expired, Mislabelled Items Seized
 Israel News: Netanyahu Was Warned About Hamas Attack Before October 7, Didn't Act Because Of...
 Delhi PG Collapse: Supreme Court Steps In After Satya Niketan PG Tragedy Kills 7, Announces Big MoveCrude oil price jumps above USD 108, hits 4-month high amid West Asia crisis; Know how it will impact India
 Gold, silver prices today, September 11, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
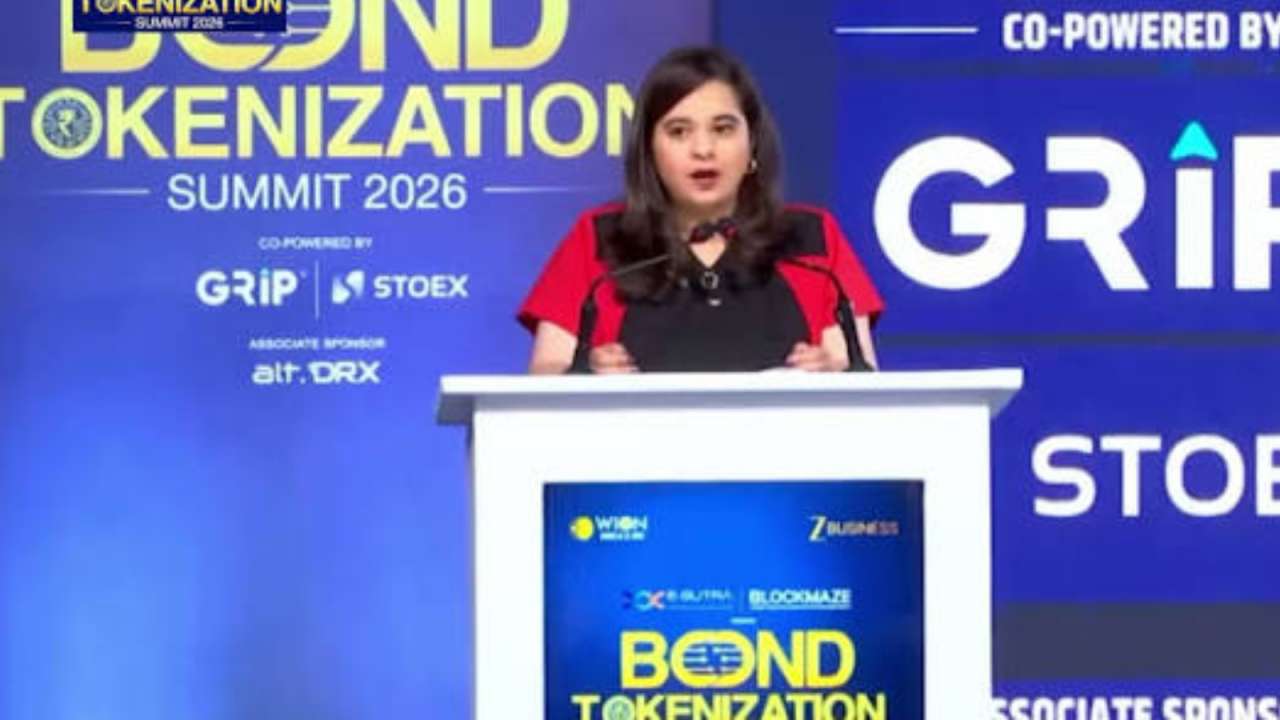 Zee Business Bond Tokenization Summit 2026 Mumbai: Finance leaders discuss RWA tokenization future of digital bonds
 Gold, silver prices today, September 10, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 8th Pay Commission: How much pension can central govt employees get under proposed pension structure?
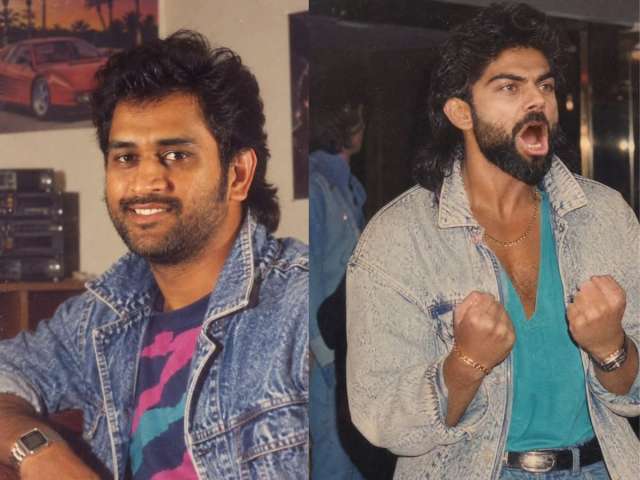 MS Dhoni to Virat Kohli: Indian cricket stars turn back time in viral 80s AI photo trend
 Bigg Boss 20: From Mary Kom, Mahhi Vij to Isha Rekhi, Qazi Touqeer, Rhiti Tiwari, Gullu; final confirmed list of contestants
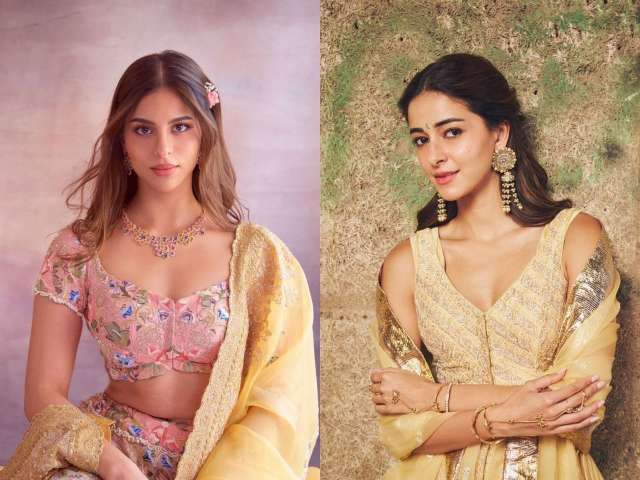 From Suhana Khan to Rasha Thadani, Ananya Panday: Gen-Z actresses acing modern-day Radha look in Janmashtami
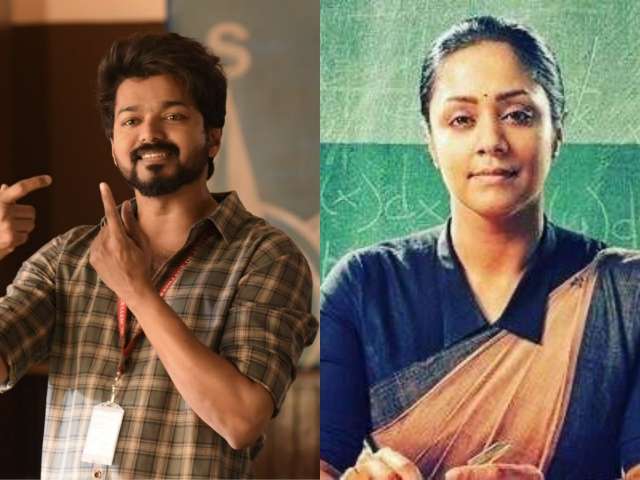 Teacher's Day 2026: From Thalapathy Vijay to Jyothika, 5 popular on-screen gurus from South that became household names
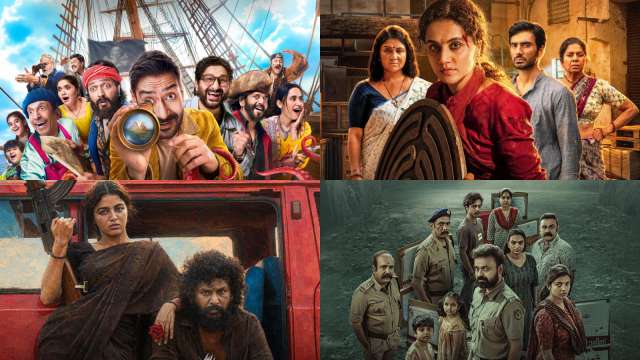 OTT Releases This Week: Dhamaal 4, Gandhari, DC, Bigg Boss 20; Indian movies, series to watch on Netflix, JioHotstar, ZEE5PM Modi expresses 'confidence on positive talks' for global welfare ahead of BRICS SummitBRICS Summit 2026: Delhi roads under restrictions, traffic diversions announced, rail services hit from Sept 11-13Russian President Vladimir Putin arrives in New Delhi to attend 18th BRICS Summit; bilateral talks with PM Modi in focus
 BRICS Summit 2026: Delhi gears up for world leaders as Russia’s Sergey Lavrov arrives, Putin set to land soon
 US H-1B Visa: What ending 60-day grace period could mean for Indian workers
 NEET PG Exam 2026: When will answer keys be released, how to access? Know here
 Teachers’ Day 2026: Heartfelt wishes, messages to make your favourite teacher feel special
 Who is Gyanendra Kumar Gangwar, IAS officer arrested in KPSC exam irregularities case?
 NLSIU cancels convocation amid row over CJI Surya Kant's proposed presence; CJP reacts
 GATE 2027 Registration: Application form to be available from August 27, check direct link, documents required and more
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
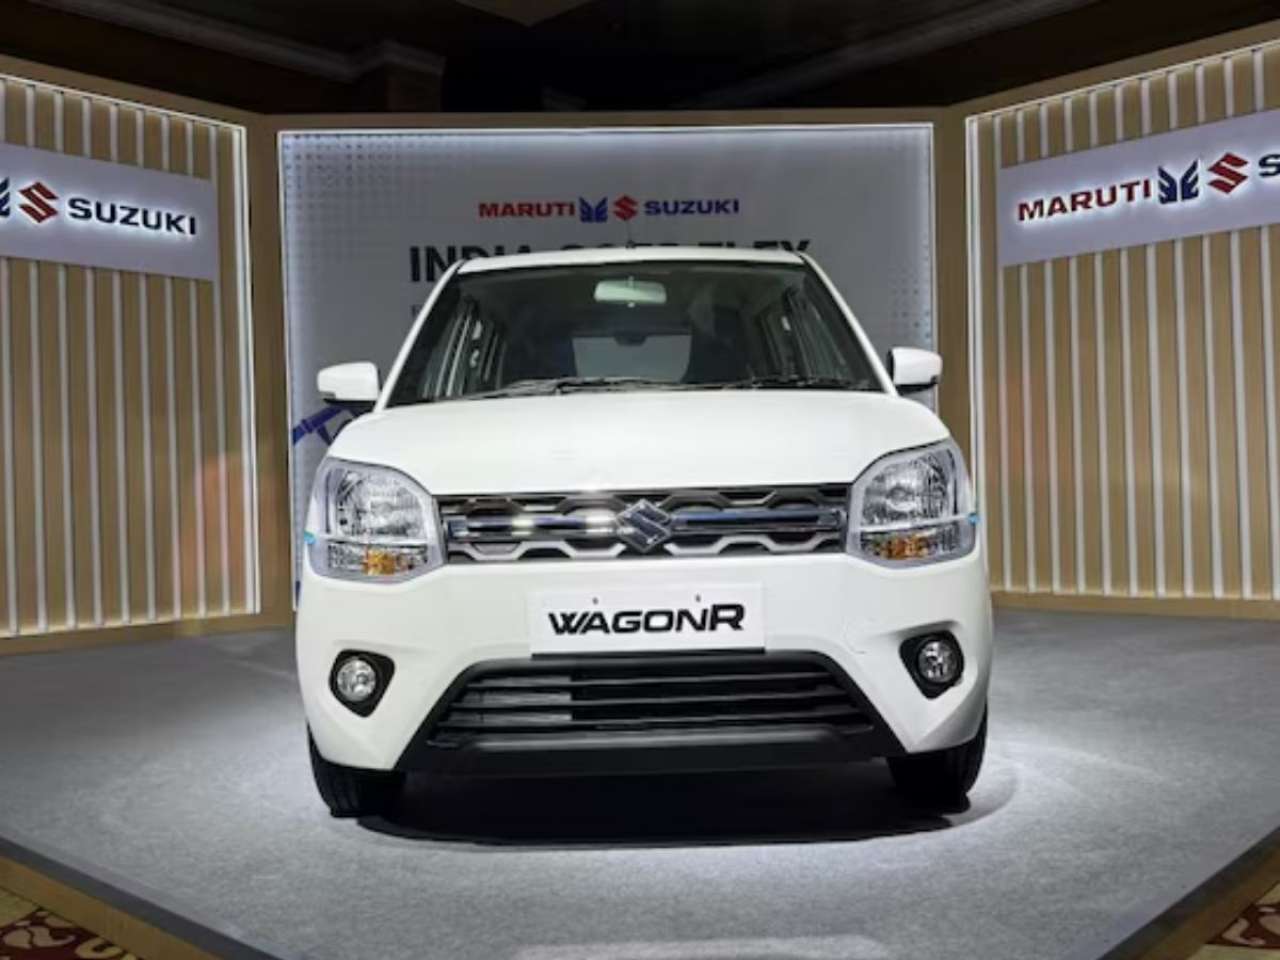 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
BUSINESS
DNA Web Team | Dec 22, 2018, 07:10 PM IST
1.New return filing system shall be introduced on a trial basis initially

The new return filing system shall be introduced on a trial basis from 1st April 2019 and on mandatory basis from July 1 next year.
2.Due date for furnishing GST returns extended

The due date for furnishing the annual returns in FORM GSTR-9, FORM GSTR-9A and reconciliation statement in FORM GSTR-9C for the Financial Year 2017 – 2018 shall be further extended till 30th June 2019.
3.All the changes in filing the returns

The following clarificatory changes, inter-alia, shall be carried out in the formats/instructions according to which the annual return / reconciliation statement is to be submitted by the taxpayers:
Amendment of headings in the forms to specify that the return in FORM GSTR-9 &FORM GSTR-9A would be in respect of supplies etc. ‘made during the year’ and not ‘as declared in returns filed during the year’;
All returns in FORM GSTR-1&FORM GSTR-3B have to be filed before filing of FORM GSTR-9&FORM GSTR-9C;
All returns in FORM GSTR-4 have to be filed before filing of FORM GSTR-9A;
HSN code may be declared only for those inward supplies whose value independently accounts for 10% or more of the total value of inward supplies;
Additional payments, if any, required to be paid can be done through FORM GST DRC-03 only in cash;
ITC cannot be availed through FORM GSTR-9 &FORM GSTR-9C;
All invoices pertaining to previous FY (irrespective of month in which such invoice is reported in FORM GSTR-1) would be auto-populated in Table 8A of FORM GSTR-9;
Value of “non-GST supply” shall also include the value of “no supply” and may be reported in Table 5D, 5E and 5F of FORM GSTR-9;
Verification by taxpayer who is uploading reconciliation statement would be included in FORM GSTR-9C.
4.Due date for furnishing FORM GSTR-8 extended

The due date for furnishing FORM GSTR-8 by e-commerce operators for the months of October, November and December, 2018 shall be extended till 31st Jan 2019.


5.Due date for submitting FORM GST ITC-04 extended

The due date for submitting FORM GST ITC-04 for the period July 2017 to December 2018 shall be extended till 31st March 2019.
6.Till when can ITC be availed?

ITC in relation to invoices issued by the supplier during FY 2017-18 may be availed by the recipient till the due date for furnishing of FORM GSTR-3B for the month of March, 2019, subject to specified conditions.
7.Where to upload revelant supporting documents?

All the supporting documents/invoices in relation to a claim for refund in FORM GST RFD-01Ashall be uploaded electronically on the common portal at the time of filing of the refund application itself, thereby obviating the need for a taxpayer to physically visit a tax office for submission of a refund application. GSTN will enable this functionality on the common portal shortly.
8.What are the type of refunds offered?

The following types of refunds shallalso be made available throughFORM GST RFD-01A:
Refund on account of Assessment/Provisional Assessment/Appeal/Any Other Order;
Tax paid on an intra-State supply which is subsequently held to be inter-State supply and vice-versa;
Excess payment of Tax; and
Any other refund.
9.How to apply for refunds?

In case of applications for refund in FORM GST RFD-01A(except those relating to refund of excess balance in the cash ledger)which are generated on the common portal before the roll out of the functionality described in point (10) above, and which have not been submitted in the jurisdictional tax office within 60 days of the generation of ARN, the claimants shall be sent communications on their registered email ids containing information on where to submit the said refund applications.
If the applications are not submitted within 15 days of the date of the email, the said refund applications shall be summarily rejected, and the debited amount, if any, shall be re-credited to the electronic credit ledger of the claimant.
10.New window for migration process

One more window for completion of migration process is being allowed. The due date for the taxpayers who did not file the complete FORM GST REG-26 but received only a Provisional ID (PID) till 31.12.2017 for furnishing the requisite details to the jurisdictional nodal officer shall be extended till 31st Jan 2019. Also, the due date for furnishing FORM GSTR-3B and FORM GSTR-1 for the period July, 2017 to February, 2019/quarters July, 2017 to December, 2018 by such taxpayers shall be extended till 31st March 2019.
11.Details about late fee waiver

Late fee shall be completely waived for all taxpayers in case FORM GSTR-1, FORM GSTR-3B &FORM GSTR-4 for the months / quarters July, 2017 to September, 2018, are furnished after 22nd December 2018 but on or before 31st March 2019.
12.Who will be restricted from generating e-way bills?

Taxpayers who have not filed the returns for two consecutive tax periods shall be restricted from generating e-way bills. This provision shall be made effective once GSTN/NIC make available the required functionality.
13.Clarifications should be sought within stipulated time

Clarifications shall be issued on certain refund related matters like refund of ITC accumulated on account of inverted duty structure, disbursal of refunds within the stipulated time, time allowed for availment of ITC on invoices, refund of accumulated ITC of compensation cess etc.
14.When will the formal notification come?

Changes made by CGST (Amendment) Act, 2018, IGST (Amendment) Act, 2018, UTGST (Amendment) Act, 2018 and GST (Compensation to States) Amendment Act, 2018 and the corresponding changes in SGST Acts would be notified on 1st January.