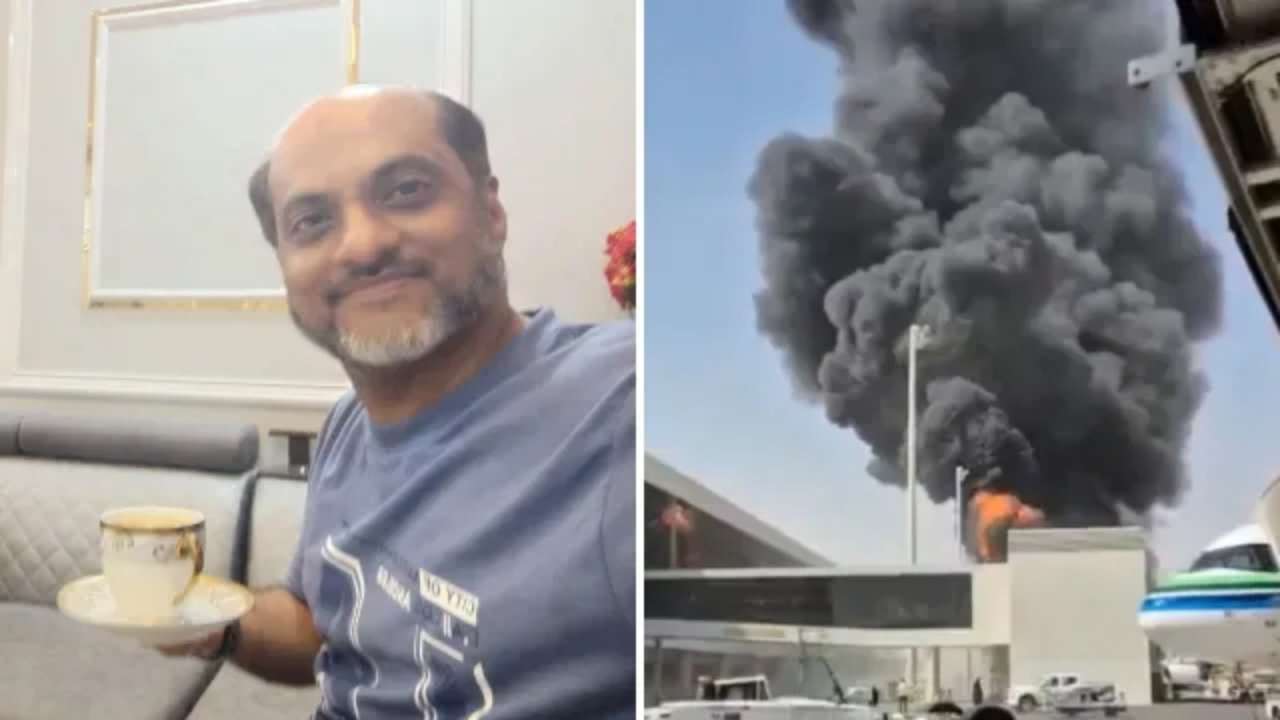
 Riyadh Airport Attack: 1 Indian national killed, 11 injured in deadly Houthi strike
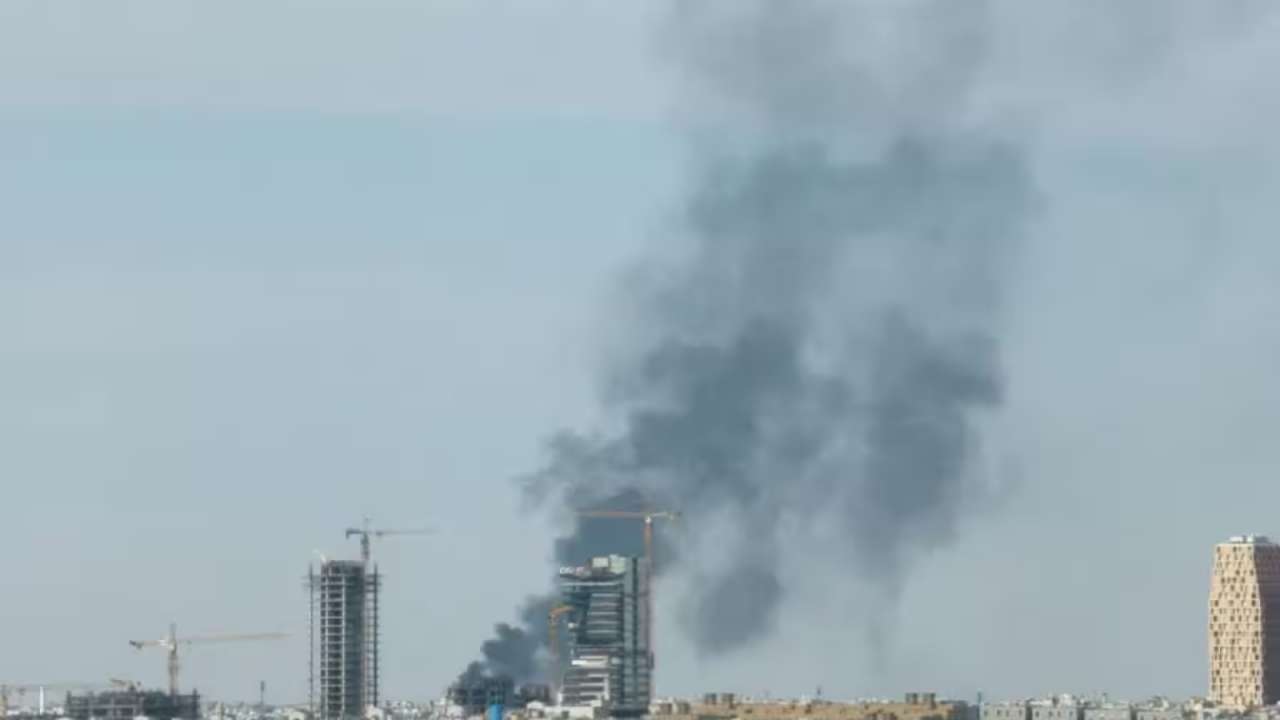 Riyadh Airport targeted again, fire reported day after Houthi deadly attack killed 12 people
 'Terrible human being’: Ex-India pacer Venkatesh Prasad takes scathing dig at Elon Musk amid escalating Starlink India row
 Donald Trump claims Russia-Ukraine have agreed to energy ceasefire effective immediately
 Amitabh Bachchan greets fans outside Jalsa on 84th birthday, video goes viral - Watch'Terrible human being’: Ex-India pacer Venkatesh Prasad takes scathing dig at Elon Musk amid escalating Starlink India row
 Fact Check: Did Virat Kohli really play in Mumbai’s Kanga League? Mystery behind viral No. 18 clip revealed
 Ranji Trophy: Mohammed Shami stars with 4/30 for Bengal as pressure mounts on selectors over India return
 Suresh Raina to become CSK’s next batting coach after Michael Hussey’s exit? Former India star breaks silence
 IND vs WI: Can Sanju Samson eclipse coach Gautam Gambhir? Big record in sight as India look to bounce back in 3rd T20IAmitabh Bachchan greets fans outside Jalsa on 84th birthday, video goes viral - Watch
 Drishyam 3 box office collection day 10: Ajay Devgn film crosses Rs 300 crore mark in India
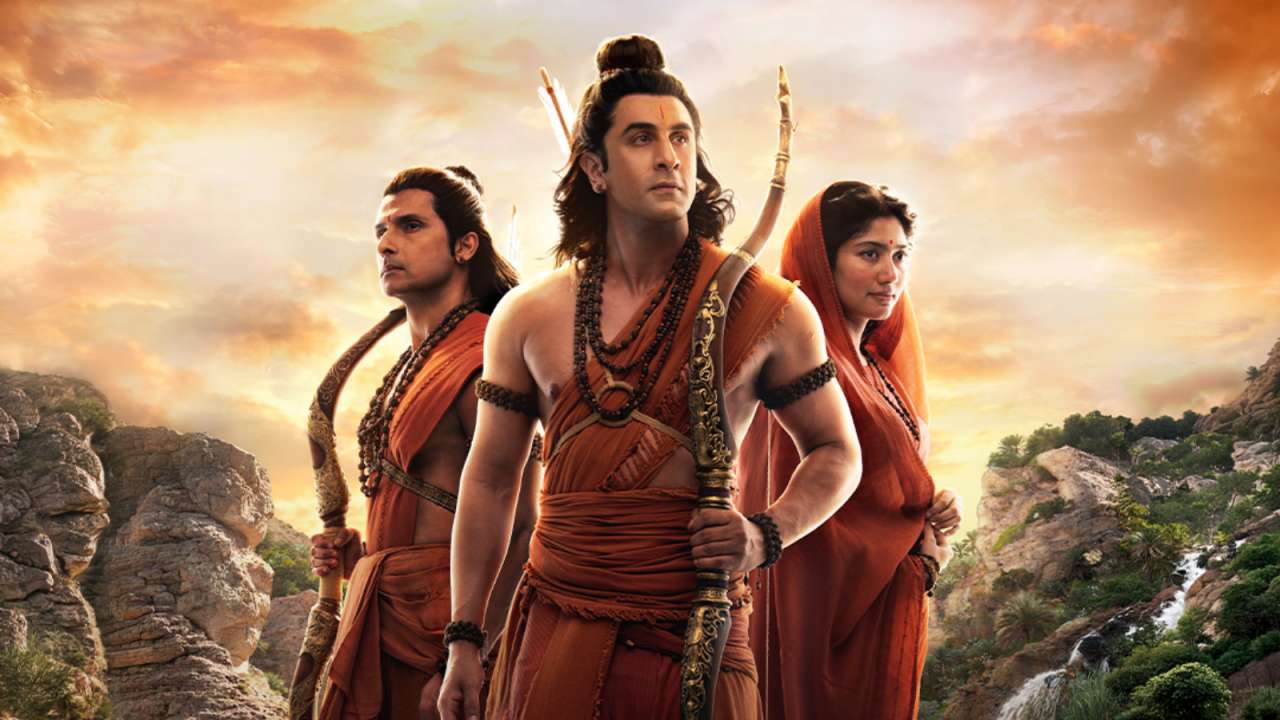 Ramayana release date: Ranbir Kapoor film to hit theatres worldwide before Diwali, advance bookings open on Dussehra
 Nana Patekar death: Final post-mortem reveals actor died due to this reason
 Vidyut Jammwal reveals what separates Indian and Hollywood action films: 'If you see movies like Baahubali...'
 Saudi Houthi War: India Issues Urgent Advisory To Citizens In Saudi After Riyadh Airport Attack
 CJP Protest: 7,000 CRPF Personnel Rushed To Capital Ahead Of CJP's Oct 10 March
 CJP News: Delhi CAPF Deployment Raised To 26,000 Ahead Of CJP October 10 Protest
 CJP Protest: In Bengaluru Dhruv Rathee, Prakash Raj Join Anti-SIR Demonstration
 Flydubai Flight News:'Revenge For Gaza'; Flydubai Co-Pilot Hamam Al-Hammami Confesses To Terror Plot
 Gold, Silver prices today, October 10, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 Reliance Jio IPO: Price Band likely at Rs 1065-1119 per share, issue may open on October 21; check details
 How to bypass H-1 B visa restrictions? Can Indian professionals use L-1 and O-1 visas as alternative routes to enter US?
 US Green Card Row: TCS says PERM suspension won't impact business, applications in single digits
 Gold, Silver prices today, October 9, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
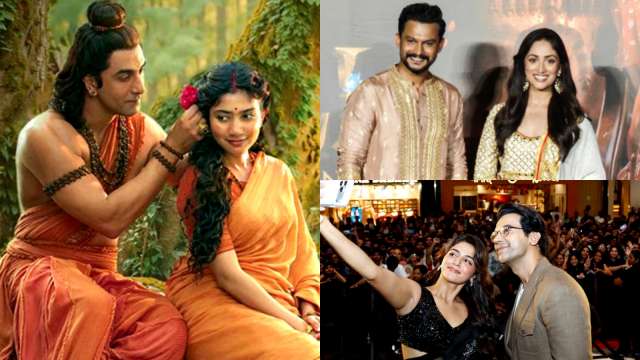 Ranbir Kapoor-Sai Pallavi, Yami Gautam-Addinath Kothare, Rajkummar Rao-Wamiqa Gabbi: 5 fresh on-screen jodis to watch out for in 2026
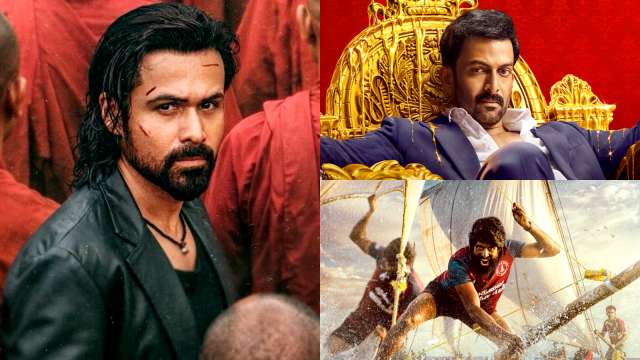 OTT Releases This Week (October 5-11): Awarapan 2, Khalifa, Mandaadi; new India movies, shows to watch on Netflix, Prime Video
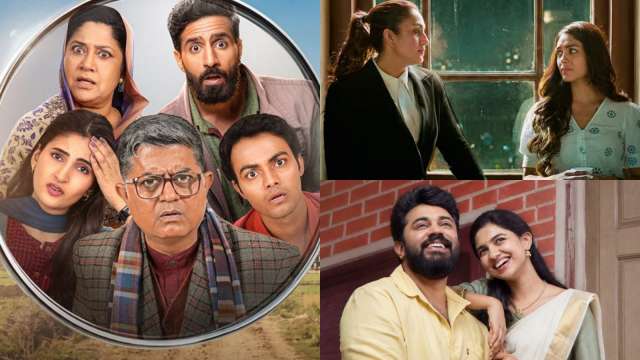 OTT Releases This Week (Sept 28 - Oct 4): Dupahiya 2, Pooja Meri Jaan; new movies and shows to watch this Gandhi Jayanti weekend
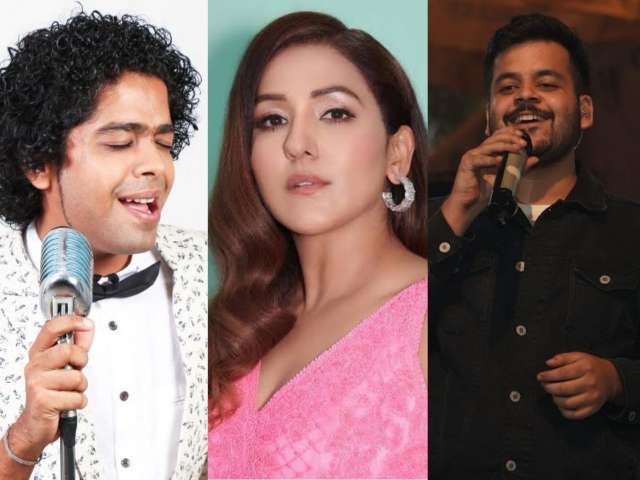 From Neeti Mohan, Heer, Sarthak Kalyani; Ahead of Sa Re Ga Ma Pa, 5 musical geniuses championed by AR Rahman
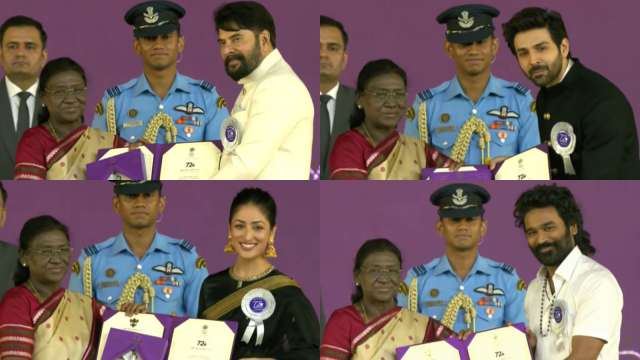 72nd National Film Awards 2024: Kartik Aaryan, Yami Gautam, Aditya Dhar, Mammootty, Dhanush, Anant Nag accept honours
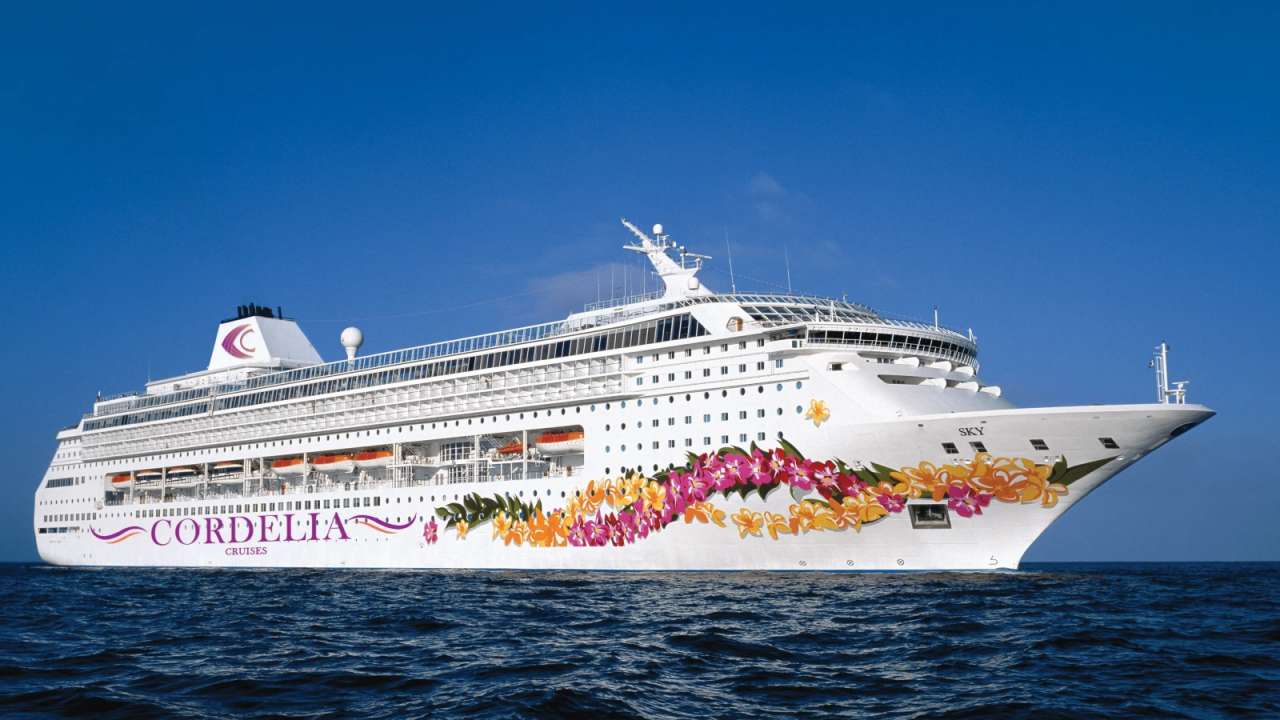 Mumbai welcomes Cordelia Sky, second vessel in Cordelia Cruises Fleet; Check features, routes and more
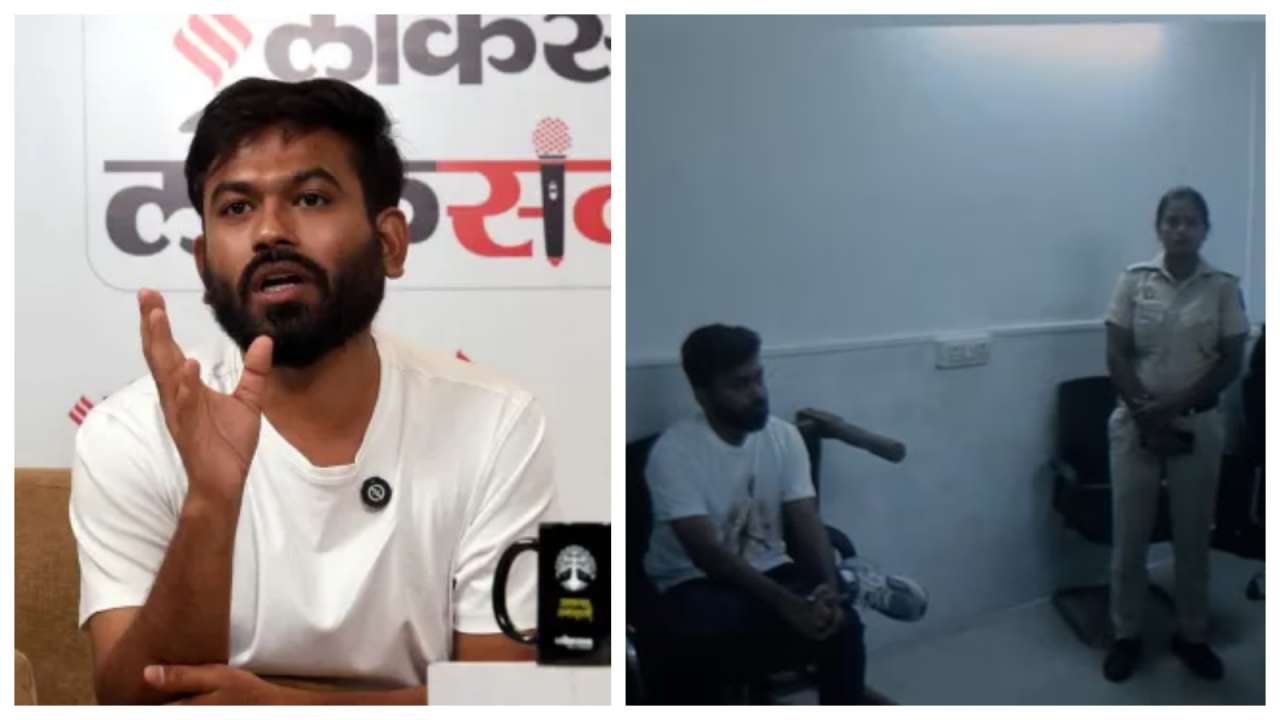 Abhijeet Dipke Denied Permission To Speak To Family? Delhi Police releases video, says offered flight and phone help
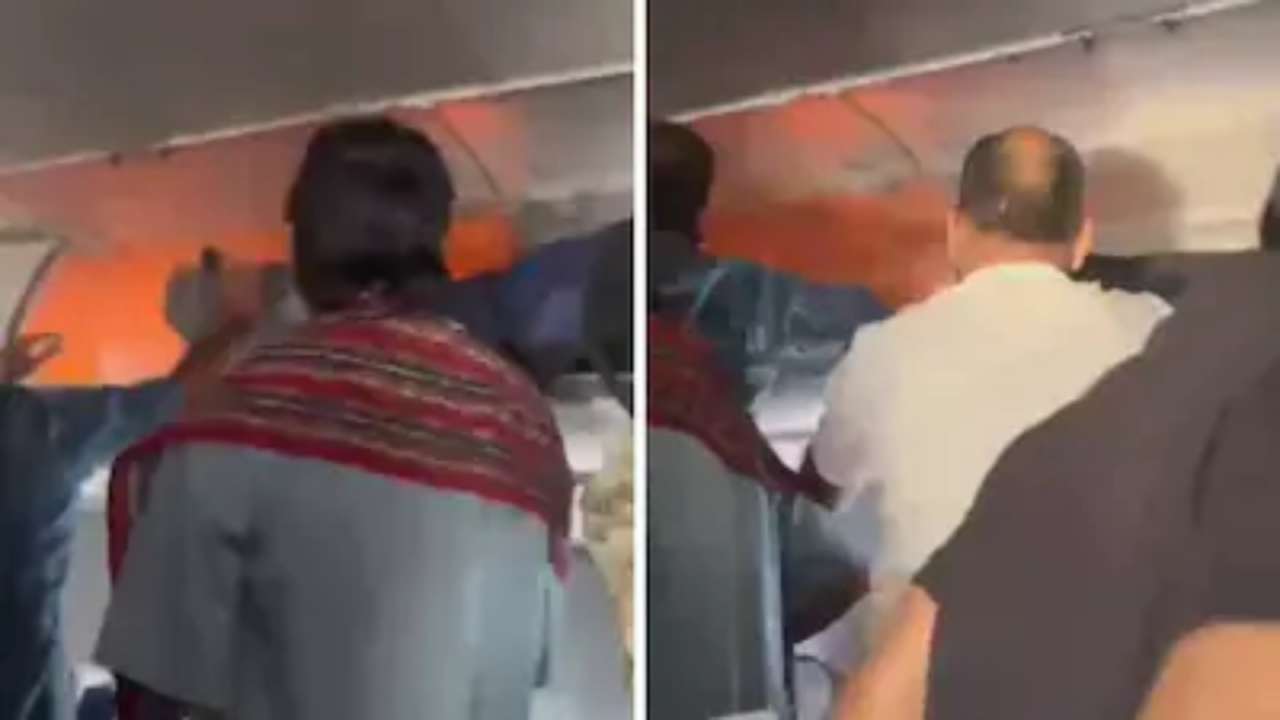 IndiGo Delhi-Chennai flight diverted to Hyderabad after smoke from passenger device
 'India Does Not Change Security Policy Under Pressure': BJP MP Nishikant Dubey hits back at Elon Musk over Starlink
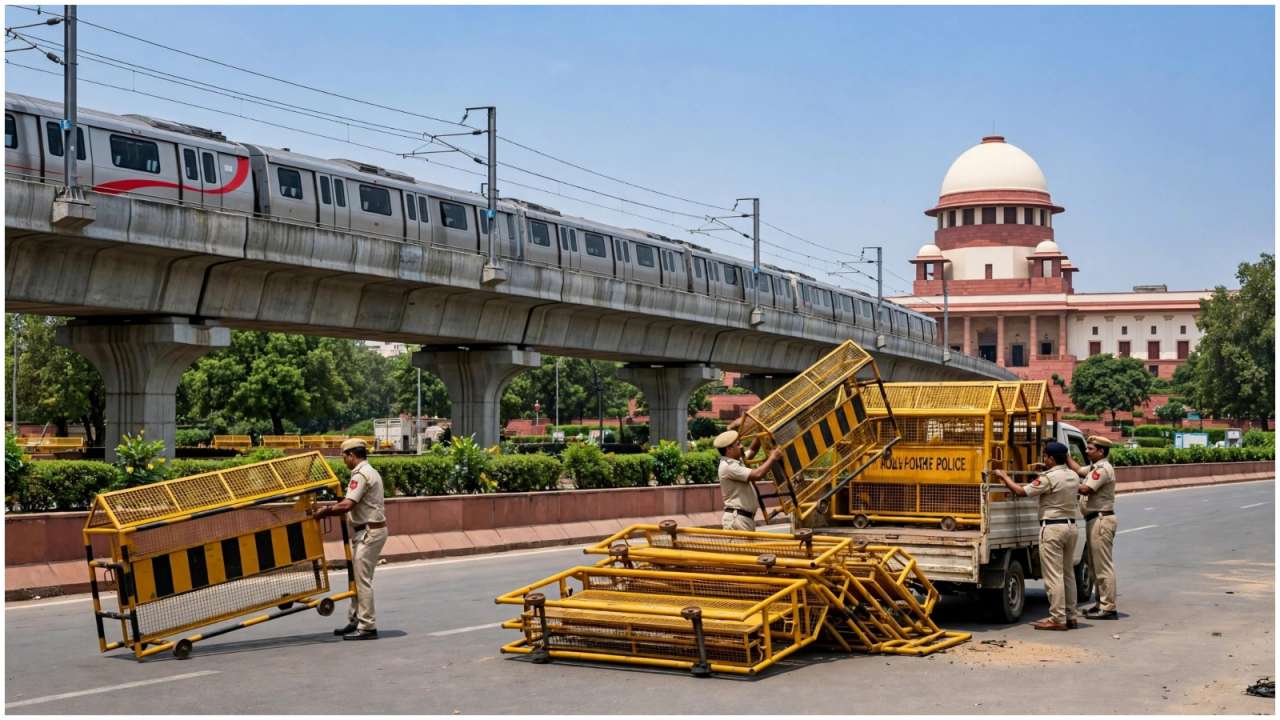 No metro disruption, no internet shutdown: Supreme Court's message to Centre on CJP protest
 Third Language Row: SC extends relaxation to Class 6 students, asks CBSE to grant exemption, here's what it means
 NEET PG 2026 Result Out: Check how to download scorecard from natboard.edu.in; Know category-wise cut-off and more
 Five-year BTech programmes? Ex-IIT director makes proposals amid IIT suicide controversy
 CBSE Date Sheet 2027: When will Class 10, 12 timetable be released? Check details here
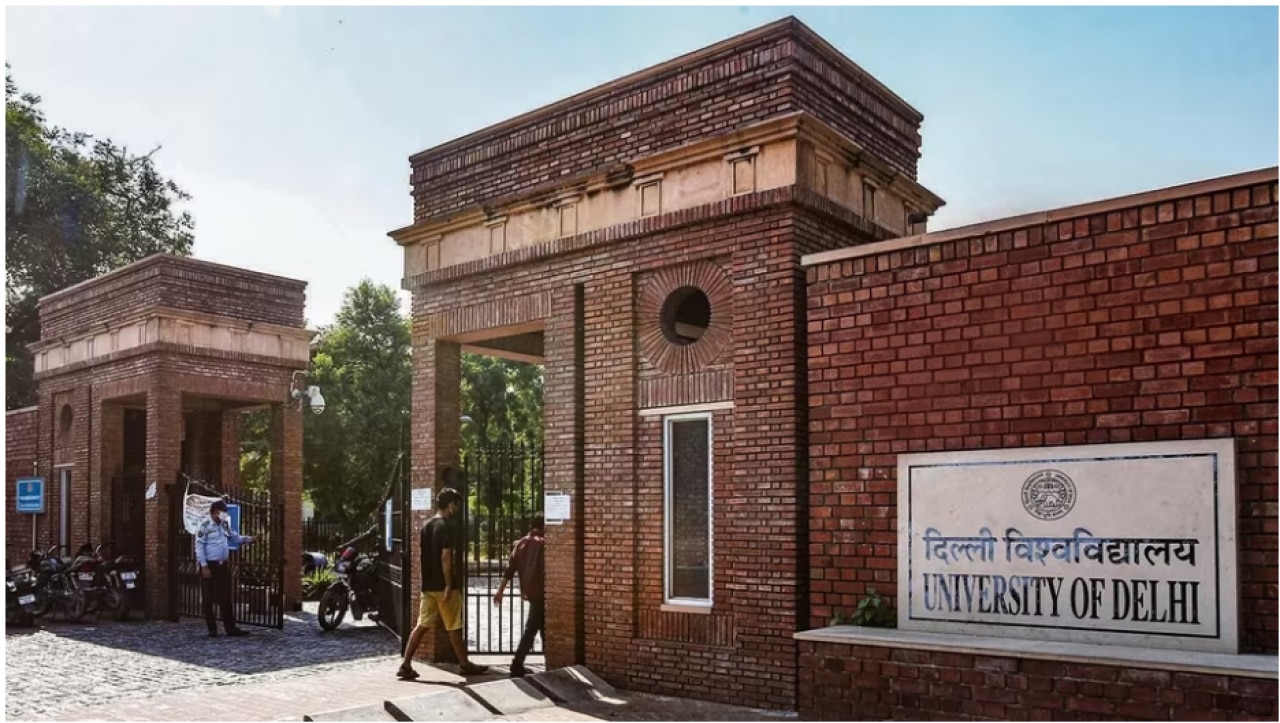 From Rs 150 in 1947 to powerful student body: The story of DUSU’s rise | Explained
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
BUSINESS
Typically, you check your credit information report (CIR) when your loan gets rejected and the lender tells you it’s because of some information on your CIR.

Updated : Mar 30, 2018, 03:55 AM IST

Typically, you check your credit information report (CIR) when your loan gets rejected and the lender tells you it’s because of some information on your CIR. But there is no need to panic. Mistakes on a CIR can be easily corrected with the help of the credit bureau. All you need to do is:
a) Purchase your own CIR from the credit bureau
b) Identify the erroneous information
c) Provide name, address, date of birth, an enquiry control number (ECN) and the nature of the error on the credit bureau’s website.
This is known as a ‘dispute request’ in credit bureau parlance.
The ECN is a unique 9-digit number found on the top right hand side of your CIR and is generated every time a CIR is generated. It is very important to provide this number to the bureau, as it helps identify the CIR on which you would like to ‘dispute’ information.
What does the credit bureau do once I raise a ‘dispute request’?
Once you have raised a ‘dispute request’, the credit bureau checks whether all the requisite details have been provided. The request is then routed to the dispute resolution department for analysis.
This is because one type of dispute request can be resolved by the credit bureau itself. If the credit bureau is unable to resolve the request, it is routed to the relevant lender. Once the lender confirms that there is an error, it will provide the credit bureau with corrected data. The credit bureau then updates the data and informs you as appropriate. Always remember, it’s the duty of the bureau to help you resolve your request.
Why doesn’t the credit bureau verify the information with consumers before updating the report?
Credit bureaus have the information of millions of individuals. It’s virtually impossible to verify the information of each individual. The ‘dispute process’ is provided to the consumer to help correct any discrepancies that may arise in their CIR exactly for this reason. Hence, it is recommended to review your CIR prior to submitting a loan application just to be sure that there are no errors on your CIR which may hamper your loan approval.
The writer is senior vice-president - consumer relations, Cibil (www.cibil.com) and can be reached at creditwise@cibil.com.