 Pakistan to redraw political map? Army Chief Asim Munir wants 12-15 new provinces
 Nana Patekar cremated with full state honours in Pune as family, politicians and fans bid farewell
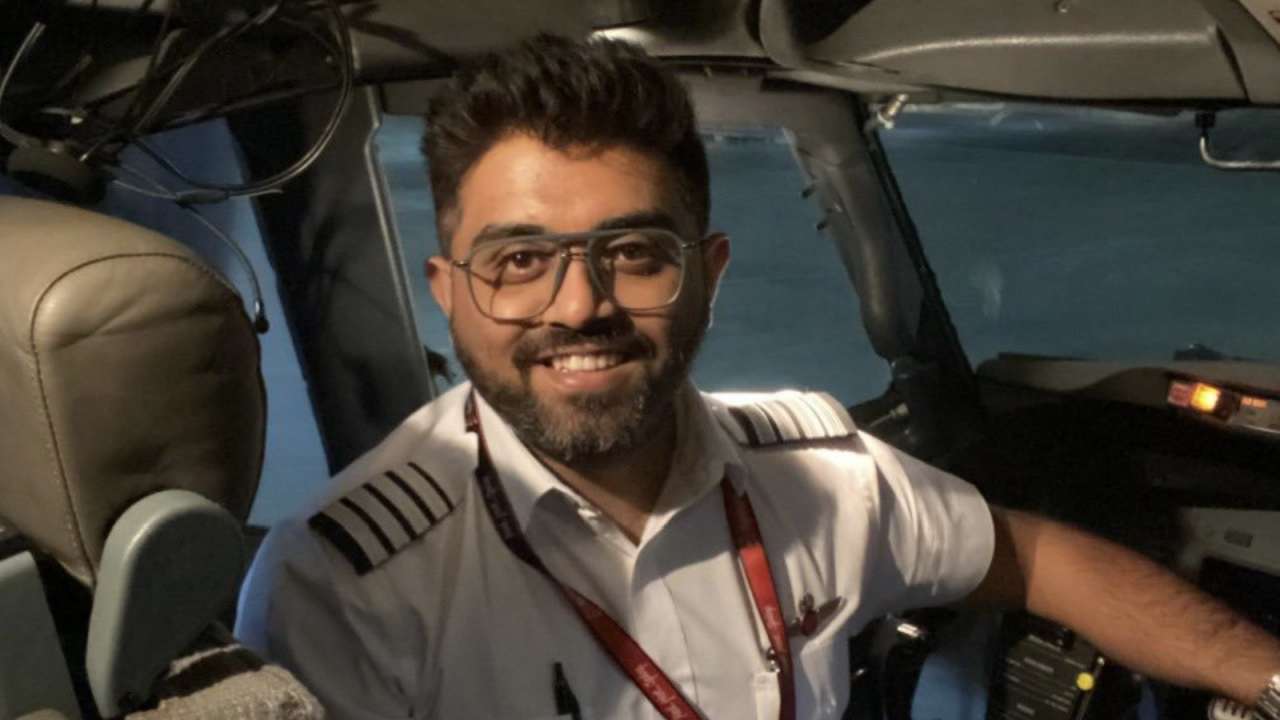 Flydubai Captain Smit Machchhar to receive Israel’s Presidential Award for Heroism
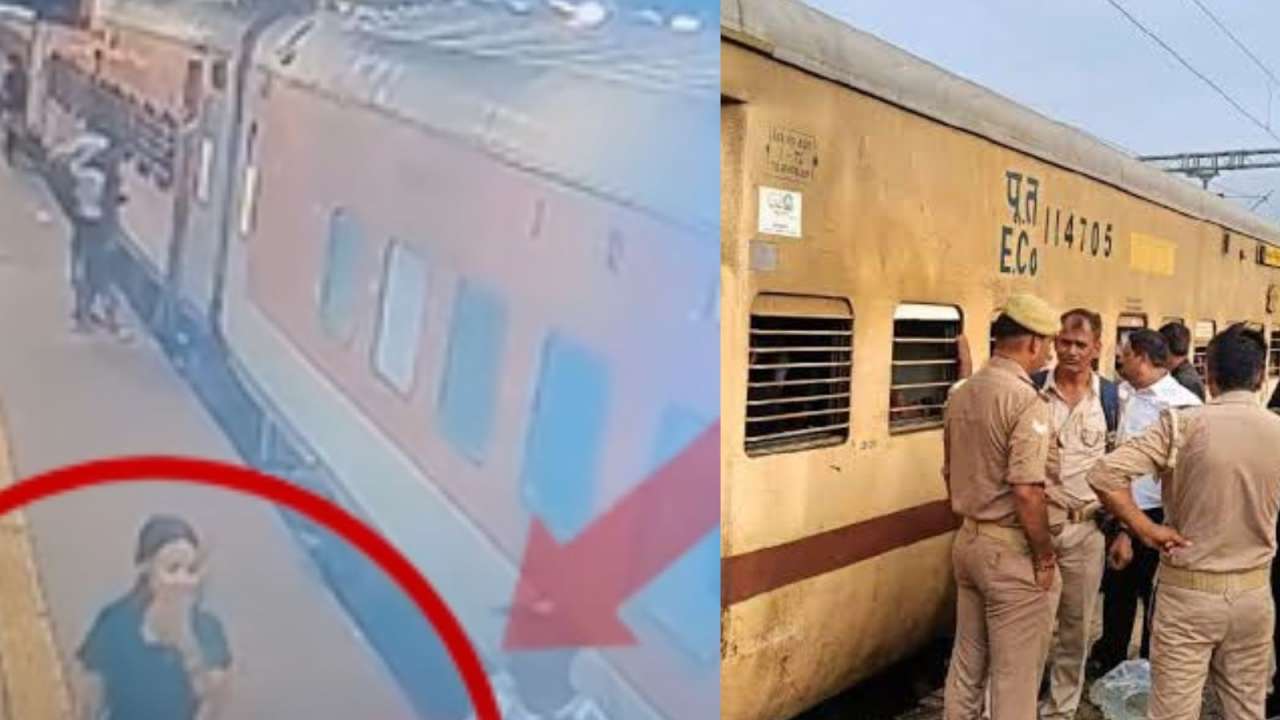 Andhra Ashamed: 20-year-old student says in last video before death, 'Drunk men all around me'
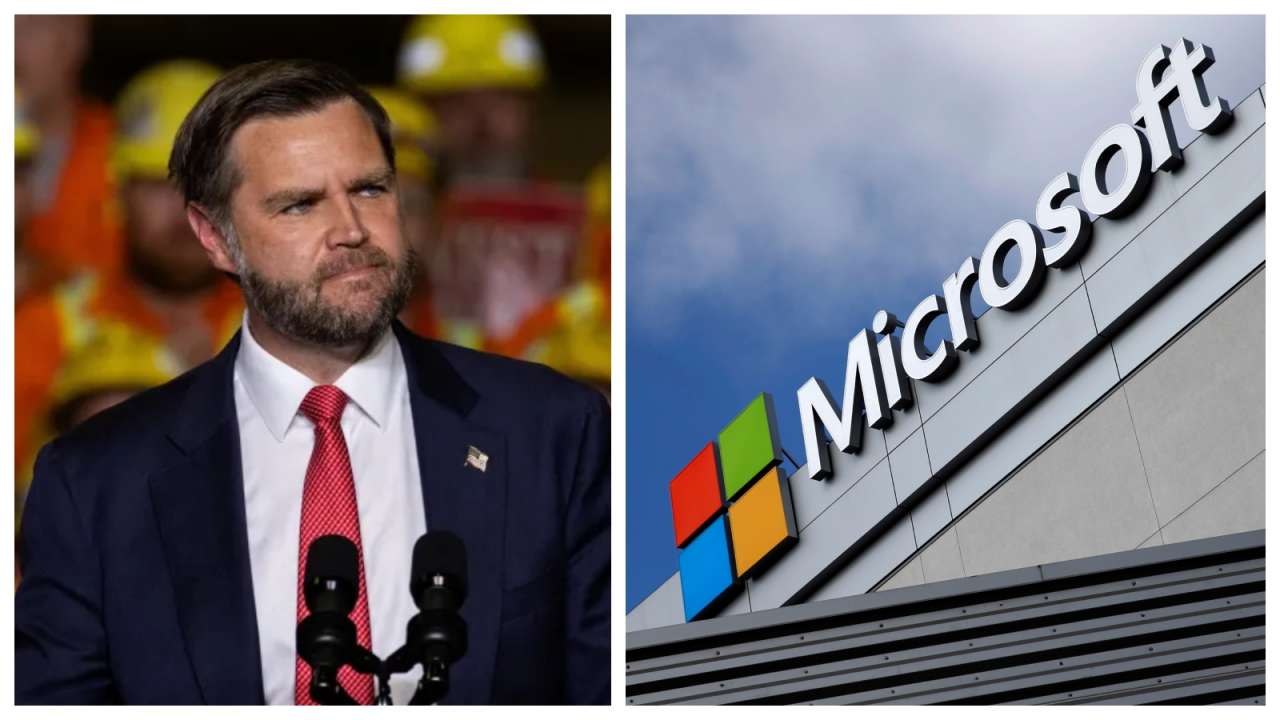 H1-B Visa Crisis Deepens: Microsoft banned from hiring foreigners, JD Vance calls them 'indentured servants'
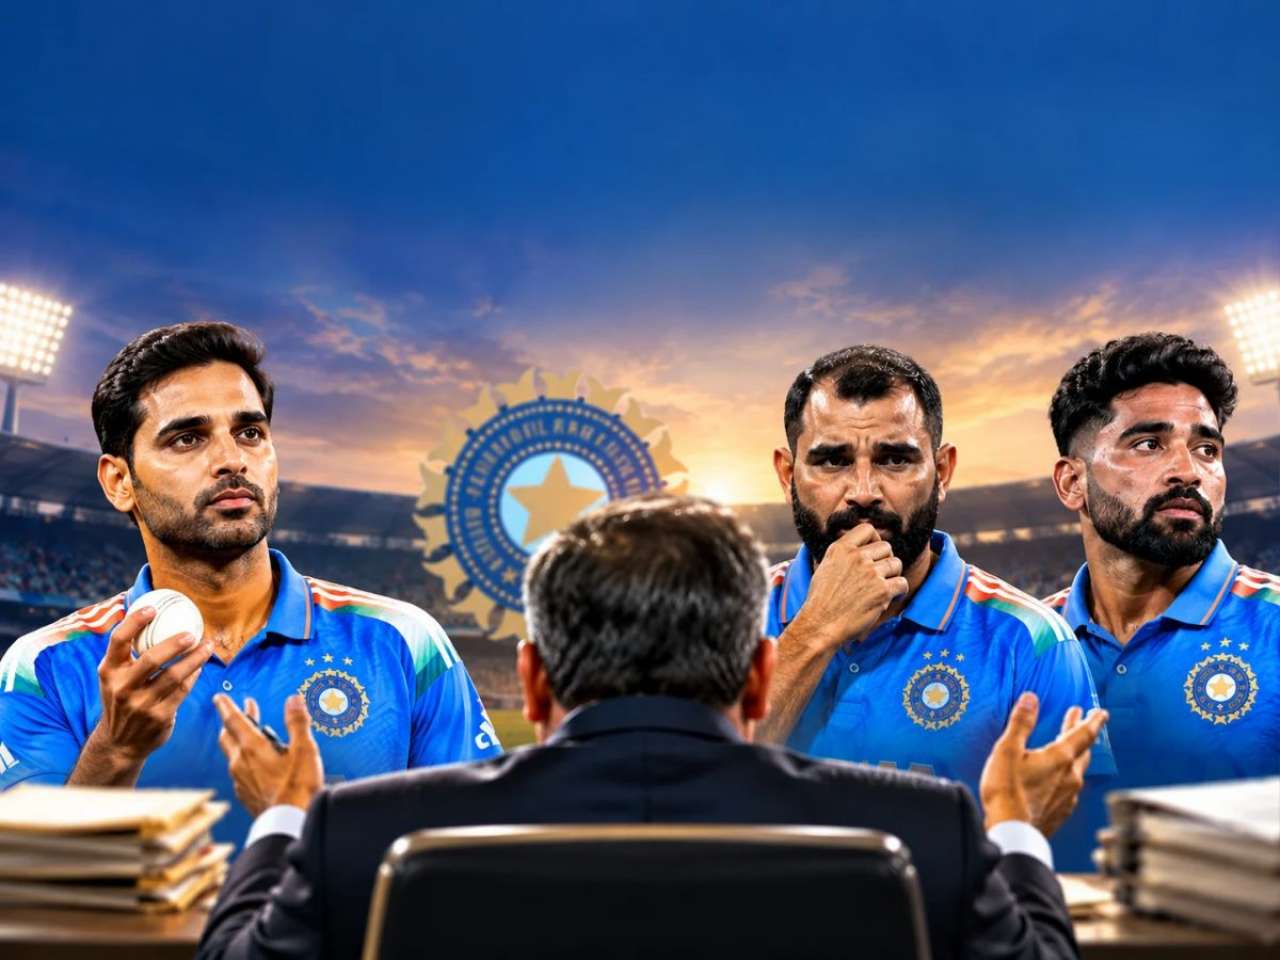 BCCI selectors face big question on Shami, Siraj after Bhuvneshwar Kumar recall: 'Who're your 2nd, 3rd seamers?'
 India vs Pakistan U-19 Asia Cup 2026: Arch-rivals ready for high-voltage Oman clash; Full schedule inside
 'Play more cricket': 1983 World Cup legend Kapil Dev hands stern advice to Hardik Pandya amid prolonged absence
 PM Narendra Modi to meet Asian Games 2026 medallists on October 15; India won 85 medals in Aichi-Nagoya
 Can Bhuvneshwar Kumar’s surprise T20I comeback pave way for 2027 ODI World Cup return?Nana Patekar cremated with full state honours in Pune as family, politicians and fans bid farewell
 Amitabh Bachchan gets emotional, pays homage to Nana Patekar at KBC 18, celebrates late actor's 'bebaki, sadgi, sach ko kehne ka saahas'
 Viral video | Nana Patekar demise: Maharashtra CM Devendra Fadnavis pays respect to Nana Patekar, consoles family, helps carry his coffin ahead of funeral
 'Ch****ya tujhse paise lunga': When Nana Patekar did THIS blockbuster for free, asked director to donate his fees, movie name is...
 Nana Patekar dies at 75: Veteran star's LAST text message dropped major hint of his weak health, he admitted feeling unwell, doctor narrates his final hours
 CJP News: Delhi CAPF Deployment Raised To 26,000 Ahead Of CJP October 10 Protest
 CJP Protest: In Bengaluru Dhruv Rathee, Prakash Raj Join Anti-SIR Demonstration
 Flydubai Flight News:'Revenge For Gaza'; Flydubai Co-Pilot Hamam Al-Hammami Confesses To Terror Plot
 Delhi Building Collapse: 5-Storey Building Collapses In Seemapuri; Emergency Teams Rush To Spot
 PM Modi News: Congress Attacks Modi Over Repo Rate Hike, Says ‘Achhe Din’ Became ‘Vasooli Wale Din’
 Gold, Silver prices today, October 9, 2026: Check city-wise rates in Delhi, Mumbai, Chennai, Kolkata and more
 57th GST Council Meeting: Experts hail decriminalisation, wider ITC refunds; flag implementation challenges
 HDFC Bank appoints Anup Bagchi as MD & CEO; set to earn Rs 35.9 crore annual packageHDFC Bank appoints Anup Bagchi as MD & CEO; set to earn Rs 35.9 crore annual package
 How was Rs 11 lakh crore wiped out in a day? Why did Sensex and Nifty crash after RBI rate hike?
 OTT Releases This Week (Sept 28 - Oct 4): Dupahiya 2, Pooja Meri Jaan; new movies and shows to watch this Gandhi Jayanti weekend
 From Neeti Mohan, Heer, Sarthak Kalyani; Ahead of Sa Re Ga Ma Pa, 5 musical geniuses championed by AR Rahman
 72nd National Film Awards 2024: Kartik Aaryan, Yami Gautam, Aditya Dhar, Mammootty, Dhanush, Anant Nag accept honours
 OTT Releases This Week (September 14-20): Lust Stories 3, Irumudi, Thudakkam; Indian movies, series to watch on Netflix, Prime Video, JioHotstar
 Ganesh Utsav 2026: Deva Shree Ganesha, Sindoor Lal Chadayo; 5 iconic Ganpati songs that should be must-haves in your playlistAndhra Ashamed: 20-year-old student says in last video before death, 'Drunk men all around me'
 Rahul Gandhi backs Elon Musk in Starlink India row; says, ‘Wait till you discover the other guy’
 Cancer drugs to get cheaper by up to 70% as govt fixes trade margin at 30%
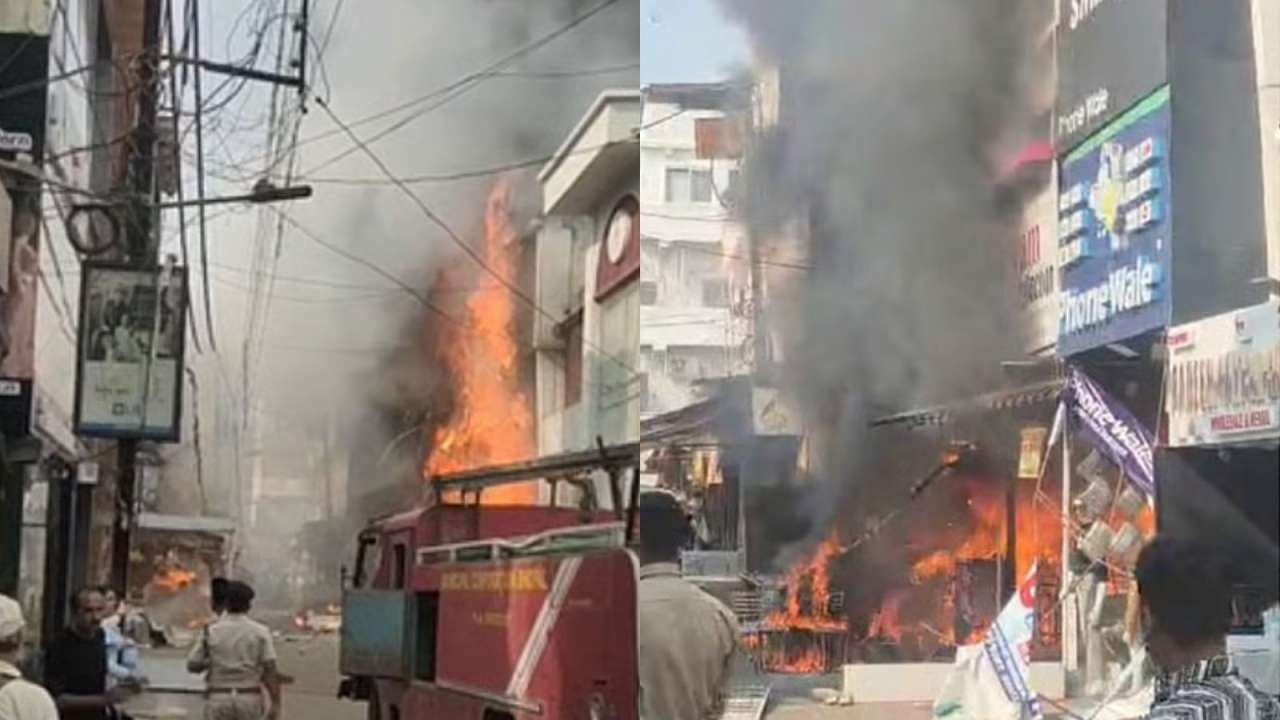 Massive Fire In Madhya Pradesh: Shops gutted in Bhopal's new market! Watch video
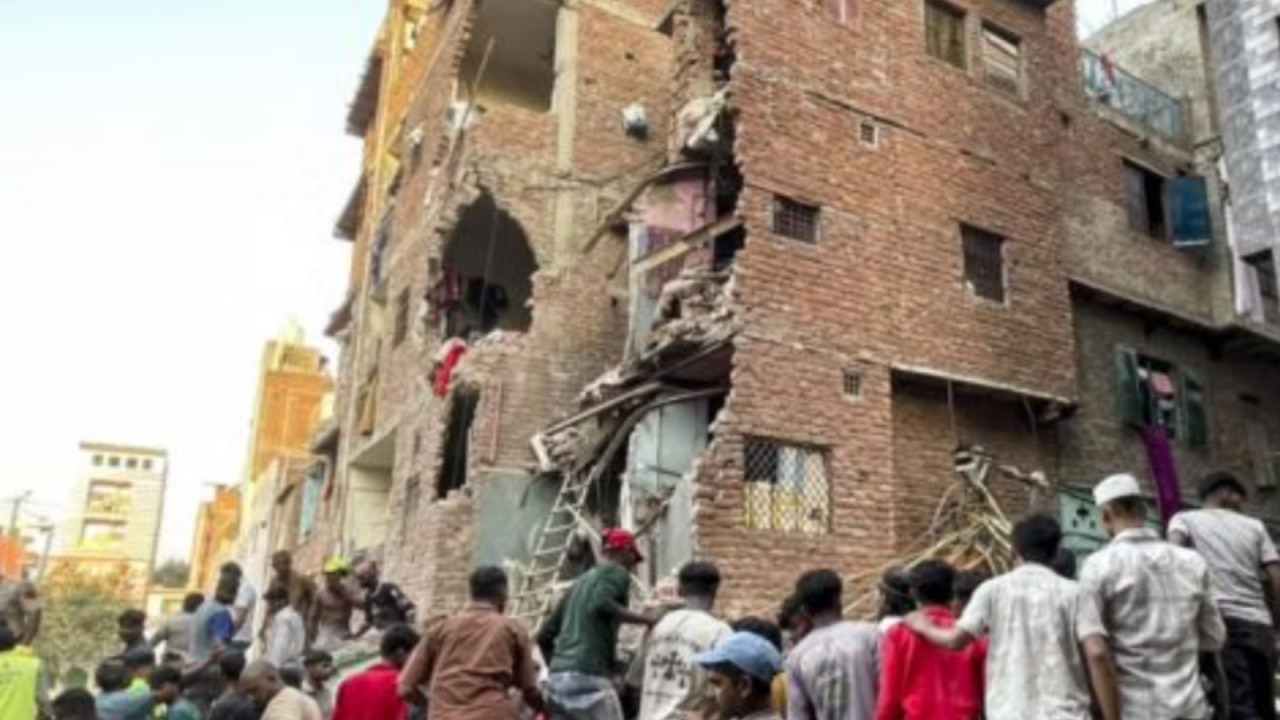 Delhi Building Collapse: Death toll rises to 5 in New Seemapuri; rescue operations continue
 Third Language Row: SC extends relaxation to Class 6 students, asks CBSE to grant exemption, here's what it means
 NEET PG 2026 Result Out: Check how to download scorecard from natboard.edu.in; Know category-wise cut-off and more
 Five-year BTech programmes? Ex-IIT director makes proposals amid IIT suicide controversy
 CBSE Date Sheet 2027: When will Class 10, 12 timetable be released? Check details here
 From Rs 150 in 1947 to powerful student body: The story of DUSU’s rise | Explained
 After Hyundai, Maruti Suzuki makes cars costlier ahead of festive season: Check new prices after hike
 Hyundai cars to get costlier from September: Check new prices and reason behind hike
 Why can't consumers choose pure petrol or E10? Centre explains why E20 is now the standard fuel
 Centre claims E20 fuel does not damage engines, cites data from Maruti Suzuki and Hero MotoCorp
 Maruti WagonR Flex Fuel: What’s price of India’s first ethanol car? Specs, mileage, and top features explained
BUSINESS
The sectors (read pharmaceuticals and information technology) which used to provide safety in the falling markets historically have now actually failed miserably in the rising markets

Updated : May 30, 2017, 07:35 AM IST

On 10th November 2015, we discussed how defensive stocks (in IT and pharma space) are no longer defensives in nature on the domestic equity markets. Since then, while the combined market cap of top five pharma stocks fell by a whopping 27.5%, the same for top five IT companies fell by lesser extent at about 2% as of yesterday. However, the Sensex has moved up 21% from 25,743 on 10 November 2015, to around 31,100 yesterday.
The sectors which used to provide safety in the falling markets historically have now actually failed miserably in the rising markets.
The pharma space has underperformed by 50% in comparison to Sensex in this period. The stringent regulatory norms and pressures on realisation in the export markets have primarily led to the destruction of wealth in the pharmaceutical sector.
The base effect of the IT exports, uncertainty regarding the visa issues and slowdown in the global growth are the reasons behind poor performance of large IT companies since November 2015.
About five years ago, the number of Indian pharmaceutical companies getting observations/alerts/warnings from the US FDA (regulator) was a small proportion of the total number of companies. But now it is very difficult to find out which pharma company in India hasn’t received such adverse reactions from the regulator.
For the large IT companies, the year-on-year revenue growth in the US dollar term first slipped into single digit, then since the December 2016 quarter, they started growing in single digits even in rupee terms. It is going to be very difficult to get back to strong double-digit revenue growth as the base of India’s annual exports has grown beyond $100 billion.
However, the stock prices of some of the large pharmaceutical companies have crashed more than 50% from their 2-year peak prices and are trading at roughly half their valuation (PE) multiples that they commanded about 3 years ago. Similarly, the IT stocks’ valuation multiples have also shrunk to around 13 to 14 times on one-year forward earnings as compared to over 20 times 3-4 years ago.
Most of the large IT and pharmaceutical companies continue to enjoy strong balance sheets with either a significant amount of cash or a low debt and solid working capital management system. Thus, cheap valuations and strong balance sheets could make some of these large companies in the so-called defensive sectors to become real defensive stocks in the near future.
The writer is founder and managing director, Equinomics Research and Advisory